false
Category
Author
Search for Articles
Trending Keywords
Category
Author
Search
Category
Author
Search
Retirement and Annuity
Savings and Investment
Editor's Pick

Short-term savings insurance VS “modified deferred annuity”: comparing returns

2019-05-26 3min read
short-term-savings-vs-deferred-annuity-return-comparison-kv.png
Recently, a qualifying deferred annuity product (QDAP) has appeared on the market – BOC Life Deferred Annuity (Fixed Term)
After completing the 5-year premium payment period, policyholders can surrender the policy and recover their premiums, enabling high-income policyholders to make full use of the tax deductions during the premium payment period and achieve a decent return. This “variant deferred annuity” effectively offers an effect similar to that of a short-term savings insurance product, attracting considerable interest from readers. If the objective is to pay premiums for a short period, recover the premiums and earn interest, which is more advantageous: a “variant deferred annuity” or short-term savings insurance? What should you pay attention to? Insurance comparison platform 10Life breaks it down for you.
 
Comparing the internal rate of return
When comparing a “variant deferred annuity” with short-term savings insurance, we calculate the product’s guaranteed internal rate of return (IRR).
 
The “variant deferred annuity” relies on tax deductions as the return upon surrender at the end of the premium payment period. Its return depends on the marginal tax rate. Based on the highest marginal tax rate of 17%, its internal rate of return is 5.9%. However, if the policyholder has a lower income and their marginal tax rate is below 17%, the amount of tax saved will be lower, resulting in a lower internal rate of return. The following shows the “internal rate of return” calculated for an annual premium of $60,000 for “BOC Life Deferred Annuity (Fixed Term)” under different tax rates:
 
Taxable income
after deducting all allowances
Marginal tax rate
Annual
tax savings
“Internal rate of return”
of the “variant deferred annuity”^
$120,000
6%, 10%
$4,400
2.5%
$180,000
10%, 14%
$7,200
4.1%
$240,000
14%, 17%
$9,600
5.5%
$300,000
17%
$10,200
5.9%


^Calculation of the internal rate of return: assuming that a 45-year-old man takes out “BOC Life Deferred Annuity (Fixed Term)”, surrenders the policy immediately after completing the five-year premium payment period, and treats the tax deduction for the “qualifying deferred annuity” as the policy’s return.
 
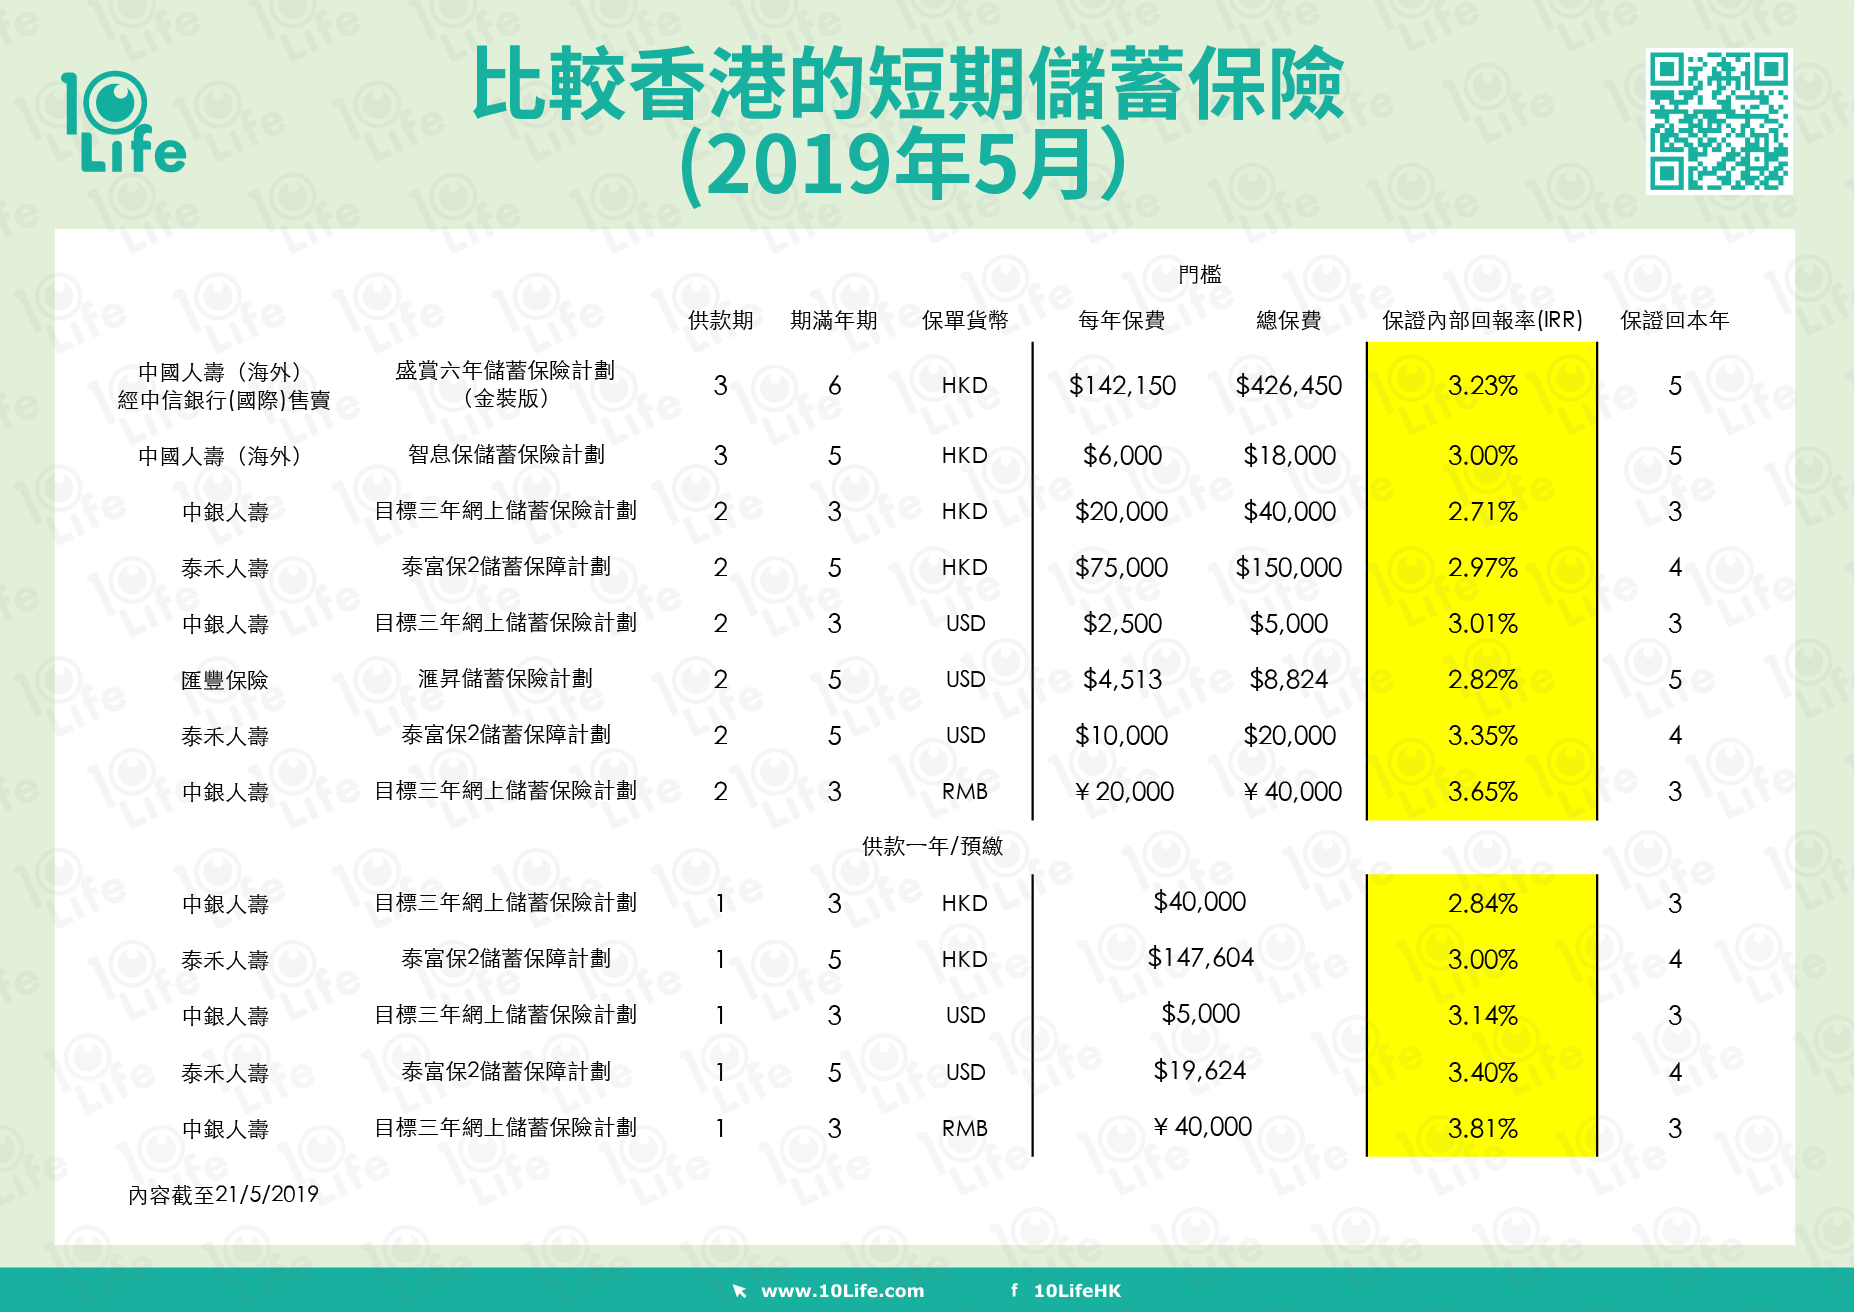
As for the short-term savings insurance products currently available on the market, the policy terms are generally around 3–6 years, and the guaranteed internal rates of return vary between products. Details are as follows:


Deferred annuities are primarily for retirement; tax saving is not the main purpose
The internal rates of return of short-term savings insurance products currently on the market are generally around 2.7–3.8%, lower than the tax-saving return of a “variant deferred annuity”. Does this mean that a “variant deferred annuity” is the better choice? Please note the following:
  • The annual tax-deductible limit for a “qualifying deferred annuity” is $60,000. To achieve the highest “internal rate of return”, the annual premium for a “variant deferred annuity” should not exceed $60,000. Otherwise, the additional premiums will not be eligible for tax deductions, bringing down the overall internal rate of return;
  • Both short-term savings insurance and “variant deferred annuities” have an “entry threshold”. The annual premiums required to take out short-term savings insurance products range from several thousand dollars to over $100,000, while the entry threshold for the BOC Life “variant annuity” is HK$36,000 per year;
  • Using a “variant deferred annuity” as short-term savings to earn tax deductions means that the return depends entirely on the tax deductions. However, the purpose of the Government’s tax incentives is to encourage members of the public to prepare for retirement early, rather than allowing everyone to exploit a tax loophole for gain. Therefore, if the Government changes the tax incentives, policyholders may find that the outcome falls far short of their expectations. You should therefore understand the long-term returns and retirement protection offered by deferred annuity products. If a policyholder chooses to continue holding the policy for 15 years until maturity and receive annuity income regularly, the guaranteed internal rate of return will be 5.1% (based on a marginal tax rate of 17%).


10Life has also compared the various deferred annuity products available on the market. For details, please visit our annuity “Insurance Decoder”.

This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

Disclaimer

10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com

Whatsapp icon
Whatsapp icon
WeChat icon
WeChat icon
Enquiry icon Close icon
Back To Top
Whatsapp icon
Whatsapp icon
WhatsApp