false
Category
Author
Search for Articles
Trending Keywords
Category
Author
Search
Category
Author
Search
Savings and Investment
Editor's Pick

Compare the fee erosion of 7 investment-linked insurance products across 12 different scenarios

2021-11-15 10min read
7-ILAS-Plans-Compared-in-12-Different-Scenarios-kv.png
Following the SFC’s issuance of new guidelines on investment-linked assurance schemes (ILAS), major reforms will be introduced within 18 months. However, these products remain available on the market, with complex charges continuing to be a nightmare for consumers. Using seven single-premium investment-linked insurance products currently available on the market as examples, 10Life clearly sets out the total fees and charges disclosure (TFCD) percentages, as well as the policy values based on different policy terms and assumed rates of return, showing the extent to which fees erode returns under the same assumptions.
 
Some members of the insurance industry have put forward constructive proposals in recent months, pointing out that comparing only three ILAS products is insufficient, that there are too few assumed scenarios, and that the impact of Mirror Fund on ILAS charges has not been considered.
 
10Life has conducted a more in-depth study this time, expanding the scope to seven products currently available on the market. Six of the products provide death benefits of 105% of the account value, while one provides at least 105% of the premiums paid. More scenarios have also been included, with a comprehensive comparison based on three policy terms (10, 20 and 30 years) and four assumed rates of return (0%, 3%, 6% and 9%). This study examines which ILAS products have the greatest overall fee erosion, which have relatively lower fees, and whether Mirror Fund has a decisive impact on charges.
 
ILAS fee “heat map”

 
The chart below ranks the seven ILAS products under different scenarios. In simple terms, based on the same assumptions — a 40-year-old male paying a single premium of HK$1 million — the total expected policy value of each company is ranked against its peers under different TFCD percentages, policy terms and assumed rates of return. This effectively reflects the extent to which the relevant products’ charges erode returns.
 
Taking the TFCD percentage as an example, red represents a higher figure and green represents a lower figure. For policy value, green represents a higher value and red represents a lower value. “Appendix 1” sets out the actual data in detail for reference.
 
It is worth noting that the TFCD percentage only includes all applicable non-discretionary bonuses. Other special promotional factors beyond the “Key Facts Statement” (KFS) on the SFC website are not included in this product comparison.
 
Figure 1: Comprehensive comparison of the rankings of the expected policy values of seven ILAS products
 
ILASAXA Prestige II
Single Premium Investment Insurance Plan
Sun Life
Sun Life Prosperity Investment Life Insurance Plan
Prudential
Prudential Premium Investment Plan
Manulife Investment PlanYF Life
Global Investment Single Premium Plan
FWD
FWD Fortune Plus
AIA
AIA Prosperity Elite
TFCD percentage1237654
Mirror Fund available✗✓✗✓✗✗✗
Minimum death benefit105% of premiums105% of policy value105% of policy value105% of policy value105% of policy value105% of policy value105% of policy value
Policy yearAssumed rate of returnRanking of expected policy values
Year 100%1243657
3%1242657
6%1342567
9%1352476
Year 200%1326745
3%1234765
6%1234576
9%1243576
Year 300%3217645
3%2134765
6%2134576
9%2143576
Notes:
1. The policyholder is assumed to be a 40-year-old man paying a single premium of HK$1 million.
2. For the “TFCD percentage”, 1 represents the lowest and 7 the highest. For “expected policy value”, 1 represents the highest and 7 the lowest.
3. Green represents lower charges and weaker erosion of returns; red represents higher charges and stronger erosion of returns. The products are ordered from left to right according to their overall ILAS ranking.
4. Other special promotional factors beyond the KFS on the SFC website are not included in this product comparison.
5. See “Appendix 1” for detailed data.
 
 
Expected returns from ILAS products fluctuate across different policy terms
To compare ILAS products with complex charges, it is essential to understand that different policy terms and assumed rates of return have different effects on the expected policy value. Some products have a lower expected return including principal during the early period (the 10th policy year), reflecting greater fee erosion. However, as time passes, the impact of fees may improve compared with similar products in the later period (the 30th policy year). Consumers must understand these differences.
 
At year 10, AIA Prosperity Elite ranked lowest among the seven ILAS products. Under three of the four assumed rates of return, its policy value ranked last, indicating relatively high charges. It was followed by FWD Fortune Plus and the YF Life plan. AXA Prestige ranked highest among the seven ILAS products, followed by the Manulife Investment Plan and Sun Life Prosperity, reflecting their relatively lower charges.
 
At year 20, FWD Fortune Plus, the YF Life plan and AIA Prosperity Elite continued to perform relatively poorly under different assumed rates of return, reflecting stronger fee erosion. AXA Prestige and Sun Life Prosperity continued to rank highly, while Prudential Premium improved slightly in the rankings.
 
At year 30, Sun Life Prosperity caught up and took the lead. Under assumed rates of return of 3%, 6% and 9%, its expected return including principal ranked first among the seven products, reflecting its relatively lower charges over longer policy terms and under positive-return scenarios. AXA Prestige continued to demonstrate relatively weak fee erosion due to its lower charges, while FWD Fortune Plus, the YF Life plan and AIA Prosperity Elite continued to rank relatively low.

 
TFCD percentage may not be closely correlated with actual fee erosion
As noted above, some members of the insurance industry have pointed out that the TFCD percentage does not tell the whole story. 10Life partly agrees with this view. Taking the Manulife Investment Plan, which has the highest TFCD percentage among the seven ILAS products, as an example, its charges in the 10th policy year were relatively lower than those of its peers under different assumed rates of return, ranking only behind AXA Prestige. In the 20th and 30th policy years, apart from ranking lower under the zero-return assumption, it remained in the middle of the rankings.
 
As for AIA Prosperity Elite, its TFCD percentage is not particularly high, ranking fourth among the seven ILAS products and in the middle compared with the other products. However, its overall expected policy value generally ranked relatively low under all assumed policy terms and rates of return. For the remaining ILAS products, the TFCD percentage maintained a broadly reasonable correlation with the total expected return including principal.
 
Does a Mirror Fund mean higher charges? This conclusion cannot be drawn
Some ILAS products offer a so-called Mirror Fund option, under which the insurance company replicates a fund manager’s investment portfolio by purchasing fund units. The Investor and Financial Education Council states that where an ILAS investment option is linked to an investment portfolio managed internally at the discretion of the insurance company, the fees and charges collected by the insurance company will, based on the assumptions adopted for the TFCD, be included in the total fees and charges payable to the insurance company and reflected in the TFCD percentage (see the chart below).
 
Figure 2: Explanation by the Investor and Financial Education Council


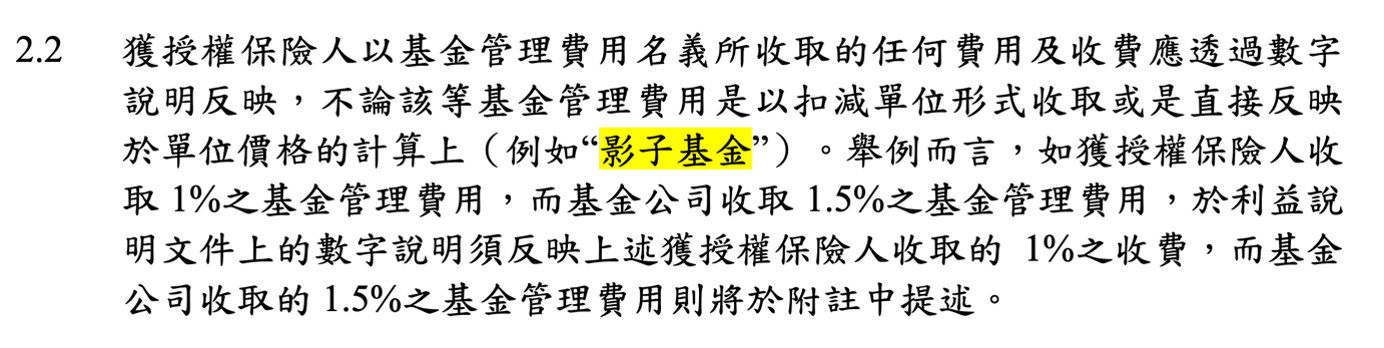
In addition, the Insurance Authority’s Guideline on Benefit Illustrations for Long Term Insurance Policies (Guideline 28) states that where a “Mirror Fund” charges fund management fees, these must be stated in the figures in the benefit illustration document.
 
Figure 3: Extract from Section 28 of the Insurance Authority’s guideline


As for the view that ILAS products with a “Mirror Fund” option have higher charges than ILAS products offering only “Direct Fund” options, our study was unable to reach this conclusion. Of the seven ILAS products mentioned above, only two offer a “Mirror Fund” option: the Manulife Investment Plan and Sun Life Prosperity. However, under many assumed return and policy-term scenarios, the expected policy values of these two products were higher than those of their peers.
 
By contrast, AIA Prosperity Elite, FWD Fortune Plus and the YF Life plan do not offer a Mirror Fund option and provide only Direct Fund options. Their overall expected returns including principal all ranked below those of their peers.
 
Consumers should not take out a policy if they do not understand the product

 
Finally, this study did not include scenarios in which the expected policy value of an ILAS product may incur a loss. After taking the impact of fees into account, the relevant loss could be even more substantial. However, the Insurance Authority does not currently require benefit illustration documents to include loss scenarios (see the article “The Disappearing ‘Loss Scenarios’ of ILAS”).
 
10Life believes that consumers must conduct extensive research before purchasing an ILAS product and should not rely on the opinion of a single broker, agent or so-called “star” agent. Consumers should read the ILAS KFS and benefit illustration document carefully, and should also refer to the relevant articles on the Investor and Financial Education Council website. The Insurance Decoder is also a useful reference. If you still do not understand the details of an ILAS product, you should not purchase it, and in particular should not fall into the sales trap of individual brokers and agents who claim that these products offer “high returns and low risk”.
 
Appendix 1: Policy values after a 40-year-old man pays a premium of HK$1 million

 
ILASAXA Prestige II
Single Premium Investment Insurance Plan
Sun Life
Sun Life Prosperity Investment Life Insurance Plan
Prudential
Prudential Premium Investment Plan
Manulife Investment PlanYF Life
Global Investment Single Premium Plan
FWD
FWD Fortune Plus
AIA
AIA Prosperity Elite
TFCD percentage15.2%16.1%17.2%27.5%25.6%24.6%24.0%
Mirror Fund available✗✓✗✓✗✗✗
Minimum death benefit105% of premiums105% of policy value105% of policy value105% of policy value105% of policy value105% of policy value105% of policy value
Policy yearAssumed rate of returnExpected policy value (HK$10,000s)
Year 100%90.788.58888.185.586.385.1
3%122119.5118119.5115.6116115.1
6%162.5159.9157160.4154.9154.5154.1
9%214.7212.1207.2213.3207.3204.1204.5
Year 200%87.184.986.279.679.180.379.7
3%158.2155.7154.2148.1143.7144.9145.1
6%280.6278.7271.5268.6262.6257259.1
9%489.6489471.1476.8465.4448.7454.5
Year 300%80.781.48471.772.874.874.6
3%203.7204200.7184.7179.9181.1183.5
6%480.8489468453.4443.5427.7437
9%1107.91134.51067.410731039986.21012.4
Notes:
1. The policyholder is assumed to be a 40-year-old man paying a single premium of HK$1 million.
2. Other special promotional factors beyond the KFS on the SFC website are not included in this product comparison.


Note:
1. This article was prepared by 10Life using market information collected through various sources and is provided for general reference only. It does not take into account any individual needs or suitability and should not be regarded as sales advice. Before taking out a policy, you should discuss an insurance solution suitable for you with a licensed insurance adviser and rely on the information provided by the insurance company.
2. The premium information above was updated as at 15 November 2021 and does not include the premium levy charged by the Insurance Authority.
3. Last updated: 15 November 2021.


Want to learn more about insurance but do not know where to find an insurance adviser? Click “Online Consultation” now!
 
•More than 1,000 licensed insurance advisers on Stand-by around the clock
•Free answers to insurance questions
•User ratings available to ensure adviser quality
•Ask questions anonymously at any time to protect your privacy

This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

Disclaimer

10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com

Whatsapp icon
Whatsapp icon
WeChat icon
WeChat icon
Enquiry icon Close icon
Back To Top
Whatsapp icon
Whatsapp icon
WhatsApp