false
Category
Author
Search for Articles
Trending Keywords
Category
Author
Search
Category
Author
Search
Medical
Personal Accident
Life Protection
Savings and Investment
Critical Illness
Editor's Pick

【Guardian God Decoded】Paid premiums but no policy issued: how can consumers protect themselves?

2019-02-13 3min read
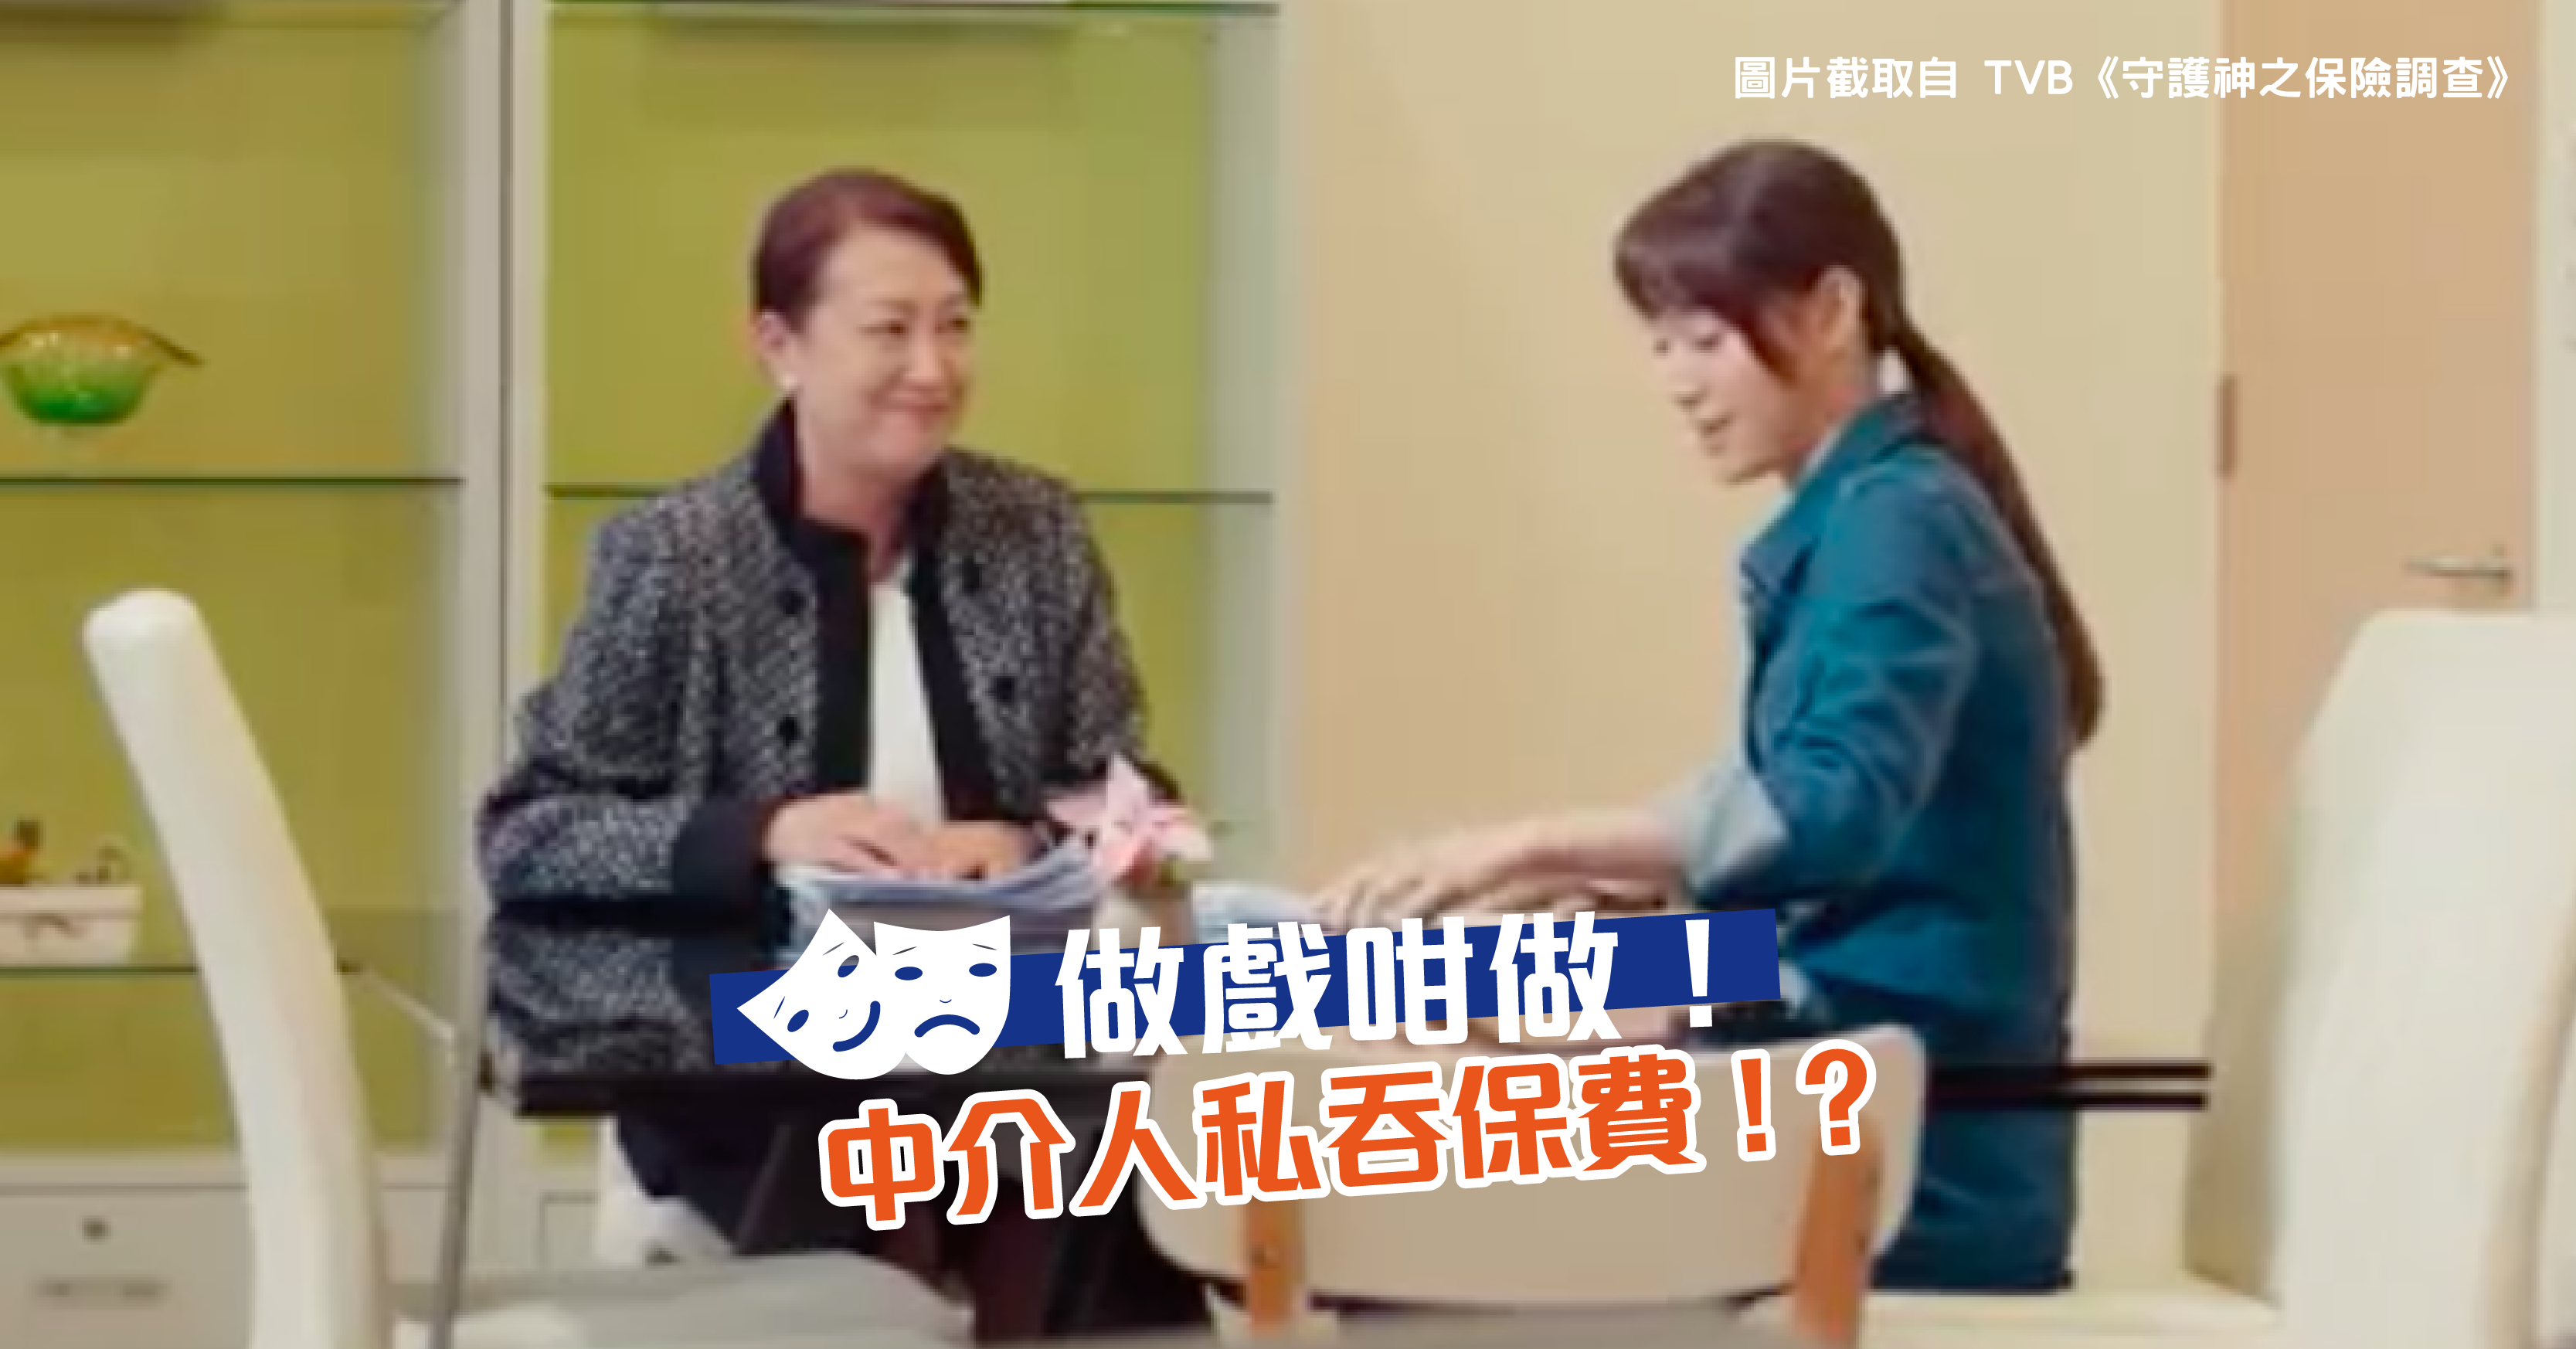
blog-TVB-Drama-Decode-No-insurance-cover-after-payment-How-can-consumers-protect-themselves-kv.png
The plot of the online drama Guardian Angel: Insurance Investigators mentions an elderly resident at a care home who claimed to have bought insurance, but discovered when applying for a surgical expense claim that he had never actually taken out a policy with the insurance company. Suspicion fell on the insurance intermediary, Yip Tze (played by Nancy Sit). Following Cheung Tung’s (played by Michael Miu) investigation, it was discovered that the care home director had committed fraud: although multiple policies had been signed, he had not arranged insurance for all of them through Yip Tze, but had instead secretly kept most of the premiums. So, in reality, how can we avoid similar incidents?
 
An Inconceivable Plot: The Care Home Director Selling Insurance on Someone Else’s Behalf?!
The director collected premiums and policy applications at the care home on behalf of the insurance intermediary, before passing them to Yip Tze to process with the insurance company. In this situation, if the director did not hold an insurance intermediary licence but sold insurance products to others, this would constitute a breach of the relevant insurance regulations.
 
In addition, as an insurance intermediary, Yip Tze had a responsibility to meet customers when arranging policies, understand their needs in a professional and responsible manner, and verify that the policyholders genuinely existed. For certain types of insurance, such as whole-of-life critical illness insurance, the intermediary must also conduct a financial assessment of the policyholder before purchase.
 
Policyholders Should Know How to Prevent Intermediaries from Misappropriating Premiums
 
The misappropriation of premiums described in the drama is not uncommon. According to data from the Insurance Agents Registration Board, more than one-third of complaints^ involve insurance agents misappropriating premiums or mishandling premium payments. How can we avoid this?
 
When purchasing insurance, we should ensure that payments are not mixed with the intermediary’s personal funds and retain records of payment.
 
If you take out insurance through an insurance agent, Guideline 5 of the Insurance Agents Registration Board (see Note 1) recommends the following preferred methods of paying premiums:
 
  1. payment by cheque made payable to the insurance company*; or
  2. payment by credit card/direct deposit/direct transfer from the customer’s bank account to the insurance company’s account
 
*(Editor’s note) If insurance is arranged through a brokerage company (broker), the payee may instead be the brokerage company. Policyholders should check whether the brokerage company genuinely exists by consulting the registers of the Hong Kong Confederation of Insurance Brokers (CIB) or the Professional Insurance Brokers Association (PIBA).
 
As cash payments are difficult to trace, they are not an ideal method of payment. If it is genuinely necessary to pay in cash, the policyholder should pay the premium in person at the insurance company’s customer service centre or a designated location, and retain the receipt.
 
Sometimes, an insurance intermediary may ask a customer to sign a credit card authorisation form to pay the premium. When signing, the policyholder should confirm that the payee is the insurance company. When paying by bank transfer, the policyholder should check the account number to ensure that the payment is successfully transferred to the insurance company.
 
All of the above methods can effectively reduce the risk of intermediaries misappropriating premiums. Assuming underwriting is successful and the insurance company accepts the application, it will notify the policyholder and issue an official receipt, the policy and the policy terms and conditions. The policyholder should retain these documents for record purposes. If the policyholder has still not received notification from the insurance company within two weeks of paying the premium, they should make enquiries with both the insurance intermediary and the insurance company to avoid a situation in which premiums have been paid but no insurance has been arranged.
 
 
(Note 1) Hong Kong Federation of Insurers, Code of Practice for the Administration of Insurance Agents
 
^Cited from Guideline 5 of the Committee on the Code of Practice for the Administration of Insurance Agents of the Hong Kong Federation of Insurers

This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

Disclaimer

10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com

Whatsapp icon
Whatsapp icon
WeChat icon
WeChat icon
Enquiry icon Close icon
Back To Top
Whatsapp icon
Whatsapp icon
WhatsApp