









10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


10 policy currencies and multiple flexible options Take control of opportunities
12 lifetime annuity options Customise your legacy plan according to your needs
Case Study – Intergenerational Wealth Transfer15
11 death benefit payout options Let your care continue for generations
Achieve savings, retirement and legacy planning all at once while enjoying up to 30% off premiums


With the New Year comes a fresh outlook, making it the perfect time to plan for the future — why not start with financial planning? When it comes to growing your wealth in the year ahead, consider starting by choosing an insurance product that offers asset growth, retirement planning and wealth inheritance features.
Recently upgraded, the participating savings insurance plan — YF LifeProsperous Infinity Saver — offers a medium- to long-term solution that combines protection with the opportunity to grow wealth over time. It provides a choice of up to 10 policy currencies, the option to convert to 12 types of lifetime annuity, and a policy splitting feature. Together, these features meet three major goals — savings, retirement and inheritance — enabling you to prepare early for a financial blueprint to share with your loved ones, even in an uncertain future.
10 policy currencies and multiple flexible options Take control of opportunities
As a medium- to long-term financial planning solution, a flexible savings insurance plan can cater to policyholders’ evolving financial needs. Whether for overseas education or plans to immigrate, Prosperous Infinity Saver offers a range of flexible options, including the market’s widest choice1 of 10 policy currencies. In addition to the existing option of locking in bonuses, it now offers the option to unlock bonuses, enabling policyholders to take control of when to preserve and grow their wealth. Prosperous Infinity Saver can help policyholders achieve steady wealth growth while pursuing higher potential returns.
Against the backdrop of globalisation, increased population mobility means that multi-currency products are better able to meet customers’ changing needs. The policy currencies offered by Prosperous Infinity Saver have increased from nine to 10, including the US dollar, Hong Kong dollar, Macau pataca2, renminbi, pound sterling, Singapore dollar, Australian dollar, Canadian dollar, Swiss franc and euro. Policyholders can apply to exercise the “Currency Conversion Benefit”3 as early as the first policy anniversary.
The existing bonus lock-in4 feature has also been enhanced, allowing policyholders to transfer the latest cash value of reversionary bonuses5 and terminal bonuses5 to the Bonus Lock-in Account at an earlier stage—from the 15th policy anniversary to the 10th policy anniversary—where it can accumulate with interest at a non-guaranteed rate, or be withdrawn for use. This plan also introduces a bonus unlock feature6, allowing policyholders to convert part or all of the latest cash value in the Bonus Lock-in Account into reversionary bonuses and terminal bonuses one year after exercising the bonus lock-in benefit, thereby accumulating potential returns.
Managed by a professional investment team, Prosperous Infinity Saver adopts a diversified investment portfolio spanning regions, industries and market cycles. In addition to guaranteed cash value5, it offers non-guaranteed “reversionary bonuses”5 and “terminal bonuses”5, providing greater potential investment returns and enabling the policy cash value7 to grow continuously.
12 lifetime annuity options Customise your legacy plan according to your needs
Starting to save early, most people do so to prepare for retirement. Prosperous Infinity Saver allows you to flexibly convert all or part of the policy’s cash value into a lifetime annuity8, while offering a market-exclusive9 choice of up to 12 lifetime annuity options, enabling your savings to provide a worry-free retirement.
There are 12 flexible annuity payment options to choose from, including sharing the annuity with your spouse or receiving double annuity payments in the event of a critical illness or severe cognitive impairment. Payments can continue for life, regardless of how long you live, ensuring a stable source of income after retirement. From age 55 and after the policy has been in force for 10 years, you can flexibly choose to convert all or part of the cash value into an annuity.
Prosperous Infinity Saver also caters for different legacy planning needs, offering multiple flexible legacy options to help pass on your wealth through the generations:
Case Study – Intergenerational Wealth Transfer15
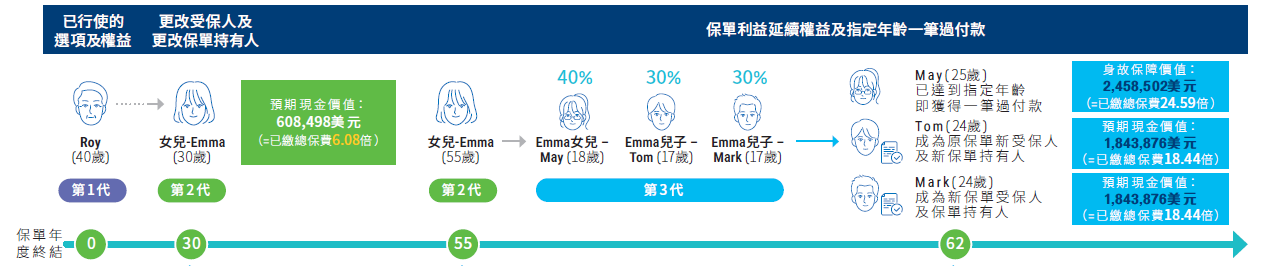
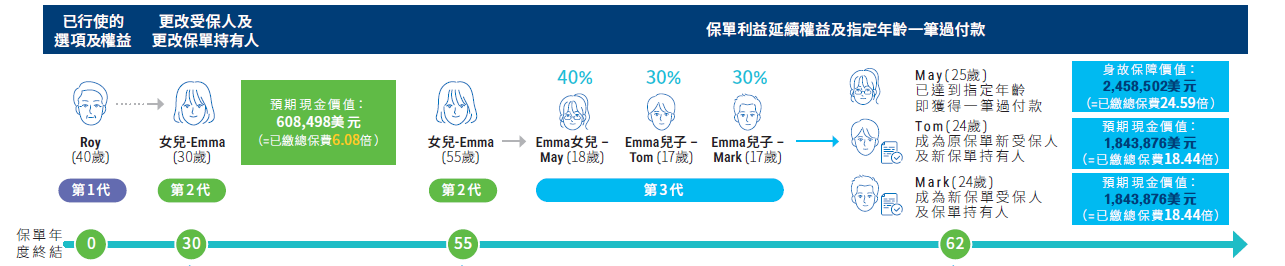
As the head of the household, Roy’s financial planning was not focused solely on the present; he also hoped to pass his wealth down through the generations. Therefore, at the age of 40, he took out Prosperous Infinity Saver, contributing a total of US$100,000 over two years. After the policy had accumulated value over the years, Roy transferred it into his daughter Emma’s name when she started a family at the age of 30. By then, the policy’s cash value had reached US$608,49816.
When Emma entered her later years, she likewise followed her father’s approach of using savings insurance to pass on wealth. She selected different death benefit payout options to plan ahead for the future of her three children, passing on the wealth Roy had left her to the third generation.
11 death benefit payout options Let your care continue for generations
Life is full of uncertainties. By making early arrangements for wealth succession, you can ensure that your wealth is passed down through generations. In addition, Prosperous Infinity Saver allows you to make thoughtful arrangements for your loved ones in advance through up to 11 death benefit payment options17.
In the unfortunate event of the life insured’s death, in addition to paying the death benefit to the designated beneficiary, the policyholder may pre-set the payment method, allowing the beneficiary to receive the death benefit through any of 11 options, such as immediate or deferred payment, or only upon reaching a specified age.
Achieve savings, retirement and legacy planning all at once while enjoying up to 30% off premiums
The purpose of saving is to prepare for the days ahead. However, the future is unpredictable. A flexible product such as Prosperous Infinity Saver provides tangible returns as life changes at different stages, together with protection that gives you and your loved ones peace of mind.
With the comprehensive upgrade of 「Prosperous Infinity Saver」, successful applications made from now until 28 February 2025 will enjoy early-bird offers including (i) a premium discount of up to 30% of the first-year premium and (ii) a promotional interest rate of up to 8% p.a. on pre-paid premiums for the first year. For details of 「Prosperous Infinity Saver」 and the promotional campaign, please visit https://www.yflife.com/tc/Hong-Kong/Individual/Save/Prosperous-Infinity-Saver/
Notes:
1. Based on comparable plans in the Hong Kong and Macau markets as at 1 December 2024.
2. Applicable only to policies issued in Macau.
3. Applicable to policies which have been in force for one year or more and have not converted all of their cash value into annuities (not applicable to policies with pre-paid premiums or policies during a premium holiday), subject to a written application being submitted within 30 days from each policy anniversary. The currency conversion option may only be exercised once in each policy year. If YF Life no longer offers Prosperous Infinity Saver when the currency conversion option is exercised, the policy will be converted to a new plan then available from YF Life, which may differ from the existing product. Before exercising this option, you should carefully assess the differences in protection, benefits and policy terms between the products, and consider whether the relevant product meets your personal needs. Following the exercise of the currency conversion option, the guaranteed and non-guaranteed policy values and the annual premium of the basic plan will be determined and adjusted based on various factors, including but not limited to the prevailing market currency exchange rates (as determined at YF Life’s discretion), the investment returns and asset values of the existing and new asset portfolios and/or the transaction for transferring assets from the existing assets to the new assets, and may be lower or higher than the corresponding values before conversion. Following the exercise of the currency conversion option, the annual premium of the basic plan must not be less than the minimum premium required under the plan. Any policy debt (if applicable) must be repaid in full before the currency conversion. For details of the currency conversion option, please refer to the terms and conditions.
4. After the policy has been in force for 10 years, a written request to exercise the bonus lock-in option may be submitted within 30 days from each policy anniversary. The minimum lock-in percentage for each conversion is currently 5% and the maximum aggregate lock-in percentage is 60%. YF Life reserves the right to determine the minimum and maximum lock-in percentages from time to time. The prevailing administrative rules must be complied with. Upon exercise of the bonus lock-in option, the reversionary bonus and terminal bonus will be reduced by the amount of reversionary bonus and terminal bonus converted, and any future reversionary bonus and terminal bonus will also be reduced accordingly at a rate determined by YF Life based on the converted reversionary bonus and terminal bonus.
5. Exercising the premium holiday and/or currency conversion option will affect the guaranteed cash value, reversionary bonus and terminal bonus. For details of the premium holiday and currency conversion, please refer to the terms and conditions.
6. One year after exercising the bonus lock-in option, a written request to exercise the bonus release option may be submitted within 30 days from each policy anniversary, to transfer the latest value of the designated percentage of the bonus lock-in account into reversionary bonus and terminal bonus. The release percentage for each release must be between 10% and 100%. The Company reserves the right to determine the minimum and maximum release percentages from time to time. The latest value of the bonus lock-in account, as at the date of approval, will be used to determine the amount to be converted into reversionary bonus and terminal bonus. The reversionary bonus and terminal bonus declared by YF Life on the relevant policy anniversary and in the future will be adjusted. The amount released from the bonus lock-in account will be converted from its guaranteed value into the non-guaranteed values of the reversionary bonus and terminal bonus.
7. Policy debt must be deducted.
8. The annuity commencement date must be a month-end date falling 10 years after the policy date and must not be earlier than the policy anniversary on which the insured reaches age 55. When the annuity option is exercised, the policy must remain in force and the policy currency must be US dollars, Renminbi, Hong Kong dollars or Macau patacas. Policies denominated in other currencies cannot exercise the annuity option, and there must be no death benefit payable under the policy. Under the prevailing requirements, the cash value used to exercise the annuity option must reach US$10,000/RMB65,000/HK$80,000/MOP80,000, must not exceed the cash value, and the remaining cash value must not be less than the minimum requirement specified by YF Life. Any supplementary benefits under the policy will terminate on the effective date of the full annuity. The annuity option may only be exercised once for each insured. YF Life guarantees the provision of Annuity Option 1 “Level Lifelong Annuity” and reserves the absolute right to revise the annuity options provided under this plan from time to time and to determine the terms and annuity amount relating to the annuity upon the first annuity payment.
9. Based on comparable plans in the Hong Kong and Macau markets as at 1 December 2024.
10. If the policyholder designates a beneficiary as the successor insured while the insured is alive, that beneficiary must submit a written request to become the new insured within six months after the insured’s death. This plan will not pay the death benefit and the policy will not be terminated. The prevailing administrative rules must be complied with.
11. During the period in which this policy is in force, the policyholder may submit an application to nominate a successor policyholder. Upon the death of the policyholder and approval of the application to change policy ownership, the new policyholder may exercise all rights conferred on the policyholder under this policy and must assume all obligations under this policy. For details of policy ownership, please refer to the terms and conditions.
12. Applicable to policies which have been in force for one year or more and have not converted all of their cash value into annuities (not applicable to policies with pre-paid premiums or policies during a premium holiday), subject to a written application being submitted within 30 days from each policy anniversary. The policy may only be split once in each policy year, but there is no limit on the number of policies created in each split. The policy commencement date and premium payment term of the split policies will be the same as those of the original policy. Under the prevailing requirements, upon each policy split, the cash value converted into each new policy must reach US$10,000/HK$80,000/MOP80,000/RMB65,000/£7,500/S$15,000/A$15,000/CA$15,000/CHF7,500/€10,000; and the annual premium of the basic plan of the portion not converted after the policy split must not be less than the minimum premium requirement. Any policy debt (if applicable) must be repaid in full before the policy split. For details of the policy split option, please refer to the terms and conditions.
13. The policyholder may pre-designate the split ratio and the policyholders of the split policies after their death. YF Life will process the relevant instructions upon receipt of the policyholder’s death certificate. For details of the policy split pre-designation option, please refer to the terms and conditions.
14. There must be an interval of at least one year between two changes of insured. Evidence of insurable interest between the new insured and the policyholder must be provided. The actual age of the new insured on the effective date of the change of insured must meet the policy’s age-at-entry requirements. YF Life reserves the right to request evidence of insurability. Following a change of insured, any supplementary benefits originally included in this policy will terminate. For details of changing the insured, please refer to the terms and conditions.
15. The figures in the case are hypothetical and for illustrative purposes only. The projected cash values are calculated based on the current projected reversionary bonus and terminal bonus, assuming that premiums are paid annually as scheduled until the end of the premium payment term, no cash value is withdrawn, no policy loan is taken, and the policy split option, currency conversion option, annuity option and premium holiday are not exercised during the policy term. The projected cash values have been rounded to the nearest whole number.
16. All projected cash values above are non-guaranteed.
17. The death benefit applies only while the policy is in force and before the annuity option is exercised for the full cash value. The death benefit does not include the reduced annual premium of the basic plan (i.e. partial surrender). Policy debt must be deducted.
The above information is provided for general information and reference purposes only. It does not form part of the policy contract and does not cover all the terms and conditions of the policy. Please refer to the policy documents and product brochure for the scope of cover, details and terms and conditions, exclusions and key product risks.
The above information is intended for circulation in Hong Kong / Macau only and should not be construed as YF Life providing, selling, soliciting the purchase of, soliciting or recommending any insurance products outside Hong Kong / Macau. If you are currently outside Hong Kong / Macau, YF Life will not be able to provide you with the relevant products and offers.
You and the relevant parties should seek independent financial, tax and legal advice. Although YF Life has exercised due care in handling the information set out above, if there is any inconsistency or ambiguity between its contents and the policy contract, the policy contract shall prevail.
Should you have any enquiries or wish to obtain a specimen of the policy documents, please contact a licensed insurance agent of YF Life or your licensed insurance broker; or call the YF Life Customer Service Hotline: Hong Kong (852) 2533 5555 / Macau (853) 2832 2622.
Last updated: 3 February 2025
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Bringing you the latest market information
1. The information of this article has been provided by the advertiser to promote its products and services.
2. The information of this article is intended for general education purpose and reference only. None of the information is intended, nor should they be considered or relied upon, as and is not, regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products.
3. 10Life Financial Limited will not be responsible for any liability, claim or loss arising from or associated with you using the information. No warranty, representation or guarantee is given by 10Life Financial Limited on the accuracy, completeness and timeliness of the information or for any claims and / or losses caused thereby.




 Talk to 10Life on WeChat
