









10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong



Understanding the Cap on the Illustrative Interest Rate Why Is There a Cap?
Market returns can be confusing to calculate
Expected cash value includes non-guaranteed returns
The break-even period may not be as expected


From 1 July this year, the Insurance Authority introduced caps on the illustrated interest rates for participating policies, stipulating that the cap for Hong Kong dollar policies is 6%, while that for non-Hong Kong dollar policies is 6.5%. Following the implementation of the measure, many people have asked what the figures of 6%/6.5% represent.
In fact, when insurance agents sell savings insurance, they often refer to numerous figures, such as rates of return and bonus rates. These figures can be highly appealing, so which rate should consumers refer to when selecting a product? The following explains each one in turn.
Understanding the Cap on the Illustrative Interest Rate Why Is There a Cap?
To prevent overly aggressive sales practices in the market, the Insurance Authority has introduced a new regulation on the “illustration rate cap”. Under the regulation, when insurance companies sell participating policies, the annualised rate of return calculated based on the projected total surrender value shown in the benefit illustration document (i.e. the total internal rate of return (IRR)) must not exceed the illustration rate cap set by the authority at 6.5% (for non-Hong Kong dollar policies) or 6.0% (for Hong Kong dollar policies). This helps prevent insurance agents and intermediaries from providing overly optimistic return projections during sales, while also managing policyholders’ expectations and avoiding significant discrepancies between expected and actual returns.
Market returns can be confusing to calculate
The structure of each savings insurance product, such as the premium payment term, investment method and return amount, varies. To calculate the time value of money, we recommend using the internal rate of return (IRR) to compare savings insurance products. However, when selling savings insurance, some agents may provide other figures to highlight policy returns, such as bonus rates. Although these figures are often quite attractive, consumers must pay attention to what those figures (%) represent and how they are calculated. For example, some providers calculate returns by comparing bonuses with the cash value, or even treat the bonus accumulation interest rate as the rate of return. This can make it easier to calculate a high return.
However, when analysing expected returns, 10Life looks at the product’s expected internal rate of return (IRR), namely the annualised return of the cash value (including bonuses) relative to the premiums paid, taking into account the time value of money. Regardless of the premium payment term, payment method or bonus distribution method of the insurance product, IRR can be used for a consistent calculation, making it easier for consumers to compare products. For details, please refer to 10Life’s Long-term Savings Insurance Product Decoder.
Expected cash value includes non-guaranteed returns
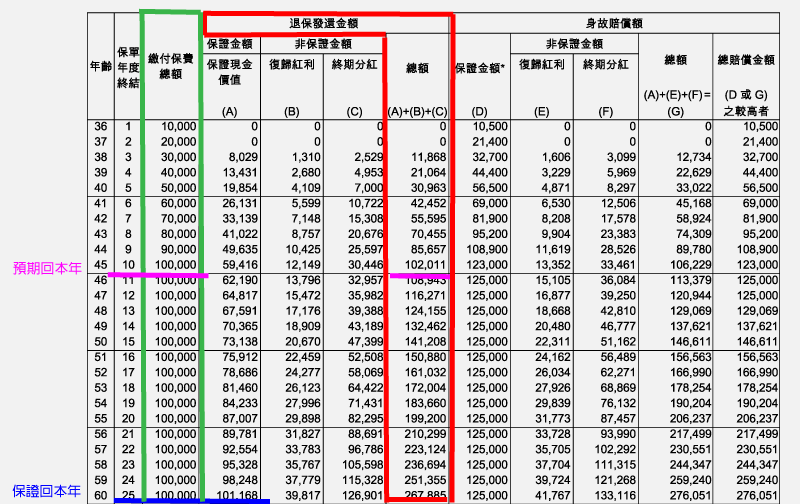
Next, readers may ask why the cash value is so low in the early policy years, far below the premiums paid. Before answering this question, it is important to understand what “cash value” means. “Cash value” refers to the amount that the policyholder is expected to receive if they surrender the policy in a particular policy year, including guaranteed and non-guaranteed components (if any). If the fulfilment ratio of the participating benefits is not as expected, the actual surrender value received by the policyholder may be lower than expected.
For example, in the illustration below, we have highlighted “cash value” in the red box and “premiums paid” in the green box. In the earlier policy years, such as the first one to five years, the “cash value” is relatively low. So where do the premiums paid by the policyholder go? Simply put, they are used to pay the adviser’s commission, the cost of insurance and the insurance company’s administrative expenses, among other things.
The break-even period may not be as expected
Another question that concerns everyone is: when will you break even? If you compare the “surrender value” with the “premiums paid”, the example below shows that in the 10th policy year, the “surrender value” is greater than the “premiums paid” (see the pink line). Therefore, the anticipated break-even year for this illustration is the 10th year. However, the “surrender value” includes non-guaranteed bonuses, dividends or interest, so the break-even year may sometimes be “delayed”.
If you would like to know the guaranteed break-even year, compare the “guaranteed amount” with the “premiums paid”. The guaranteed break-even year for this illustration is therefore the 25th year (see the blue line).
Everyone should understand that a long-term savings insurance policy is a relatively long-term “investment”. You should ensure that you have sufficient liquid funds to meet your living expenses and maintain good financial discipline by making payments on time throughout the policy payment term in order to achieve long-term wealth growth. You should also avoid surrendering the policy early, as this may result in unnecessary losses.
If you would like to know how to choose the right savings insurance policy, please feel free to contact 10Life’s insurance advisers to find a savings insurance product that suits you.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.

Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com




 Talk to 10Life on WeChat
