





10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


What are the benefits of an immediate annuity? How does it differ from fixed-term investments, the stock market and the property market?
Compare three lifetime annuity plans, each with its own features
Some products provide special withdrawal arrangements to help cover unexpected substantial medical expenses
Also featured: Policy Reverse Mortgage Plan vs Immediate Annuity


As Hong Kong’s population ages and life expectancy continues to increase, the average life expectancy for men in Hong Kong has now reached 82.5 years, while that for women is even higher at 88.1 years1. If employees consider 60 to be the ideal retirement age, retirement could last for more than 20 years. However, some people may cut back on their spending after retirement due to concerns about financial pressure, or even return to the workforce to cover their daily living expenses.
Instead of worrying about finances after retirement, it is better to make comprehensive plans for the second half of your life as early as possible. This can help safeguard your future quality of life, ease the burden on your family and enable you to enjoy your ideal retirement. Many people withdraw their MPF when they retire and, together with their accumulated savings over the years, have a considerable sum of cash in hand. Some choose to place the funds in fixed deposits with a bank, or invest in the property or stock markets. Many others consider using an immediate annuity to create a stable cash flow for their future needs and hedge against longevity risk. In this article, we compare three immediate annuity products, each with its own distinctive features, to help readers choose the immediate annuity that best suits them.
What are the benefits of an immediate annuity? How does it differ from fixed-term investments, the stock market and the property market?
Many people have a sizeable retirement fund when they retire. How this money is used will directly affect their quality of life after retirement. An immediate annuity can convert retirement savings into a stable cash flow immediately, with payments received regularly on a monthly or annual basis. It also usually offers a certain return, helping to reduce the financial pressure brought about by longevity.
In addition to immediate annuities, retirees may also consider options such as fixed-term deposits, investing in shares or property. However, each involves different risks or time costs: interest rates on fixed-term deposits are affected by changes in the economic environment, and upon maturity, consideration must be given to renewing the deposit or transferring the funds. This involves frequent ‘moving money around’, which can be inconvenient; property investment requires dealing with tenants’ requests, maintenance and vacancy issues, and the process can be complicated and time-consuming; share prices are highly volatile, meaning older people may need to monitor price movements frequently and bear the pressure of the market.
By contrast, immediate annuity products have a simple structure and can provide retirees with a long-term, stable cash flow that is not affected by market fluctuations, without requiring time to manage. For those seeking simplified financial management and a secure retirement, an immediate annuity is an effective option. It is worth noting that immediate annuities are designed to convert a lump sum into a long-term, stable cash flow, rather than to provide policyholders with flexibility in managing large sums of money.
Compare three lifetime annuity plans, each with its own features
As a retirement planning tool, an annuity can provide a stable source of income, so we need to compare products carefully in order to select a suitable one. There are not many immediate annuity products on the market. This time, we will compare three products that allow you to “buy now and receive payments immediately”: HKMC Annuity Plan offered by HKMC Annuity (wholly owned by the Government through the Exchange Fund), JoyAhead Immediate Annuity Plan from AXA Hong Kong and Macau, and Smart Immediate Annuity from BOC Life. We assume that the policyholder is a 60-year-old man who pays a single premium of HK$1 million and receives a lifetime annuity.
Assuming an entry age of 60, male, single premium (HK$1 million) lifetime annuity, with annuity payments commencing at age 60
| HKMC Annuity HKMC Annuity Plan | AXA JoyAhead Immediate Annuity Plan | BOC Life Smart Immediate Annuity | ||||
| Is the annuity fully guaranteed? | Yes | Yes | No | |||
| First-year guaranteed annuity | $61,200 | $40,800 | $48,310 | |||
| Year in which premiums are guaranteed to be recouped (including guaranteed surrender value) | 12 years | 25 years | 6 years | |||
| Guaranteed annuity | Expected annuity | Guaranteed annuity | Expected annuity | Guaranteed annuity | Expected annuity | |
| Age 75 | $918,000 | $918,000 | $612,000 | $612,000 | $518,268 | $724,679 |
| Age 85 | $1,530,000 | $1,530,000 | $1,020,000 | $1,020,000 | $794,976 | $1,207,798 |
| Age 100 | $2,448,000 | $2,448,000 | $1,836,000 | $1,836,000 | $1,210,038 | $1,932,477 |
According to Table 1, the three immediate annuity products each have their own distinctive features. The annuity payments under the HKMC Annuity Plan are fully guaranteed, with guaranteed annuity payments of up to HK$61,200 in the first year. Regardless of whether the policyholder is aged 75, 85 or 100 at the time of application, the product offers the market’s highest “guaranteed” and “expected” annuity income. AXA can also provide fully guaranteed annuity payments. Although its guaranteed break-even period (including the guaranteed surrender value) is as long as 25 years, the product has a distinctive design featuring a non-guaranteed terminal bonus, which can only be withdrawn upon surrender or the policyholder’s death. Among the three products, BOC Life has the shortest guaranteed break-even period (including the guaranteed surrender value), at just six years. However, annuity payments are fully guaranteed only during the first five years; from the sixth year onwards, they comprise both guaranteed and non-guaranteed returns.
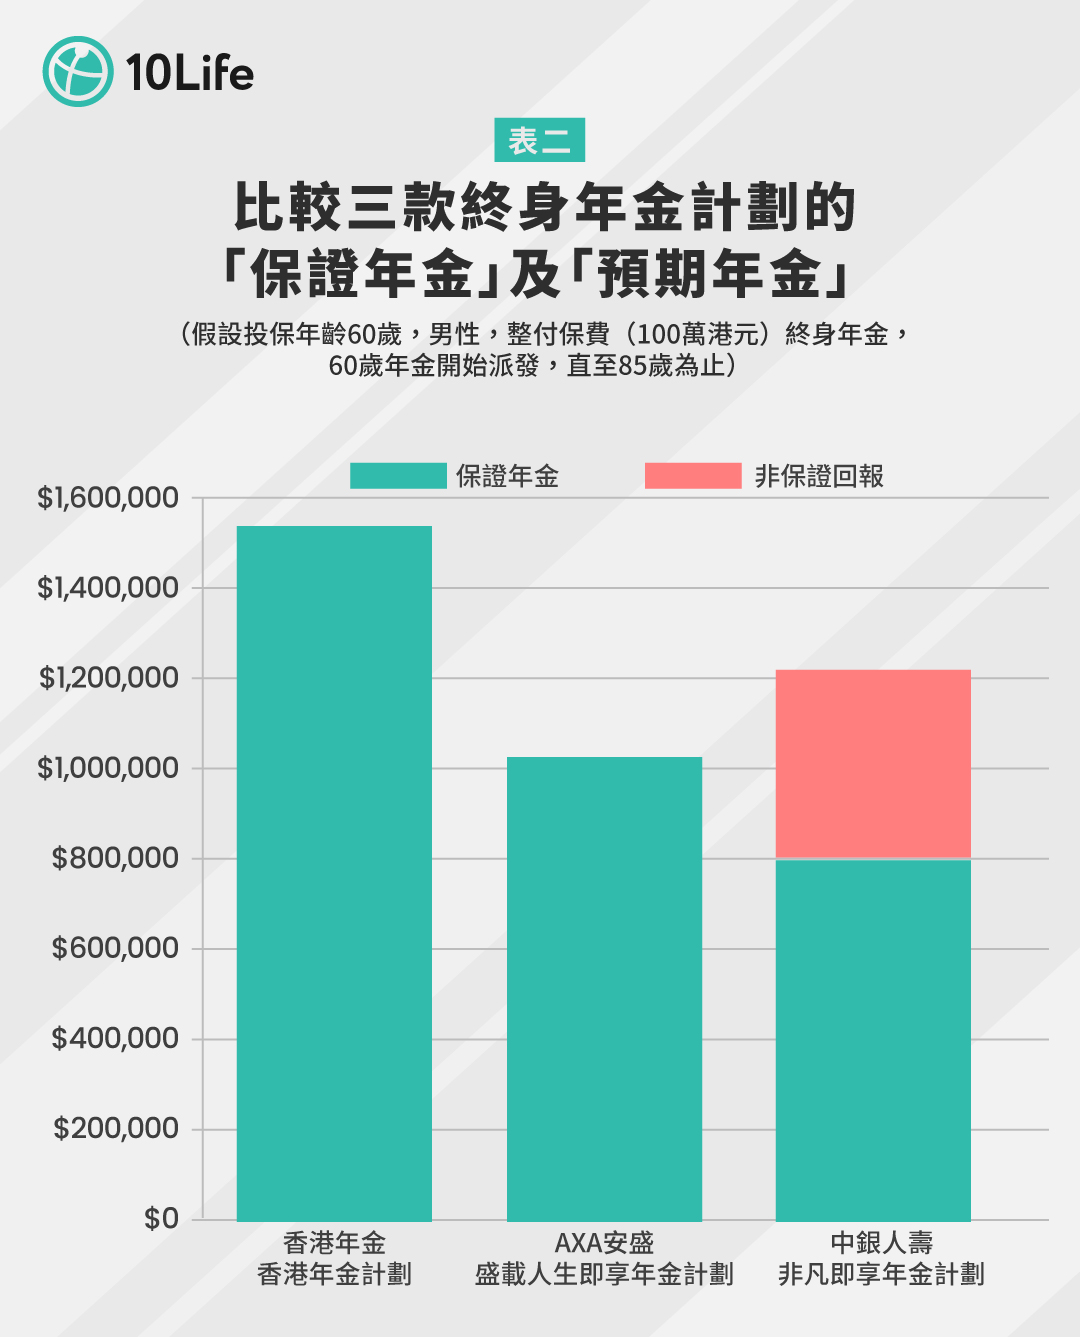
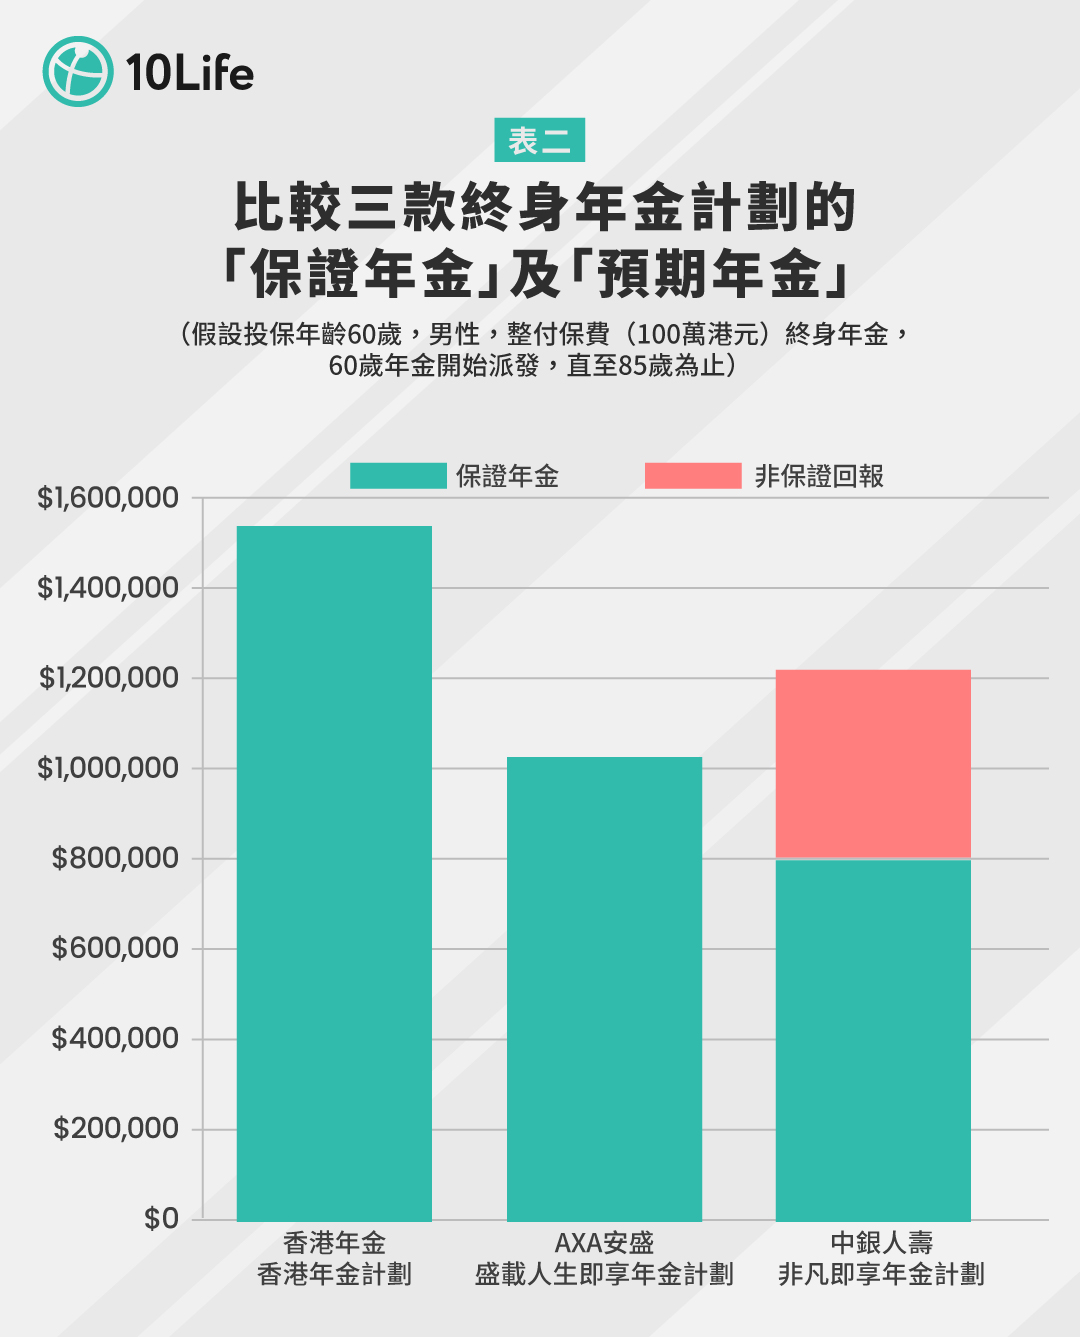
Based on Hong Kong’s life expectancy of 85.3 years2, assuming that the policyholder lives to age 85 and receives annuity payments for a total of 25 years, HKMC Annuity clearly provides a higher guaranteed return of HK$1.53 million, with annual payments of HK$61,200, or HK$5,100 per month. However, if the insured person dies prematurely and the accumulated annuity payments are still less than the premiums paid, would the insured person incur a loss? In fact, the beneficiary will receive a guaranteed death benefit, ensuring that the guaranteed death benefit plus the accumulated annuity payments exceed the premiums paid.
Of these three products, only AXA provides an expected death benefit. However, it is important to note that the “expected” figure is not guaranteed, and the actual amount may vary depending on the insurance company’s investment performance.
Some products provide special withdrawal arrangements to help cover unexpected substantial medical expenses
As the population ages, retirees are increasingly seeking a stable cash flow while also wishing to maintain liquidity, particularly if they face substantial medical expenses or require funds for emergencies. Some annuity products offer flexible withdrawal arrangements. For example, the HKMC Annuity Plan’s “Special Withdrawal Arrangement” allows the insured to withdraw up to 100% of the remaining balance of premiums paid to cover medical expenses, without incurring withdrawal charges. The lifetime aggregate withdrawal limit is HK$1 million, while the remaining balance of premiums paid refers to the premiums remaining after deducting the annuity amounts already received.
In addition, different products are designed with extra benefits to address the specific needs of the elderly. For example, AXA offers cognitive impairment protection: if the insured is diagnosed with severe cognitive impairment before the age of 80, a care benefit equivalent to 100% of the guaranteed annuity is payable monthly for 10 years. BOC Life offers life-stage rewards: when the insured experiences major life events such as getting married or the birth of a child or grandchild, a lump-sum reward equivalent to three months’ guaranteed income is paid, up to a maximum of two times.
Also featured: Policy Reverse Mortgage Plan vs Immediate Annuity
Besides immediate annuities, policy reverse mortgage plans are another option for retirees seeking cash flow. A policy reverse mortgage plan involves pledging an existing life insurance policy as collateral, borrowing from the insurer and withdrawing cash in instalments.
| Immediate Annuity | Policy Reverse Mortgage Plan | |
| Source of funds | A one-off injection of new funds | Using the value of an existing policy |
| Nature | Converting assets into cash flow | Essentially a loan |
| Longevity risk | Hedges against longevity risk; the longer you live, the more you receive | No lifetime protection; the cash may run out early |
| Points to note | An annuity is not designed to provide policyholders with flexible access to large sums of money | For a policy reverse mortgage plan, attention should be paid to the policy value and loan interest, as these may affect the policy protection |
The main difference between the two is that an immediate annuity requires a certain amount of capital to be invested for its purchase. It is a retirement planning tool that provides policyholders with a stable, long-term cash flow and effectively hedges against longevity risk. A policy reverse mortgage plan uses the value of an existing policy as collateral for a loan. It is essentially a loan, does not provide lifelong protection, and may deplete the cash value prematurely. You should also be mindful of the accumulation of interest and the impact on the protection provided by the original policy.
In fact, the choice of solution depends on your personal circumstances, including factors such as your existing asset allocation, liquidity needs and risk appetite. If you are interested in an immediate annuity or require more detailed product advice, please feel free to contact a 10Life insurance adviser via WhatsApp.
Notes:
1.Centre for Health Protection – Life Expectancy at Birth by Sex, 1971 to 2023
2.《AM730》Social Affairs Special Feature: Living Beyond 100 and Enjoying a Healthy Retirement
3. Last updated: 18 August 2025
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com


 Talk to 10Life on WeChat
