






10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong



Readers who keep an eye on social media may come across advertisements for savings insurance. Some savings insurance advertisements use “eye-catching” return figures to attract readers, claiming annual returns of more than 10%, while being both “guaranteed” and “low risk”—far more appealing than time deposits. In an environment where Hong Kong’s stock and property markets are sluggish, savings insurance may appear capable of outperforming the market. However, many users on discussion forums allege that savings insurance is a scam and complain that the returns do not meet expectations. Why is savings insurance so controversial? This article examines the two major pitfalls of savings insurance, with the hope that readers can understand the truth about savings insurance.
Dissecting Social Media’s Eye-Catching Savings Insurance Advertisements
We often see advertisements for savings insurance on social media, with very high return figures that attract readers to make enquiries and take out a policy. However, do these insurance advertisements exaggerate or overstate the facts? Are high returns accompanied by high risks? These are questions that warrant careful consideration.
Case 1
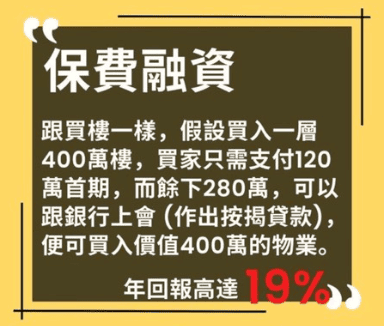
In Case 1, the savings insurance policy advertised, funded through premium financing, offers an annual return of up to 19%. When analysing the advertisement, readers should first consider whether the return is guaranteed or projected. From the words “up to”, we can tell that this is a projected return. Next, we should consider whether the 19% return is genuine. The advertisement does not explain how the return is calculated, so we are unable to verify it. However, the way to make money through policy financing is from the interest-rate spread: the policyholder can only profit when the interest earned by the savings insurance policy is higher than the interest payable on the premium financing. With interest rates still high at present, the profits from premium financing are undoubtedly being eroded, making it extremely difficult to achieve a 19% return. At the same time, we must not overlook the fact that projected returns are usually directly proportional to the potential risks, and premium financing involves considerable risks.
Further reading: 【Premium Financing】Premium financing in a high-interest-rate environment may result in losses upon exit
Case 2
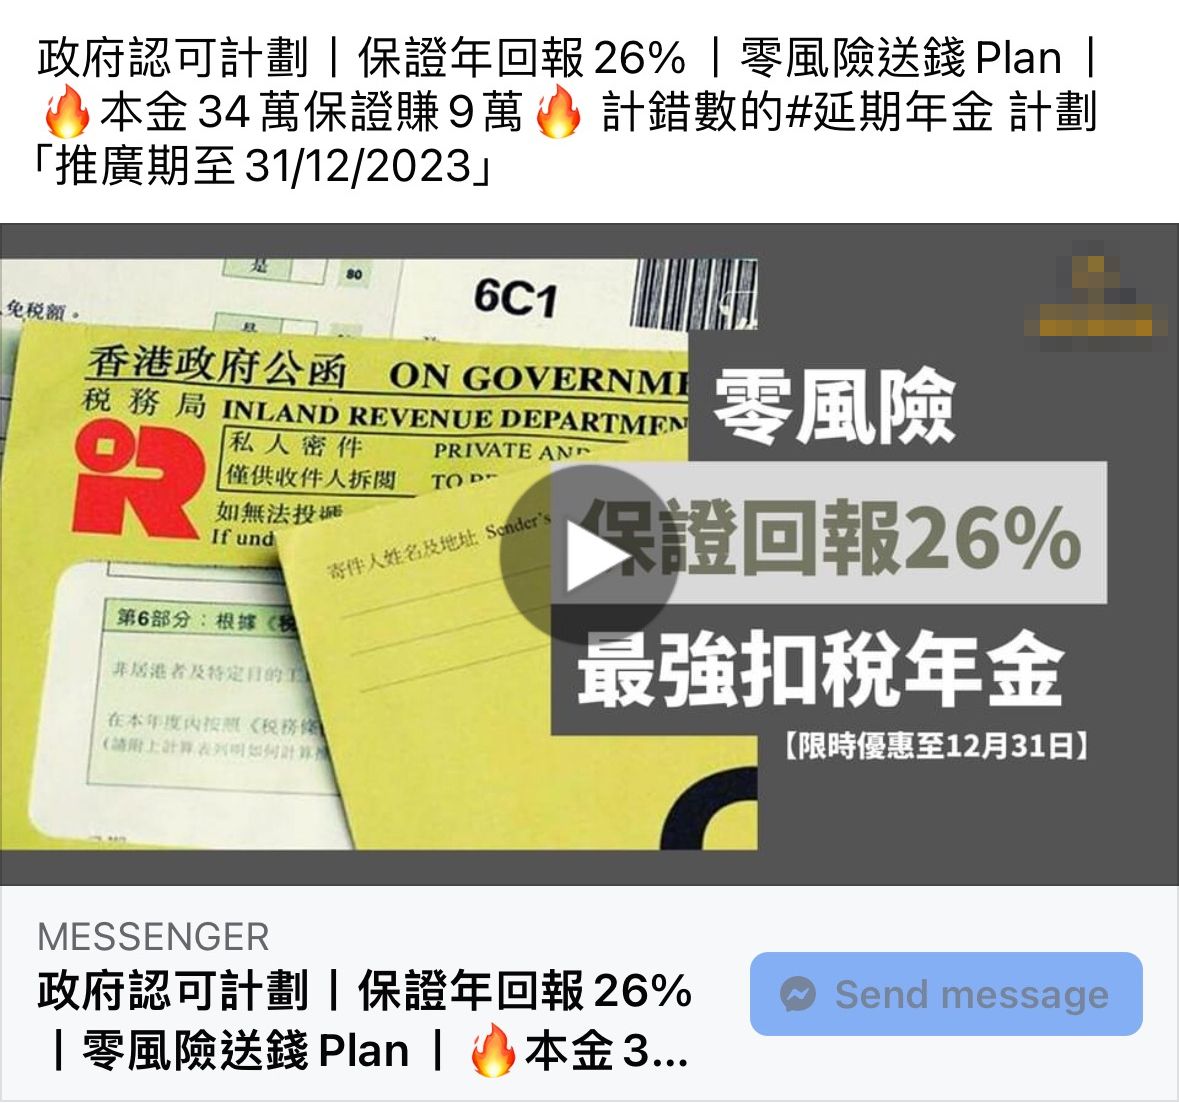
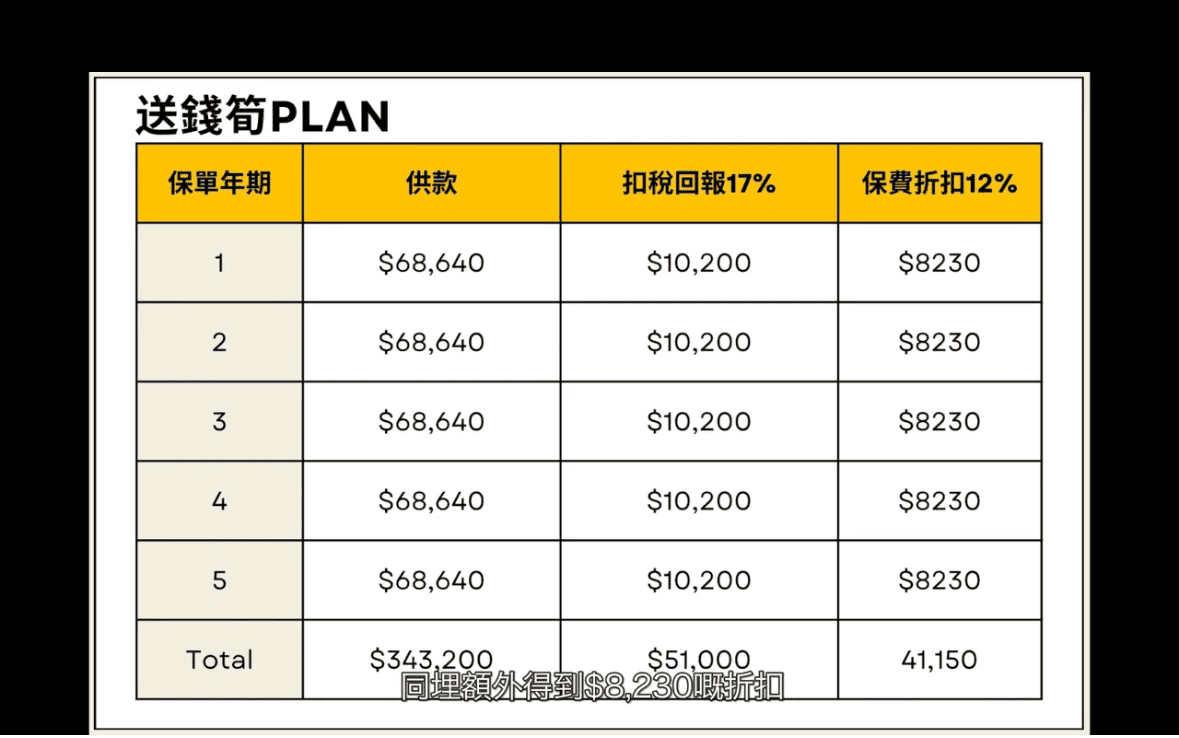
In Case 2, the advertisement claims that the tax-deductible annuity carries zero risk and guarantees an annual return of 26%, which appears highly attractive. In reality, however, this is not a return, but rather the premium savings resulting from the tax deduction (up to 17% of the premium) and premium discount (12% of the premium). The two should not be added together directly and treated as a guaranteed rate of return.
Based on 10Life’s observations, as at the time of writing, an annual expected return of 7% from savings insurance is already considered highly impressive in the market. If someone claims that savings insurance offers a higher return, readers should be particularly cautious, clarify whether the return figures are genuine, assess whether the underlying assumptions are reasonable, and take note of the potential risks.
Why Do Netizens Say Savings Insurance Is a Rip-Off? Revealing the Pitfalls of Savings Insurance
In addition to some exaggerated online marketing and sales tactics, the inherent characteristics of savings insurance have also led people to believe that savings insurance is a scam. To enhance readers’ understanding of savings insurance and help them become savvy consumers, 10Life summarises the two major common pitfalls of savings insurance today:
Savings insurance is often long-term in nature, with more significant returns arising after ten years or more. The longer the policy term, the higher the returns. If a policyholder needs to surrender the policy and cash out during the early years due to unforeseen circumstances, the cash value received may be lower than the premiums paid. Therefore, policyholders should set aside emergency funds and avoid placing all their savings in savings insurance.
The returns of savings insurance comprise guaranteed and expected returns. Guaranteed returns are those that the insurance company must provide to the insured in accordance with the contract, while expected returns (or total returns) include non-guaranteed bonuses. These are affected by factors such as the insurance company’s investment performance, bonus policy and economic conditions, meaning that the final actual amount may not be fully realised. As the expected returns of some savings insurance products do not meet expectations and their bonus fulfilment ratios are unsatisfactory, people may perceive that “savings insurance is a scam”. Therefore, the Insurance Authority issued Guideline 16, requiring insurance companies to disclose their bonus fulfilment ratios, thereby enhancing transparency regarding bonus payouts.
Further reading: 【2024 Bonus Fulfilment Ratios】Comparing the Bonus Fulfilment Scores of Major Insurance Companies
Savings insurance is one of the few financial planning tools that guarantees you will not lose money.
Although savings insurance is controversial, it still offers a number of advantages. This is particularly evident when the stock market is performing poorly, leaving investors stuck with loss-making holdings and unsure when they will be able to recover their capital. As long as the insured person is willing to allow their money to accumulate over time, savings insurance is one of the few financial planning tools that guarantees no loss of capital. For customers seeking stable returns but lacking investment knowledge, savings insurance is undoubtedly a financial planning tool for those who prefer a hands-off approach. The advantages of savings insurance are as follows:
Unlike financial products that the public commonly encounters, such as stocks or funds, savings insurance provides guaranteed returns and may also preserve the principal. As long as the insured person does not surrender the policy during its early years, allowing the funds sufficient time to accumulate, they can achieve a positive return. Many people use savings insurance for long-term investment, preparing for retirement or their children’s education in the future.
A survey found that one in every four people born in the 1990s is a “moonlight clan” member, meaning they spend all their monthly income (Note 1). This demonstrates that young people have a particularly weak awareness of saving. Where affordable, members of the “moonlight clan” may consider putting part of their income into savings insurance and making regular premium payments. This enables them to put financial planning into practice, reduce excessive spending and develop sound financial discipline, potentially bringing unexpected rewards in the long term.
Investing in stocks and bonds, as well as managing an investment portfolio, requires specialist knowledge and is not something everyone excels at. However, when you take out savings insurance, your savings are managed by a professional investment team. The insured person does not need to monitor market conditions every day, while their funds continue to accumulate and earn interest. Savings insurance is therefore also a financial planning tool for those who prefer a hands-off approach.
When it comes to “savings insurance”, some people hold it in the highest regard, while others avoid it at all costs. There are reasons why people say that “savings insurance is a scam”, but it should not therefore be regarded as entirely worthless. Before taking out savings insurance, you should first understand the product features and risks, and compare different products. Alternatively, you can consult a 10Life adviser so that you can choose an insurance product that suits your needs.
Further reading: 〈Compare savings insurance now〉
Note:
1. 〈One in four people born in the 1990s is a “moonlight clan” member〉, HKET website.
2. Last updated: 7 December 2023.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com


 Talk to 10Life on WeChat
