









10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


How do I make a claim with two medical insurance policies?
Medical Insurance Claim Procedure
Tips for claiming on 2 medical insurance policies
2 Tips for Claiming Medical Insurance


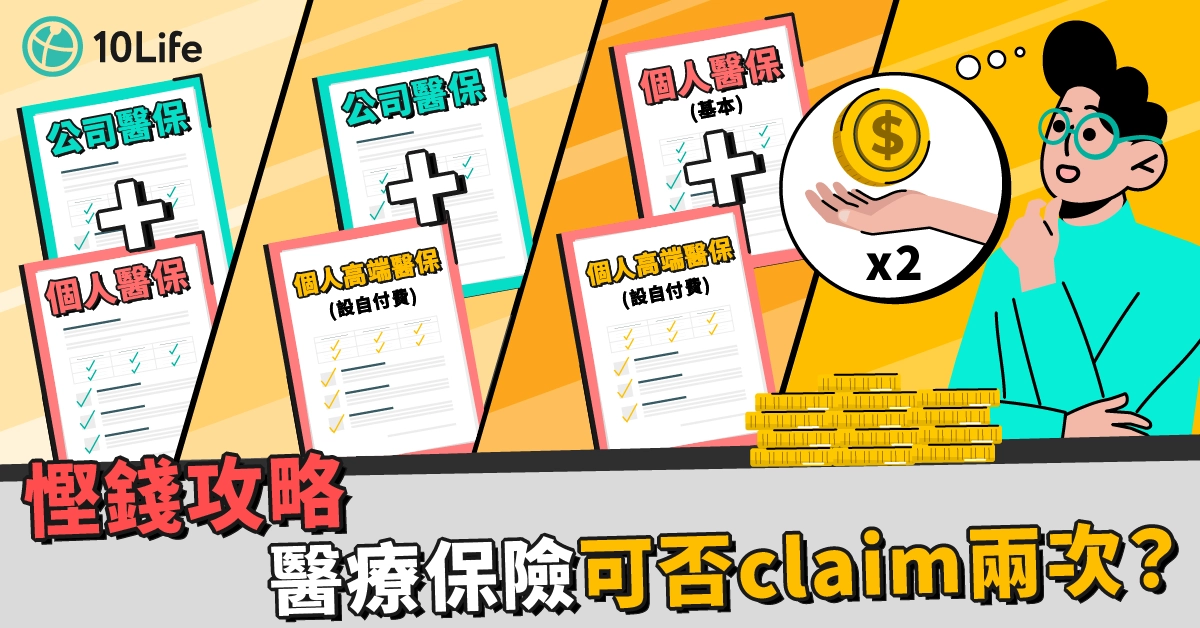
As medical expenses continue to rise, having comprehensive medical protection has become increasingly important. As a result, some people choose to purchase a personal medical insurance policy in addition to the medical insurance provided by their employer, to ensure they can obtain more comprehensive protection and a higher level of compensation when needed. However, many people do not fully understand how to make effective use of their medical insurance. Some are even unaware that they can claim from two medical insurance policies at the same time. This article will explain everything step by step.
How do I make a claim with two medical insurance policies?
Many salaried employees take out a personal basic medical insurance policy to fill the coverage gaps left by the group medical insurance provided by their employer, such as the Voluntary Health Insurance Standard Plan. In this situation, if a claim arises, you would usually first claim under the company medical insurance, and then submit a claim under the personal medical insurance for any remaining amount that has not been reimbursed. This allows the benefits of both policies to be used to the fullest extent.
Another common arrangement is to have company medical insurance as well as a top-up medical insurance plan with a deductible (also known as an “excess”). People who choose this combination of cover generally want access to more premium healthcare services, while reducing the amount they need to pay out of pocket. When making a claim, the company medical insurance may first be used to cover the deductible portion of the top-up medical insurance, after which the remaining medical expenses can be claimed under the personal top-up medical insurance. By claiming twice in this way, you can make full use of the benefits offered by both policies.
In general, many people have a personal basic medical insurance policy purchased for them by family members. However, basic medical insurance usually comes with more restrictions, such as room class and treatment items. As a result, many people choose to purchase an additional personal top-up medical insurance plan with a deductible, where affordable, in order to obtain better protection. When making a claim, the basic medical insurance may first be used to cover the deductible portion of the top-up medical insurance. Then, the remaining medical expenses can be claimed under the personal top-up medical insurance with a deductible. By claiming twice in this way, you can maximise the reimbursement available.
Medical Insurance Claim Procedure
The first step in the medical insurance claims process is to prepare the relevant documents. The policyholder must submit the claim form and supporting documents within the specified period, which generally include:
1. Claim form (some parts must be completed by the attending doctor and stamped by the hospital)
2. Original medical receipts and bills
3. Laboratory, ultrasound, X-ray, CT scan, MRI and pathology reports
4. Referral letter from a doctor or hospital
5. Copies of the policyholder’s and the insured person’s Hong Kong Identity Card
If the policyholder intends to make a claim from more than one insurer, they must prepare the claim form of the other insurer, with some sections also completed by the attending doctor and stamped by the hospital.
In addition, when making a claim with the first insurer, the policyholder must request the return of the original medical receipts or their certified copies, as well as a copy of the claims breakdown statement from the first insurer, so as to apply for a claim form from the other insurer.
After preparing the required information, you need to complete each insurer’s claim form to ensure that all information is accurate. In general, claim forms are often completed on the policyholder’s behalf by the insurance agent. If there is no insurance agent involved, you will need to complete it yourself.
The final step in the medical insurance claims process is to submit the completed claim form together with the relevant documents to the insurer. The insured person may choose the submission method offered by the insurer, such as in person, by post, by email or via a mobile app.
Tips for claiming on 2 medical insurance policies
When holding two or more medical insurance policies, it is generally advisable to first make a claim with the insurer of the company medical plan or personal basic medical insurance (the “first policy”), and then claim any remaining amount that has not been reimbursed from the personal premium medical insurance with deductible (the “second policy”). This helps maximise the benefits payable under both policies and reduce the financial burden.
Please note that the insured should submit claim forms to both insurers at the same time for record purposes, so as to avoid missing the claim deadline under the second policy while waiting for the claim result of the first policy. However, the handling of different cases may vary, and the insured should seek professional advice from an agent before making a claim.
2 Tips for Claiming Medical Insurance
Make sure the doctor completes claims forms for multiple medical insurance policies, with the hospital stamp attached.
When making a claim with the first insurer, you must ask that insurer to return the original medical receipt or provide a certified copy, so that you can more easily submit a claim to the second insurer.
When submitting the second insurance claim, remember to attach a copy of the first insurer’s claims statement and the original medical receipt, so as to speed up the claims process and ensure compensation is received smoothly.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com




 Talk to 10Life on WeChat
