









10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


Returns from participating savings policies are relatively more stable than the stock market
10Life 5-Star Insurance Awards speak through data
BOC Life wins Wealth Insurance Company of the Year 2024
Table 2: Distribution of awards won by insurers in wealth-related categories
Financial know-how: the power of compound interest


Insurance is not only a form of protection, but also a prudent financial planning tool. Among the many insurance products in Hong Kong, participating savings insurance is highly popular among the public, accounting for more than 80% of total annualised premiums in 2023. The popularity of participating savings insurance lies in its wide range of options. Policyholders can choose a suitable premium payment term or withdrawal method according to their own needs, allowing their funds to grow over time through compound returns, and helping them achieve financial goals such as education, aspirations, retirement and legacy planning.
Returns from participating savings policies are relatively more stable than the stock market
The policy value of participating policies generally includes guaranteed cash value and non-guaranteed benefits (also known as bonuses). Typically, insurers will invest part of the premiums into investment funds managed by a professional investment team, with the aim of achieving capital appreciation, so that policyholders can enjoy the benefits of participating policies without needing to take an active role or constantly keep up with market movements. In addition to investment performance, insurers will also consider factors such as claims experience and operating expenses when deciding how much bonus to distribute to policyholders.
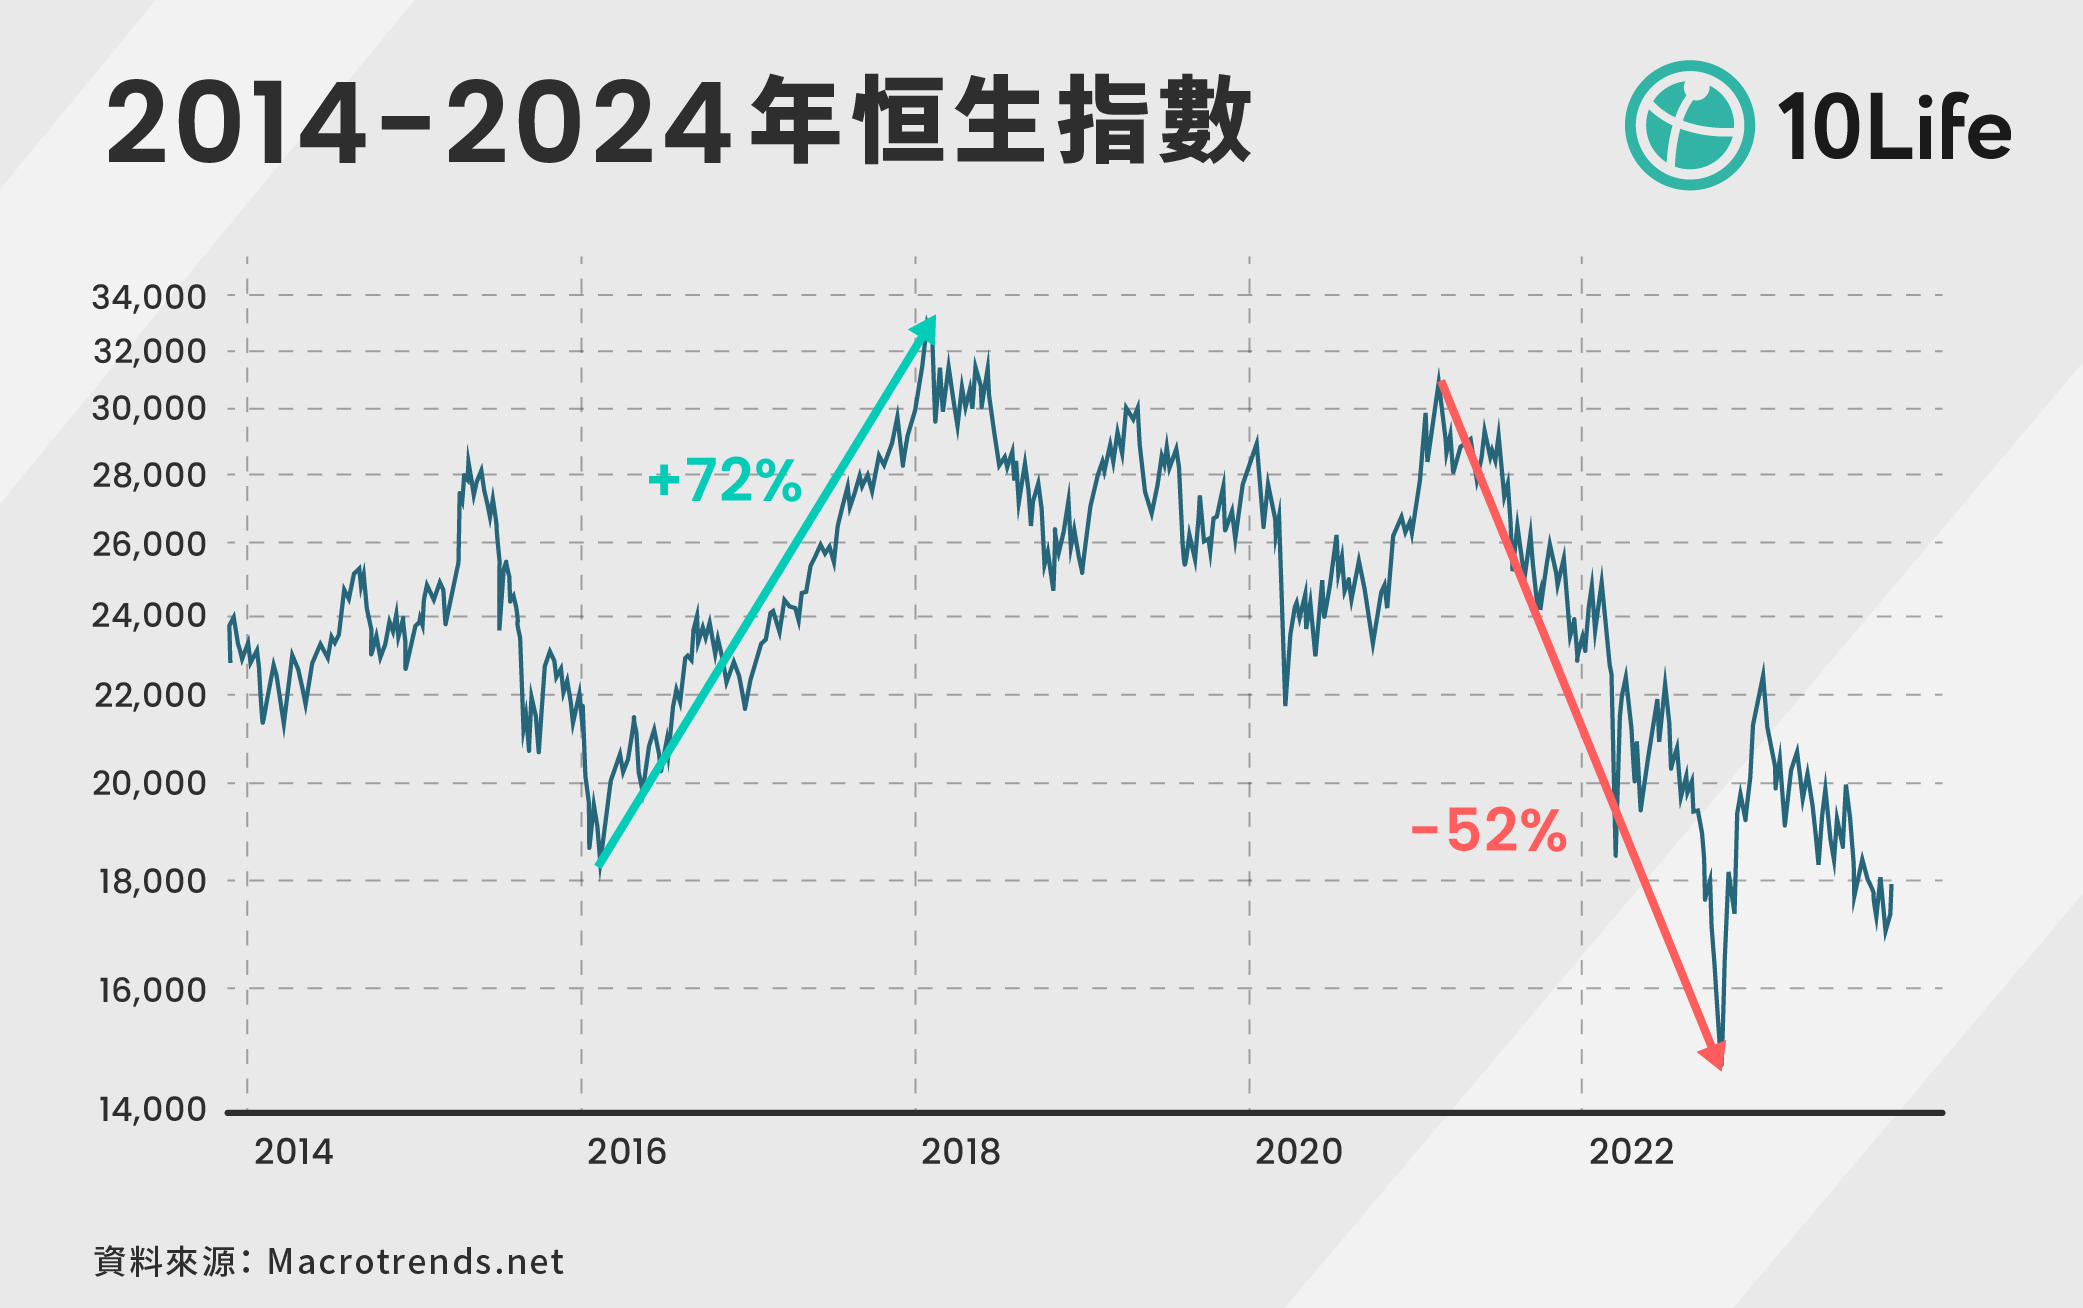
Many people compare participating policies with stock market investments, believing that the returns from the stock market are more substantial. In fact, when considering investment vehicles, one must understand the relationship between returns and risks, and how much risk one can tolerate in exchange for returns. The chart below shows the Hang Seng Index over the past 10 years. During the bull market from 2016 to 2018, the Hang Seng Index rose by 72%; however, during the bear market from 2021 to 2022, the Hang Seng Index lost 52%. If one can accurately read market trends, it is of course possible to do well in the stock market, but in reality, it is often the case that those involved cannot see the situation clearly, and buying high after selling low is even more common. To become a long-term winner in the stock market, is it really that easy?
For many members of the general public, if they do not have the energy, time or luck to face the turbulence of the stock market, yet do not want their assets to underperform inflation, participating policies may be worth considering. By cultivating a consistent saving habit over time, one can not only preserve capital but also earn stable returns. It is a convenient financial planning tool.
In addition to capital appreciation, some participating savings insurance plans also offer features such as currency conversion options, insured change options, policy split options, and different death benefit payment methods, enabling customers to use participating savings insurance as a tool for wealth inheritance. The process is simple and can cater to the needs of policyholders at different stages of life.
10Life 5-Star Insurance Awards speak through data
As market demand for participating savings insurance is substantial, insurers have launched a variety of participating savings insurance products. However, these products come in many forms and their product information is complex, involving a considerable amount of technical terminology and calculations, making them difficult for consumers to understand, let alone compare.
In view of this, 10Life has launched the “10Life 5-Star Insurance Awards”, which establish a standardised measurement framework to compare different insurance products based on data. The rating process is professional and independent, and does not favour any particular insurer.
For the popular savings insurance product category, 10Life compares savings insurance products with different premium payment terms according to four major financial goals (“Golden Decade”, “Education Planning”, “Retirement Planning” and “Wealth Transfer”), in order to identify products with more attractive returns.
Given that the bonuses of participating savings insurance products are not guaranteed, insurers are required by regulators to publish bonus fulfilment rates. However, as the data are extensive, they are difficult for the general public to digest. Therefore, the scoring criteria for the “5-Star Savings Insurance Award” take bonus fulfilment into account, analysing the average and stability of insurers’ bonus fulfilment rates, with the aim of rating participating savings insurance products on an objective basis.
Category | Target Term | Premium Payment Term | Bonus Realisation Score (Based on 2022 data) | Guaranteed Return | Expected Return* |
Golden Decade | 10 years | Single premium | 9.5 | Guaranteed to breakeven at the target term | 1.35x |
Education Planning | 20 years | 5 - 14 years | 9.0 | 2 - 4x | |
Retirement Planning | 30 years | 10 - 19 years | 8.5 | 3 - 4x | |
Wealth Transfer | 60 years | No limit | 8.5 | 19 - 42x | |
| *Expected return is calculated at the end of the product’s target term. | |||||
BOC Life wins Wealth Insurance Company of the Year 2024
In addition to rigorously selecting 5-Star savings insurance products, 10Life has established three “Insurer of the Year” awards under the 10Life 5-Star Insurance Awards to recognise insurers that have delivered outstanding performance across various financial goals, including:
As for the “Wealth Insurer of the Year” award, 10Life reviews tax-deductible annuities and savings insurance based on financial goals. Among the six insurers that have the highest number of wealth-related insurance categories, BOC Life had products rated 5-Star across all six financial goals, outperforming its peers. As a result, BOC Life received the 10Life 2024 Wealth Insurer of the Year award. Its “薪火傳承環球終身壽險計劃” received a 5-Star rating in both the “Golden Decade” and “Further Education” categories, while “非凡未來終身壽險計劃” also received a 5-Star rating in the “Further Education” and “Retirement Planning” areas. (Click here for details)
Table 2: Distribution of awards won by insurers in wealth-related categories
Savings Insurance | Tax-Deductible Annuity | ||||||
Insurer | Golden Decade | Education & Further Study | Retirement Planning | Wealth Transfer | Savings | Retirement | Longevity Risk Hedge |
| BOC Life | ✔ | ✔ | ✔ | ✔ | ✔ |
| ✔ |
| Sun Life |
| ✔ | ✔ | ✔ | ✔ | ✔ |
|
| AXA Hong Kong and Macau | ✔ | ✔ | ✔ | ✔ |
|
|
|
| FWD | ✔ | ✔ | ✔ | ✔ |
|
|
|
| Generali |
|
| ✔ | ✔ | ✔ | ✔ |
|
| YF Life | ✔ | ✔ | ✔ | ✔ |
|
|
|
| Note: Awards are based on the scoring criteria as of 15 January 2024. | |||||||
Financial know-how: the power of compound interest
Many people overlook the importance of compounding when choosing financial planning tools. The so-called compounding effect is commonly referred to as “interest on interest”. Each time an investment return is earned, the principal and returns are rolled over together. The longer the time horizon, the more powerful the compounding effect becomes.
Suppose you have HK$1 million and earn a return of 6% per year, with compounding once annually. After one year, you reinvest the full HK$1.06 million, principal and interest included. In this way, like a snowball rolling downhill, it would take only around 12 years for the principal to double. That is the power of compounding!
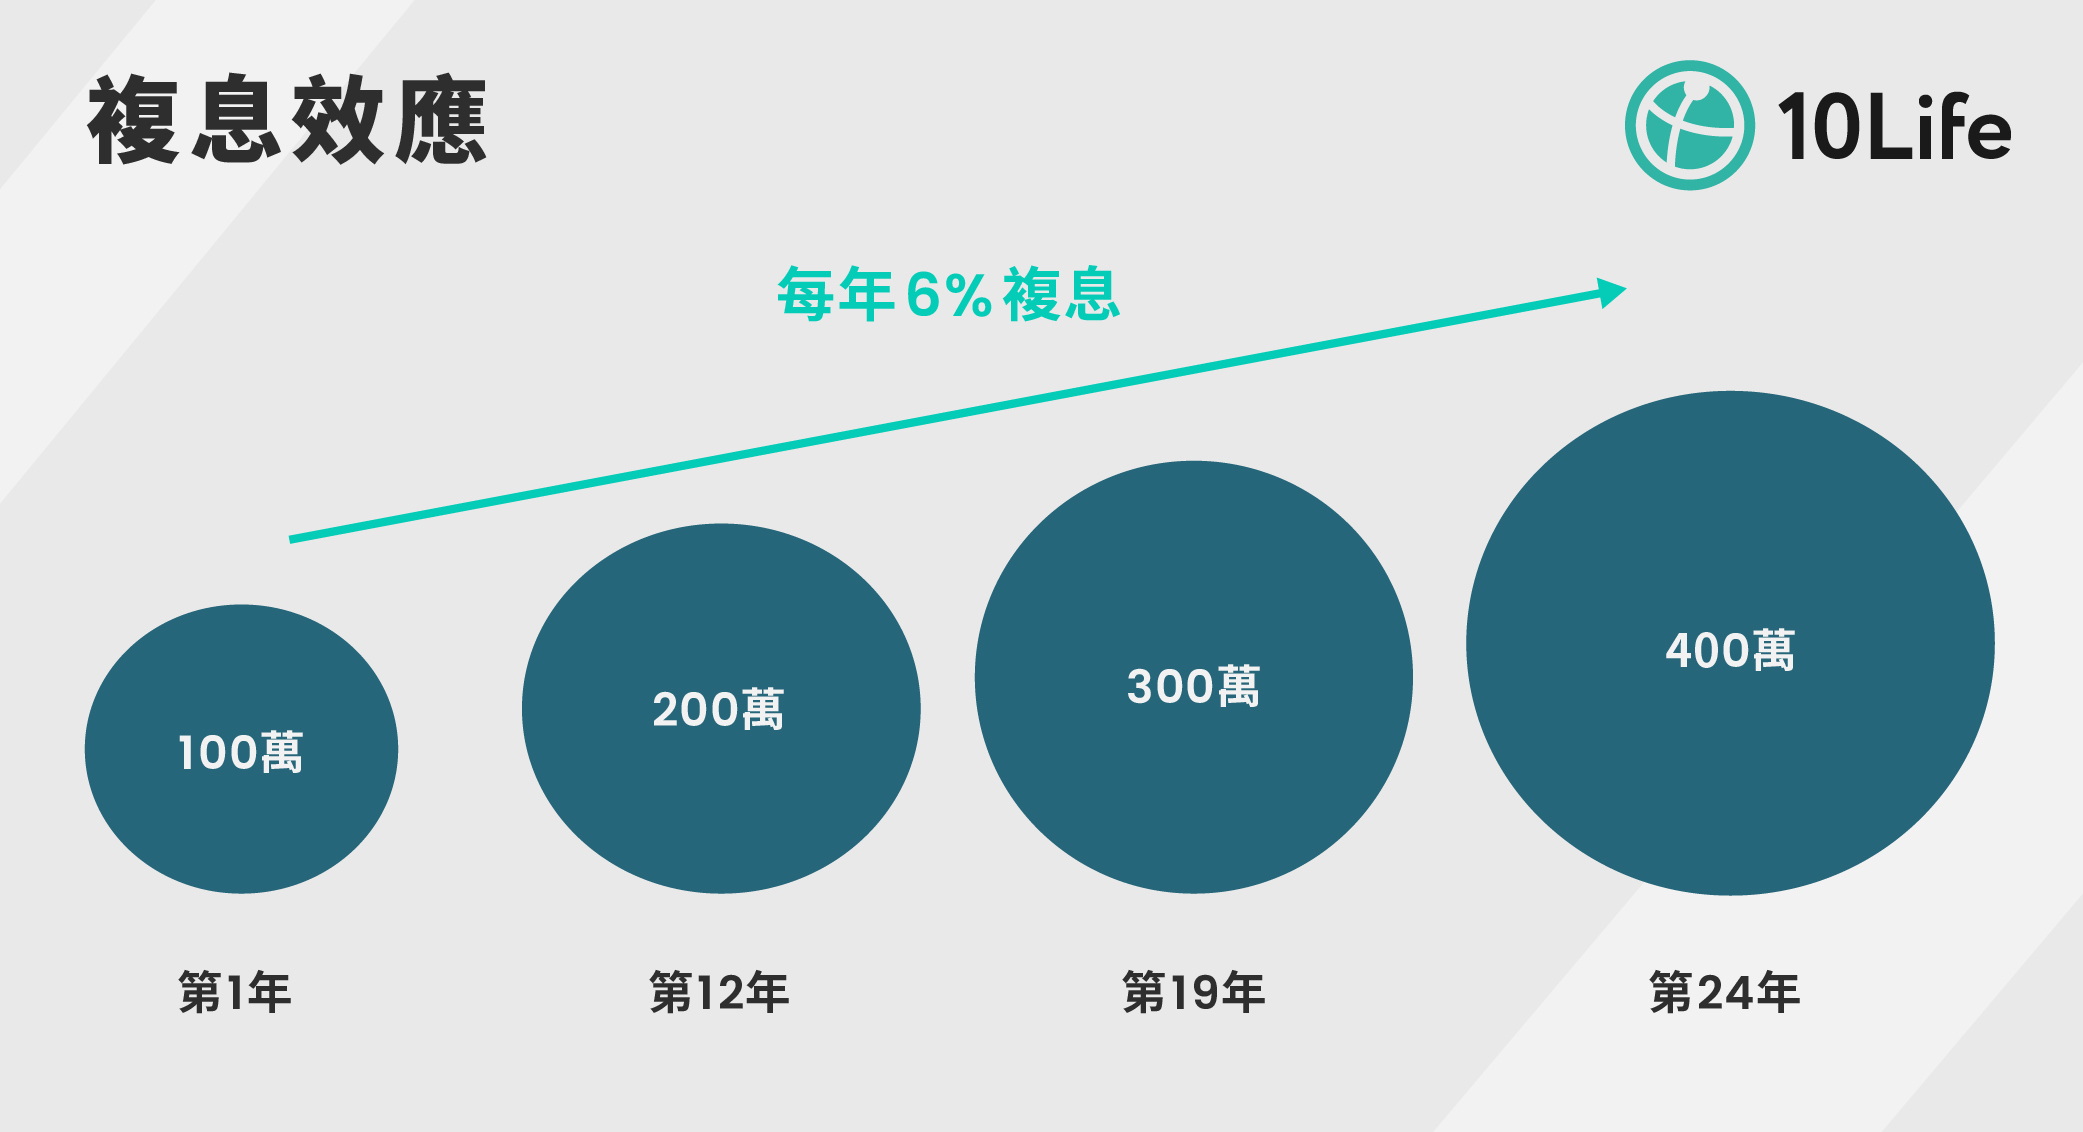
Therefore, financial tools that offer steady growth, such as participating savings policies, may not deliver returns as volatile as the stock market. However, provided the money is left to accumulate for a sufficiently long period, such as 10 years or more, the compounding effect can still generate a significant increase in value. Time is therefore capital: the earlier you start saving, the more you can harness the power of compounding.
Note:
Source: Macrotrend.net
This article was last updated on 18 November 2024
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com




 Talk to 10Life on WeChat
