

false
Category
Author
Search for Articles
Trending Keywords
Category
Author
Search
Category
Author
Search
Insurance Intermediaries
Editor's Pick

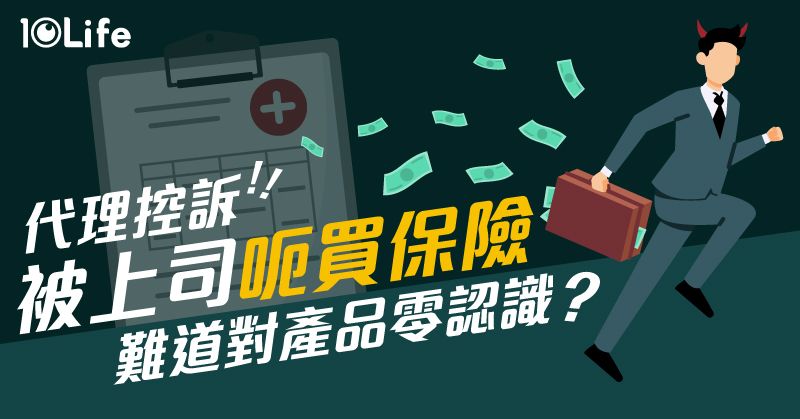
【Insurance Agent can fall into traps too】Why do agents buy the wrong products? (4 self-protection tips for consumers)

2022-07-20 3min read
How-Could-Even-Insurance-Agents-Got-Misled-into-Buying-Insurance-kv.jfif
Recently, on the programme 《東張西望》, a group of current and former insurance practitioners accused their former insurance company supervisor of misleading them into purchasing the wrong savings insurance products for themselves and their clients. The programme immediately sparked heated discussion online after it was broadcast. Many online users were also surprised that the interviewees, as licensed insurance agents, had nevertheless misunderstood the products.

Insurance agents should have a thorough understanding of the nature and key features of the products.

In terms of product knowledge, the Insurance Authority’s Code of Conduct for Licensed Insurance Agents stipulates that: “Licensed individual insurance agents and licensed technical representatives (agents) should have adequate knowledge of the nature and key features of the classes of insurance products in relation to which they may carry on regulated activities, as well as the risks covered and associated with them.”


In fact, licensed insurance agents are front-line practitioners in the insurance industry and serve as a bridge between policyholders and insurance companies. One of their key functions is to provide prospective policyholders with product information and advice, and they must therefore possess a certain level of product knowledge.

Is there a gap in the product training monitoring mechanism?

The customary practice in the insurance sector is that, in addition to obtaining a licence from the Insurance Authority, licensed agents must comply with continuing professional development requirements and complete internal training provided by the insurance company before they can sell insurance products. If the training materials contain errors, agents may mislead customers, thereby affecting their interests. In the case featured in 《東張西望》, the interviewees stated that they had acquired all their insurance knowledge through their supervisor, and provided audio recordings of part of the product training process as evidence that their supervisor had misled them.


If the interviewees’ accounts are genuine and complete, one cannot help but ask whether there is room for improvement in the licensing mechanism for insurance advisers. Should the Insurance Authority raise the licensing standards or impose additional training requirements? Secondly, do insurance companies have mechanisms in place to monitor the quality of their internal training—for example, requiring training sessions to be recorded and conducting regular random audits?

4 Ways Consumers Can Protect Themselves

However, even if some insurance agents have varying levels of competence and only a limited understanding of insurance products, consumers need not worry. They can respond by following these 4 methods:


  1. When applying for insurance, agents are responsible for providing information such as the product booklet, Product Summary and Policy Benefit Illustration (where applicable) for the applicant’s reference. Applicants can conduct their own research to gain a better understanding of the product features.
  2. If you have any questions about a product, in addition to making enquiries with a licensed insurance agent, you can also contact several licensed insurance consultants, including 10Life insurance consultants, to ensure that you correctly understand the policy details.
  3. Readers can also use 10Life’s Insurance Decoder to compare the advantages and disadvantages of products, free of charge.
  4. Some policies, such as life insurance and the Voluntary Health Insurance Scheme, have a “cooling-off period”. If the applicant ultimately considers the insurance product unsuitable, they can notify the insurance company to cancel the policy during the cooling-off period and receive a refund of the premiums paid.
 
Note: The last updated date of this article was 18 July 2022.

This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

Disclaimer

10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com

Whatsapp icon
Whatsapp icon
WeChat icon
WeChat icon
Enquiry icon Close icon
Back To Top
Whatsapp icon
Whatsapp icon
WhatsApp