









10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


In the past, as parents, providing for their children’s education was considered fulfilling their responsibility. But in today’s highly competitive society, some parents with greater financial means not only send their children overseas to study, but also help them purchase property, while planning their own retirement so as to relieve their children of the burden of supporting them until the end of their lives, and even hope to leave an inheritance for their children.
These tasks, which may seem difficult to achieve, are in fact not necessarily a dream if parents plan ahead and use savings insurance for wealth management. With wealth compounding over a long period of time, it can help children face different challenges at different stages of life. 10Life has compiled five multi-currency savings insurance plans to compare whether they can help policyholders achieve their life-planning goals.
To compare different products, we need a reasonable and standardised “starting point”. This time, 10Life assumes that parents take out a multi-currency savings plan from a major insurer, then withdraw funds at key stages of their child’s life, and finally compares the remaining cash value of each product when the policyholder passes away at an advanced age.
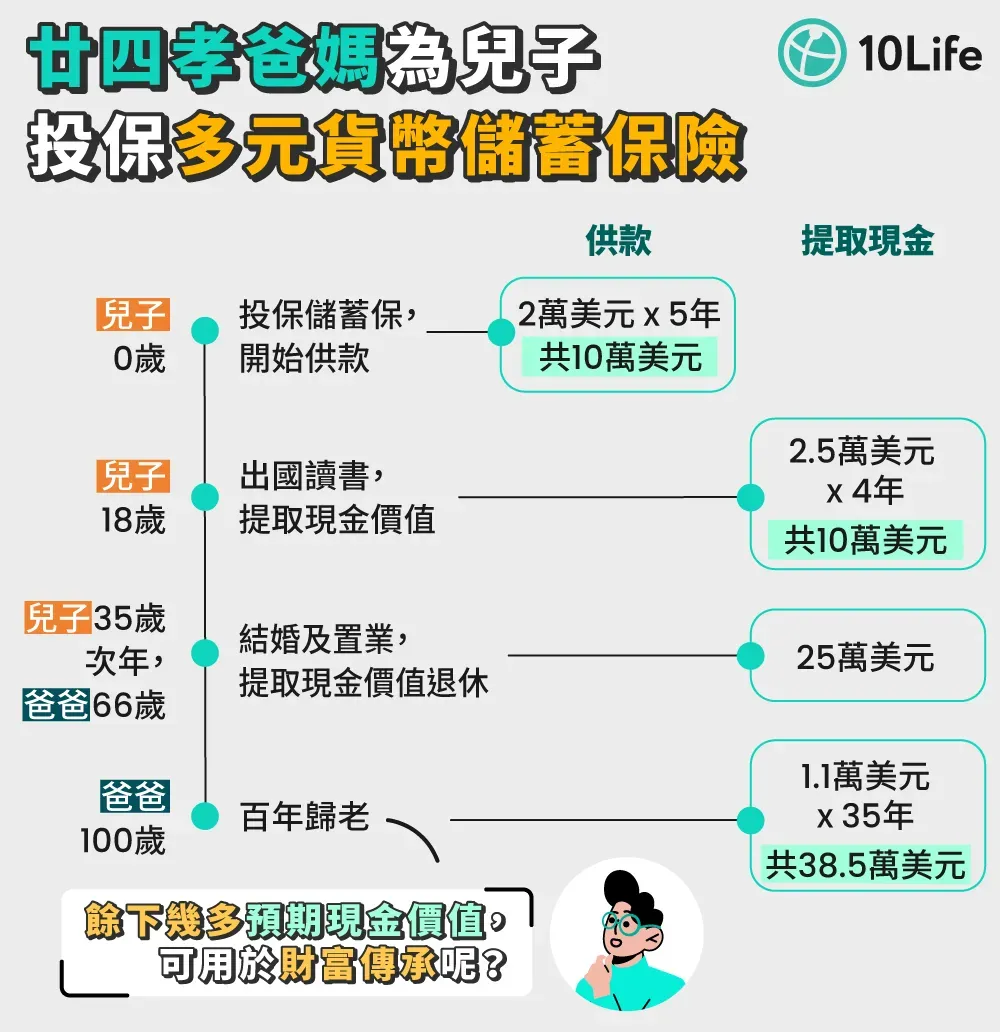
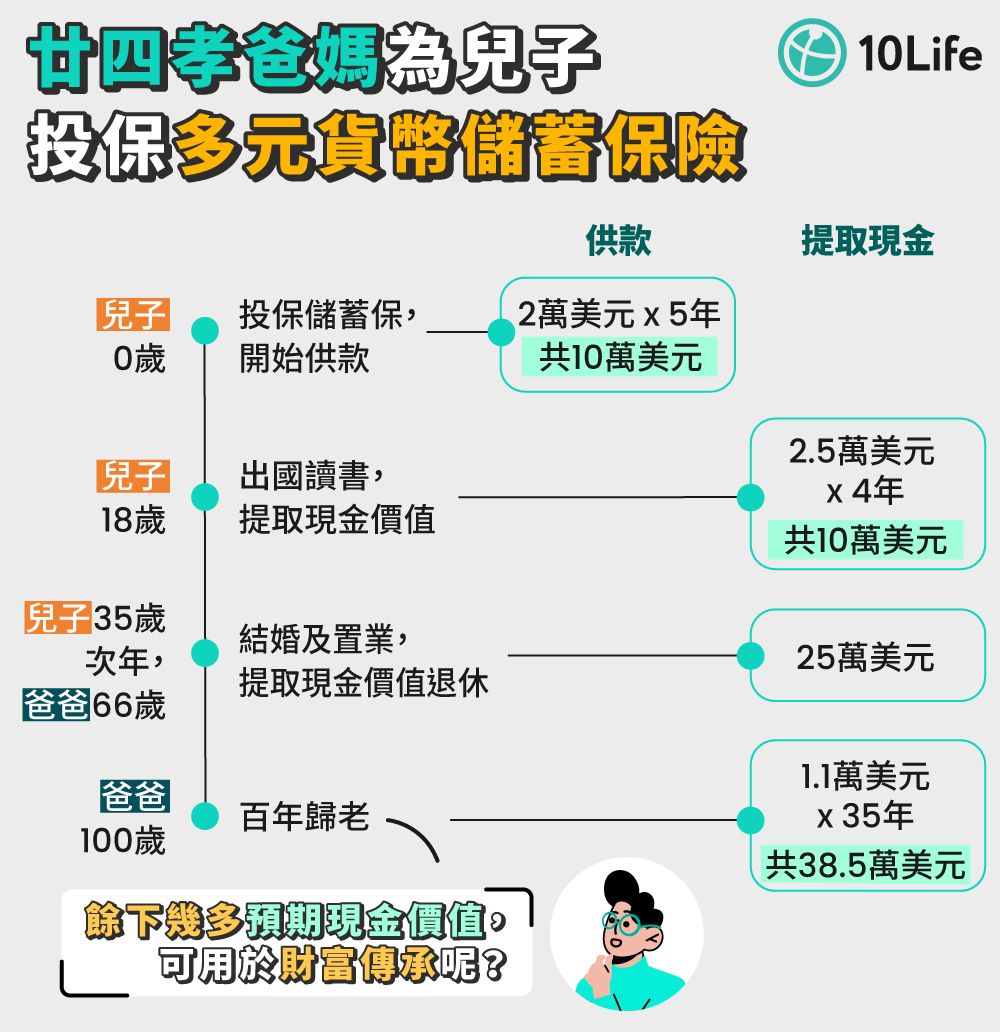
The above chart shows that a 30-year-old father, planning ahead, takes out a multi-currency savings insurance policy when his son is just born, to make arrangements for the future. He plans to pay premiums over 5 years, with a total sum insured of US$100,000 (approximately HK$780,000).
After key life stages: 1) his son studies overseas: withdrawing living expenses for 4 years (US$100,000 in total), 2) his son buys a home: withdrawing a lump sum for a property down payment (US$250,000), and 3) the father retires: withdrawing living expenses continuously for 35 years (US$385,000 in total), after the policy has been in force for 70 years, the father will have withdrawn a total of US$735,000 (approximately HK$5.733 million) from the plan. Compared with the total premiums paid at the time, this means the father has withdrawn more than seven times the amount from the policy. Until the father passes away at a ripe old age, how much expected cash value might the savings insurance still have left for wealth transfer?
(Assuming the policyholder takes out the policy at age 30, with a premium payment term of 5 years and total contributions of HK$100,000)
|
Policy term |
|||||
|
0-5 |
Contribute HK$100,000 (HK$20,000 x 5 years) |
||||
|
18-21 |
Withdrawals totalling HK$100,000 (HK$25,000 x 4 years) |
||||
|
35 |
Withdraw HK$250,000 (one-off) |
||||
|
36-70 |
Withdrawals totalling HK$385,000 (HK$11,000 x 35 years) |
||||
|
70 |
Remaining projected cash value |
||||
|
HK$704,690 |
HK$347,608 |
HK$305,487 |
Policy terminated3 |
HK$1,063,566 |
|
| Notes: 1. Insurance products are ranked according to the alphabetical order of the insurers’ English names 2. Remaining projected cash value includes guaranteed returns + non-guaranteed returns 3. Prudential Evergreen Wealth Multi-Currency Plan was terminated early during the policy year 36-70 period |
|||||
Multi-currency savings insurance products offer withdrawal options in different currencies, making it convenient to use foreign currency when children study overseas. The range of multi-currency savings insurance products compared this time, including AIA, FTLife, Manulife, Prudential and Sun Life, are among the more popular products in the market. The table above shows that, among the five products, four can correspond to the scenario of the “super dad and mum” (figure), namely the AIA, FTLife, Manulife and Sun Life products.
However, over a policy term of 70 years, the remaining projected cash value differs from product to product. Among them, the Sun Life product stands out the most, with a remaining projected cash value of more than US$1 million, while the remaining projected cash value of the AIA, FTLife and Manulife products ranges from about US$300,000 to US$700,000.
On the other hand, the Prudential product was unable to complete the “super dad and mum” scenario (figure), because the policy had already been terminated during the period when the father retired and withdrew US$11,000 a year for living expenses.
It is also worth reminding parents that the remaining expected surrender value listed above for the multi-currency savings insurance includes both “guaranteed returns” and “non-guaranteed returns”. The amount of the “guaranteed returns” is assured, but the “non-guaranteed returns” may not be fully realised. You may refer to the insurer’s dividend realisation rate for reference; bonus performance is affected by factors such as the insurer’s investment performance, bonus policy, number of claims, and operating expenses.
If customers have any questions, please feel free to contact 10Life for enquiries.
Notes:
1. Last updated on: 29 February 2024.
2. This article is compiled by 10Life from market information collected through various channels and is for general reference only. It has not taken into account any individual needs or suitability, and should not be regarded as sales advice. Before taking out insurance, you should discuss with a licensed insurance adviser to find a suitable insurance plan for you, and refer to the information provided by the insurer.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
1. The information of this article has been provided by the advertiser to promote its products and services.
2. The information of this article is intended for general education purpose and reference only. None of the information is intended, nor should they be considered or relied upon, as and is not, regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products.
3. 10Life Financial Limited will not be responsible for any liability, claim or loss arising from or associated with you using the information. No warranty, representation or guarantee is given by 10Life Financial Limited on the accuracy, completeness and timeliness of the information or for any claims and / or losses caused thereby.




 Talk to 10Life on WeChat
