









10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


Raising children is a significant responsibility. Beyond providing three meals a day and funding their education, parents also worry that when their children fall ill, they may face long waiting times for treatment at public hospitals, while private hospital treatment can be too expensive to afford. FWD has launched a Flexi VHIS plan – “Medical Plan” (abbreviated as “醫家保”). Whether you are new parents, expecting parents, or planning to have children, you can not only take out cover for yourself, but also add the “Children’s Home Protection Option”1 (optional benefit) for your child. The insured child can enjoy medical protection without any health underwriting. Even if the insured child has autism or attention deficit hyperactivity disorder (ADHD), they can still enjoy considerate medical protection without health underwriting# — truly “one medical plan, protecting two generations”.
If you want both yourself and your children to have their own medical cover, you may wish to refer to the following case.
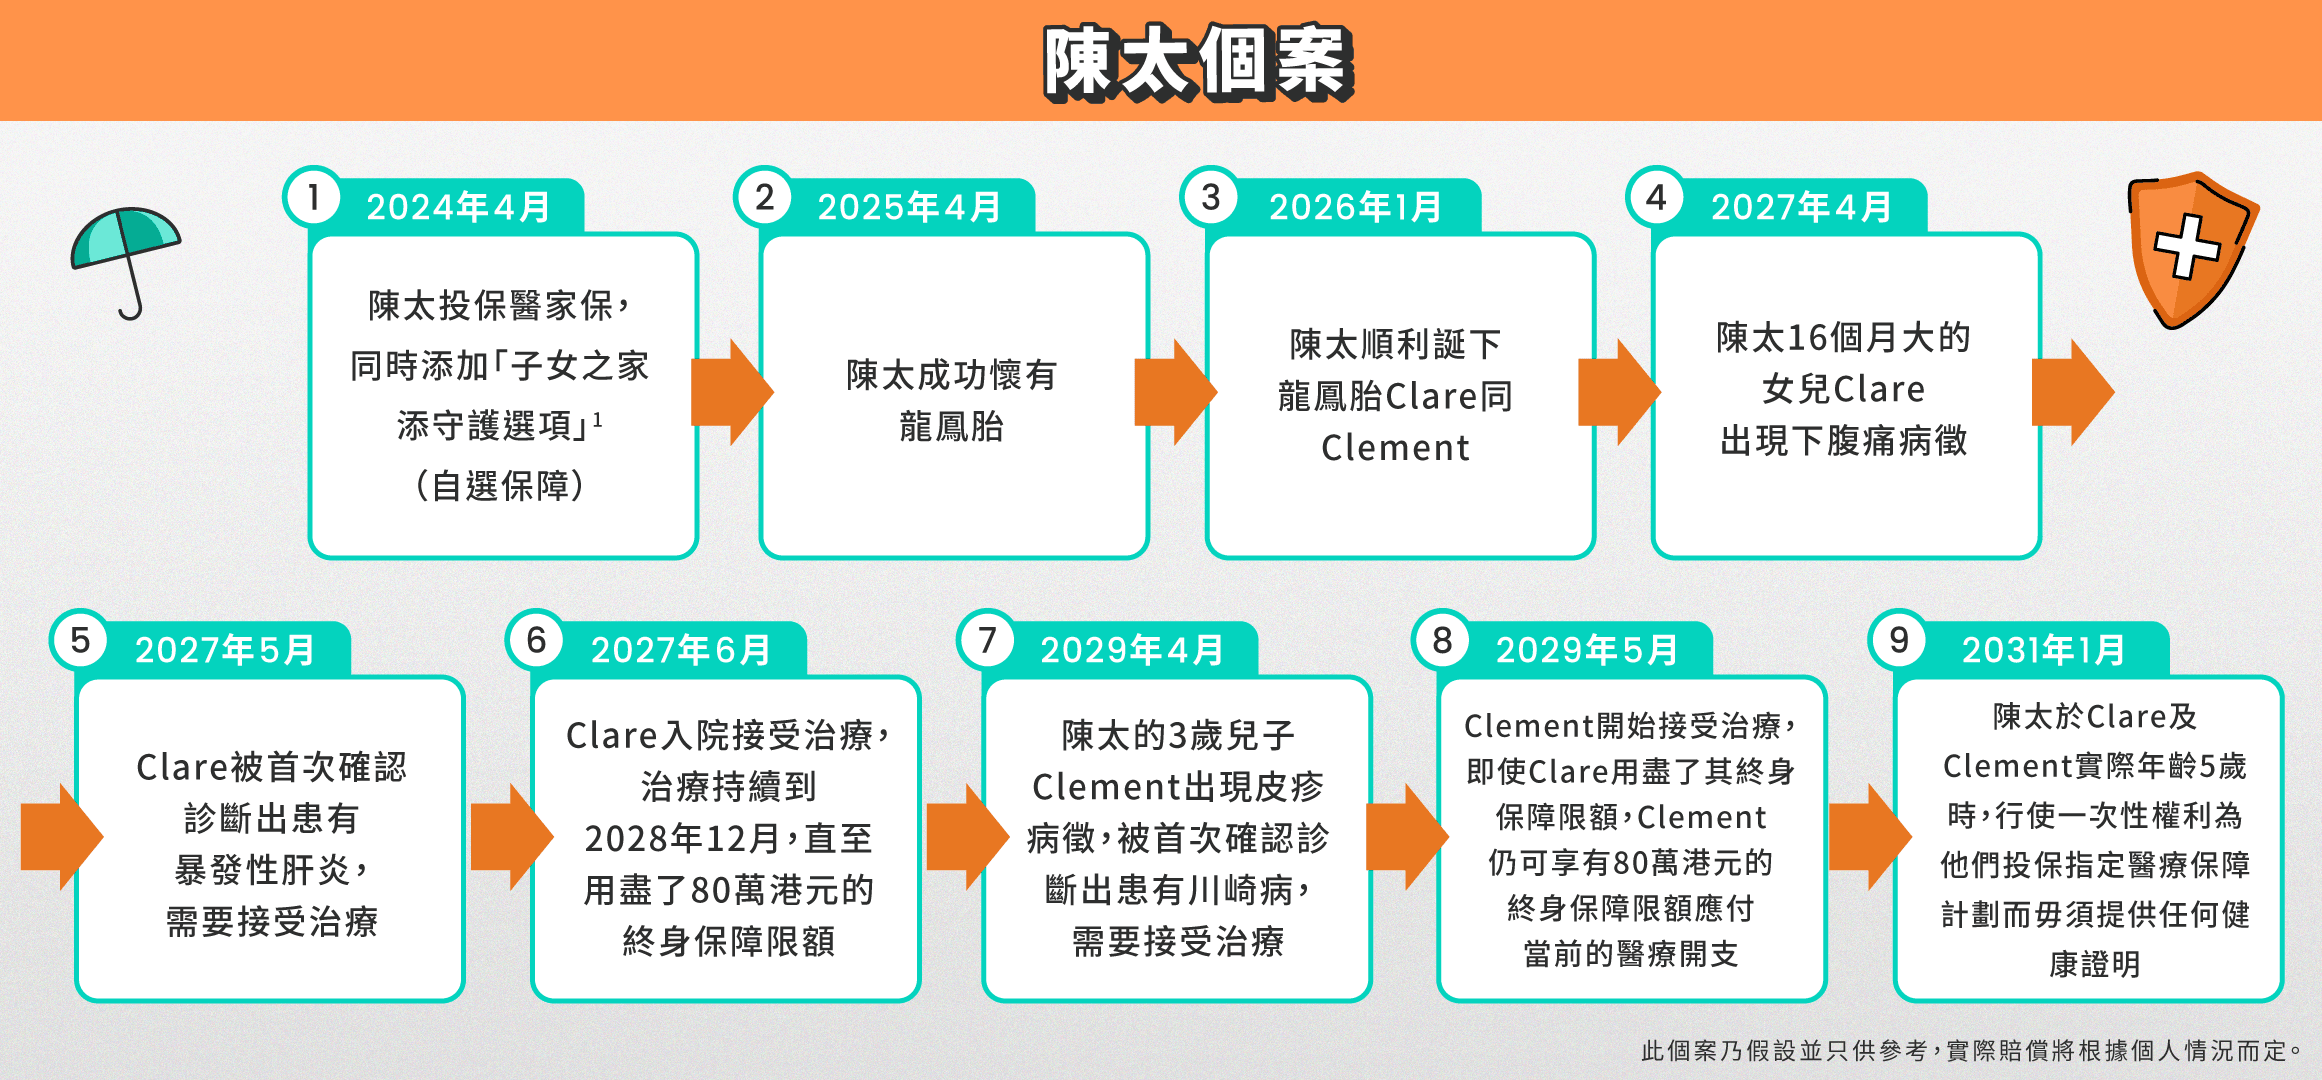
The Chan couple both love children. Since getting married, they have been planning to start a family, and they hope to prepare in advance and build a healthy future for themselves and their future children as early as possible. Mrs Chan therefore took out 醫家保 for herself in April this year (2024), while also choosing to add the “Children’s Home Protection Option”1 (an optional benefit) to protect herself and provide coverage for her future children. In April 2025, Mrs Chan successfully became pregnant with twins, and the medical benefits she enjoyed under 醫家保 as the insured person include:
As parents, our greatest concern is whether our children can grow up healthy and well. In recent reports, much attention has been paid to the difficulties SEN students face when applying for insurance. Once a child is diagnosed with autism or ADHD, they often encounter rejection when applying for medical insurance and are unable to obtain the medical protection they need. 醫家保 offers the “Child Support Option”1 (optional benefit), allowing parents to add this optional protection when applying for 醫家保, thereby protecting their children at the same time. Even if a child has already been diagnosed with autism or ADHD, the covered child can still be insured without undergoing any health underwriting#, though autism and ADHD are not among the specified covered illnesses. After the “Child Support Option”1 has been continuously in force for the specified policy years, the covered child can benefit from a thoughtful and innovative protection plan, the first of its kind in the market11.
The “Child Support Option”1 (optional benefit) provides the following three innovative layers of protection for the insured person’s children (until they reach the actual age of 19):
Another feature of the “Child Support Option”1 (optional benefit) is that there is no limit to the number of covered children. As Mrs Chan successfully conceived twins, both children each enjoy a lifetime benefit limit of HK$800,000, making this a strong back-up for children.
After ten months of pregnancy, Mrs Chan gave birth successfully in January 2026 to a pair of twins, Clare and Clement. The family of four began a new life, but unexpected events are often impossible to foresee.
When Clare was 16 months old, she developed lower abdominal pain, and by the time she was 17 months old, she was unfortunately diagnosed with fulminant hepatitis. She started treatment in June 2027, and the relevant eligible expenses could be reimbursed on a hospitalisation basis. The treatment continued until December 2028, when Clare’s lifetime benefit limit (HK$800,000) was exhausted.
Unfortunately, at the age of 3, her twin brother Clement developed a rash on major parts of his body and was then diagnosed with Kawasaki disease for the first time. He started treatment in May 2029. Even though Clare had already used up the lifetime benefit limit under the 「子女之家添守護選項」1 (optional benefit), Clement could still benefit from a lifetime benefit limit of HK$800,000 to cover the relevant eligible medical expenses.
Mrs Chan decided that in January 2031 (when Clare and Clement were both 5 years old), she would exercise the one-off right to enrol Clare and Clement in the designated medical protection plan without the need to provide any health proof+. Even though they had previously been diagnosed with fulminant hepatitis and Kawasaki disease respectively, this did not prevent them from continuing to enjoy medical protection.
Children’s health issues are often impossible to predict. Mrs Chan was fortunate to have purchased 醫家保 early on, and added the 「子女之家添守護選項」1 (optional benefit) for the twins, which enabled her to cope with the substantial expenses arising from their subsequent hospital treatment and ease the financial burden. Parents should therefore plan ahead and make proper medical protection arrangements for their children.
In addition, 醫家保 features a Health Reward, encouraging families to enrol together13 and embrace a healthy lifestyle. Personal and additional no-claim premium discounts can reach up to 30% in total (not applicable to the premium of the 「子女之家添守護選項」1 (optional benefit)).
By successfully applying for 醫家保 on or before 31 March 2025, you may enjoy a total premium discount of up to five months in the first and second policy years*; when successfully applying for 醫家保 on or before 31 March 2025, you may choose the “Child Care Plus Option”1 (optional benefit). The “Child Care Plus Option”1 may enjoy a total premium discount of up to 12 months in the first and second policy years^. Offers are subject to terms and conditions. Please refer to the relevant offer terms for details.
#This benefit is only applicable if the Child Care Plus Option has remained continuously in force for at least two policy years from the effective date of the Child Care Plus Option. If the insured child is unfortunately first diagnosed with any of the 62 specified critical illnesses and 13 specified childhood diseases covered under the Child Care Plus Option (the “Specified Illnesses”), relevant eligible expenses and/or charges incurred will be reimbursed (for Specified Illnesses only), excluding any discomfort, illness or injury other than the Specified Illnesses. For the avoidance of doubt, autism and ADHD are not covered Specified Illnesses. Under Section 6(A) of the terms and conditions of the Child Care Plus Option attached to the policy terms of 醫家保, FWD will not reimburse any medical services expenses incurred for any Specified Illness diagnosed or treated during or before the child protection waiting period. This exclusion does not apply to expenses arising from an accident and from Specified Illnesses diagnosed or treated during the child protection waiting period. The relevant terms and conditions, including but not limited to FWD’s prevailing rules and regulations at the time of application, shall be determined by FWD at its sole discretion from time to time. For details, please refer to the terms and conditions of the Child Care Plus Option attached to the policy terms of 醫家保.
+This option is only applicable if the Child Care Plus Option has remained continuously in force for at least two policy years from the effective date of the Child Care Plus Option. On the day the insured child reaches the age of 5, 10, 15 or 18, or within 31 days before the immediately following renewal date, the policyholder may exercise a one-off right to take out one designated medical protection plan for each insured child without providing the insured child’s health proof. For the avoidance of doubt, under the designated medical protection plan taken out after exercising the one-off right, FWD will not pay for any discomfort, illness or injury occurring during or before the child protection waiting period. The relevant terms and conditions, including but not limited to FWD’s prevailing rules and regulations at the time of application, shall be determined by FWD at its sole discretion from time to time. For details, please refer to the product brochure and policy terms.
*If you take out the 醫家保 medical plan without adding the “Child Care Plus Option” (optional benefit), you may enjoy a two-month premium discount in the first policy year; if you take out the 醫家保 medical plan together with the “Child Care Plus Option” (optional benefit), you may enjoy a two-month premium discount in the first and second policy years respectively. Together with the bundled application premium discount (simultaneously applying for two or more specified FWD VHIS plans for yourself and/or specified relatives), all eligible policies may each have the opportunity to enjoy an additional one-month premium discount in the first policy year (not applicable to the premium of the “Child Care Plus Option” (optional benefit)). Offers are subject to terms and conditions. Please refer to the relevant offer terms for details.
^When applying for the 醫家保 medical plan, you may choose the “Child Care Plus Option” (optional benefit). The “Child Care Plus Option” may enjoy a premium discount of six months in the first and second policy years respectively. Offers are subject to terms and conditions. Please refer to the relevant offer terms for details.
The above product information does not include the full policy terms and is subject to the terms and conditions of the relevant plan. For details of the above product features, benefits, full terms, exclusions and key product risks, please refer to the FWD website, the relevant product brochure and policy terms.
Remarks:
醫家保 medical plan (Voluntary Health Insurance Accredited Product Code: F00072) is underwritten by FWD Life Insurance Company (Bermuda) Limited (a company incorporated in Bermuda with limited liability) (Voluntary Health Insurance Scheme Provider Registration No.: 00036).
The above information is sponsored and provided by FWD Life Insurance Company (Bermuda) Limited and is for reference only.
The content is intended for use in Hong Kong only and shall not be construed as an offer to sell, a solicitation to buy, or the provision of FWD Life insurance products outside Hong Kong. The sales and application procedures for the products must be carried out and completed within Hong Kong. Before applying, please ensure that you understand the relevant product features and that they meet your needs.
FWD Life Insurance Company (Bermuda) Limited, its principals and affiliated companies, or their respective directors or employees, make no express or implied representation, statement or warranty as to the accuracy, completeness or suitability of the information for any particular purpose, nor accept any liability. FWD Life Insurance Company (Bermuda) Limited, its principals and affiliated companies, or their respective directors or employees shall not be liable and shall not bear legal responsibility (including third-party liability) for any consequences arising from the use of or reliance on this article.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Bringing you the latest market information
1. The information of this article has been provided by the advertiser to promote its products and services.
2. The information of this article is intended for general education purpose and reference only. None of the information is intended, nor should they be considered or relied upon, as and is not, regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products.
3. 10Life Financial Limited will not be responsible for any liability, claim or loss arising from or associated with you using the information. No warranty, representation or guarantee is given by 10Life Financial Limited on the accuracy, completeness and timeliness of the information or for any claims and / or losses caused thereby.




 Talk to 10Life on WeChat
