









10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


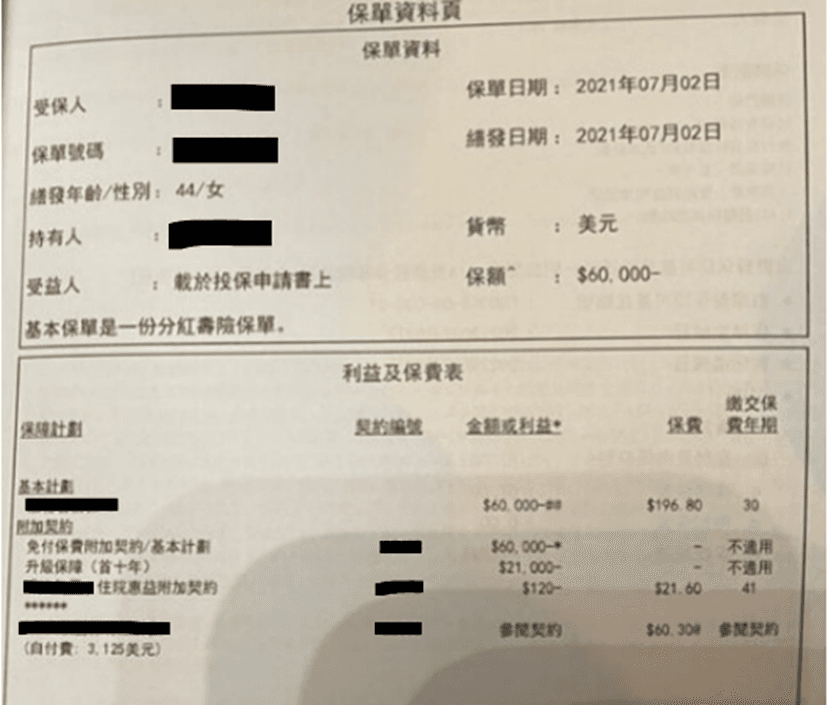
Two years ago, when Ms Chan (a pseudonym) was 44, she purchased a critical illness insurance policy with a sum insured of US$60,000 (approximately HK$468,000) to provide a safety net. Earlier this year, Ms Chan underwent an examination after a persistent cough failed to improve. Two weeks later, Ms Chan was confirmed to have stage 4 lung adenocarcinoma. Although the road to cancer treatment would not be easy, her family still hoped that the critical illness insurance she had bought earlier could help cover her medical expenses.
Miss Chan immediately started treatment and soon spent several hundred thousand Hong Kong dollars. At the beginning of February this year, Miss Chan filed a claim with the insurance company; however, the process was not smooth. At the end of March, the insurance company replied that, as the claimant’s documents were incomplete, it was unable to process the claim. After the claimant submitted the supplementary information, she enquired again with the insurance company in early May. The response was that the insurance company needed to obtain the claimant’s medical records from the Hospital Authority, and was still waiting for the Hospital Authority to approve the release of the documents, so it could not confirm when the claim would be paid. Miss Chan could only wait indefinitely.
To make matters worse, the doctor informed Miss Chan and her family that stage 4 cancer was already a very critical condition, and they should prepare for the worst. Miss Chan may only have a few months to live, and is currently only able to receive targeted therapy. However, targeted drugs can cost well over ten thousand dollars each time. In order to treat her illness, Miss Chan’s family has already spent several hundred thousand dollars, including debts owed to relatives and friends.
Not only does Miss Chan have to battle the illness, she also has to deal with the difficult claims process. The heavy financial burden has intensified her psychological stress. After pursuing the insurance claim for three months, Miss Chan felt mentally and physically exhausted, and sought assistance from a 10Life claims specialist. The 10Life claims specialist negotiated with the insurer’s internal staff, and within two weeks successfully secured the full claim amount of USD 60,000 for Miss Chan. It is understood that when the insurer made the payment, it had not yet obtained the medical records from the Hospital Authority, but given Miss Chan’s urgent situation, it exercised discretion to expedite the claim.
10Life conducted an analysis and assessment of Ms Chan’s case and considered that the reason for the delayed claim was an “Early Claim”. An “Early Claim” refers to a claim made within two years after the policy is taken out. In this case, Ms Chan submitted her claim about one and a half years after purchasing the policy, which falls under an “Early Claim”.
For cases involving an “Early Claim”, the insurer has reason to suspect that the insured may have taken out insurance while already ill, and will therefore investigate the claimant’s prior medical condition particularly thoroughly and cautiously. It will query the Hospital Authority’s medical records to verify whether the claimant had any lung-related medical consultations before taking out the policy. As a result, claims for “Early Claim” cases can take as long as 8 to 12 weeks. If the insurer discovers any undisclosed medical history or health conditions, it has the right to cancel the policy, also known as “kicking out the policy”, and refuse compensation.
10Life would like to remind everyone that although insurers have the right to investigate claims, they must not deliberately delay settlement. If the claims process takes an excessively long time, or if a claim is unfairly rejected, policyholders should also stand their ground. In this process, a competent insurance adviser can play an important role by helping clients negotiate with the insurer and, where necessary, lodging a complaint with the Insurance Complaints Bureau.
Finally, if readers have any questions about policy claims, please feel free to contact 10Life. 10Life’s claims specialists focus on securing fair compensation for clients and reviewing whether the insurer’s compensation amount is sufficient. If the insurer refuses to pay or the compensation is insufficient, the claims specialists will assist clients in pursuing the matter with the insurer.
Email: enquiries@10life.com
Further reading
〈【Vegetative State Claim Dispute】Which insurers have this exclusion clause?〉
〈【CEO’s View】The fallacy of “full reimbursement” medical insurance〉
Note: The claims specialists of 10Life Financial are licensed insurance intermediaries authorised by the Hong Kong Insurance Authority.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance




 Talk to 10Life on WeChat
