









10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


Many parents of the new generation do not want to become a burden to their children in old age, so they plan their retirement life early. Some therefore look to more stable long-term wealth management tools in the market, hoping to secure steady returns after retirement to meet various living expenses, while also easing the future pressure on their children to support their parents. In addition, they can pass on their wealth to the next generation after they have passed away.
Many people choose long-term savings insurance products with a guaranteed element in the market, hoping that by compounding over a long period, their wealth can grow steadily. This not only helps cover the various needs of retirement life, but also prepares for wealth inheritance. 10Life has compiled five of the more popular multi-currency savings insurance products currently available in the market to compare how effective they are as retirement planning tools.
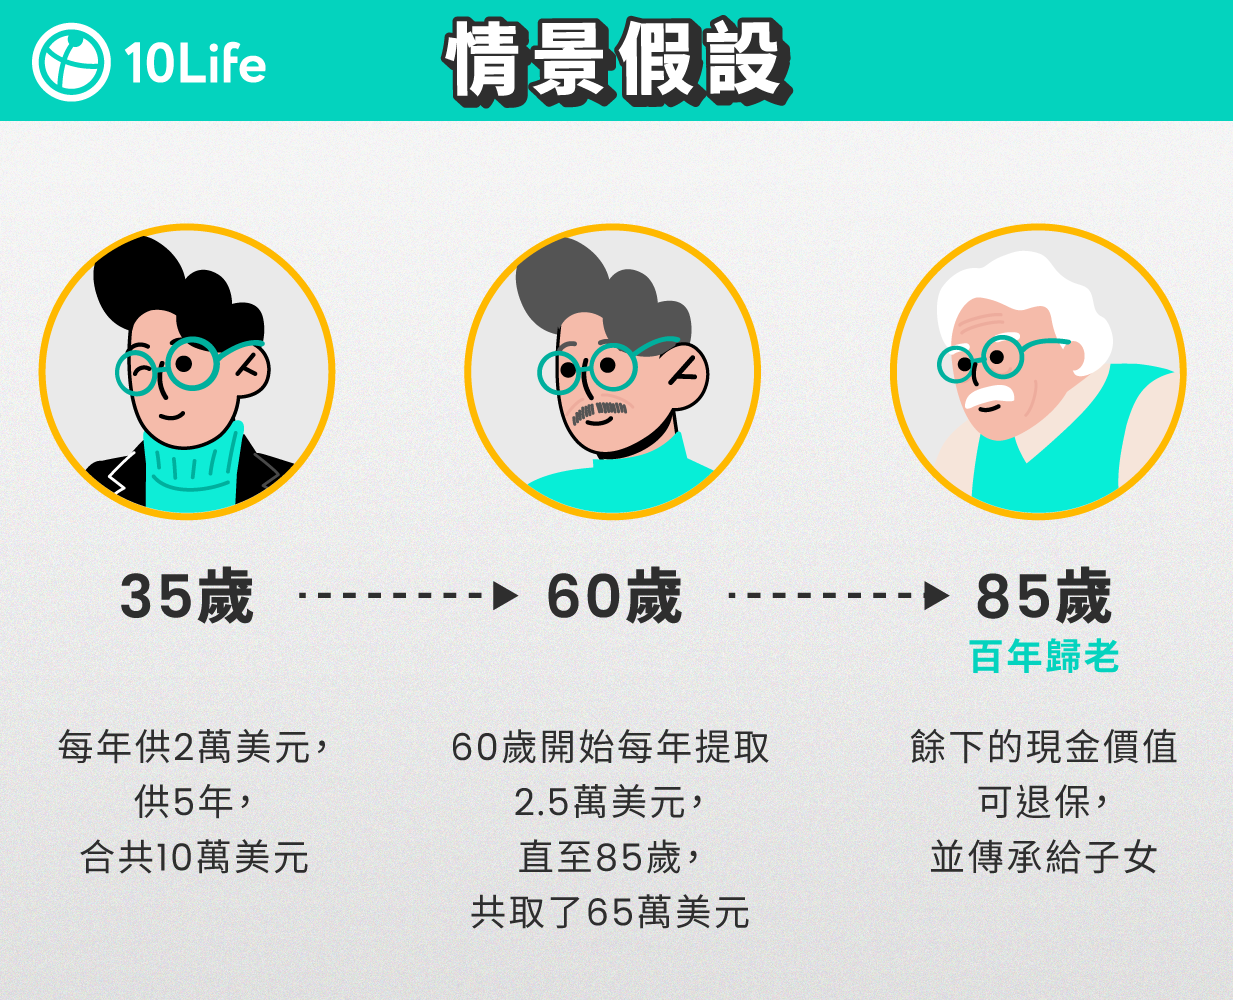
Middle-income individuals often want to maintain their usual standard of living after retirement, or even enjoy life to the full in their later years, so planning for retirement early becomes important. Suppose a middle-income father aged 35 makes financial arrangements for his future retirement life by taking out a savings insurance policy, paying USD20,000 a year for a premium payment term of 5 years, with total contributions amounting to USD100,000.
After retiring at 60, he plans to start withdrawing the cash value, aiming to take out USD25,000 each year as long-term income until he passes away at 85. He therefore needs to make annual withdrawals for 26 consecutive years, totalling USD650,000. If the policy performs well, he would also hope to have money left over to pass on his wealth to his children. Which products on the market can help policyholders plan ahead as early as possible?
Based on the example of the middle-class father above, various savings insurance products available in the market can be considered. The products compared this time include a range of multi-currency savings insurance plans, namely FWD, Sun Life, AIA, Prudential and Manulife, all of which provide both guaranteed and non-guaranteed returns.
Ideally, all of these products could meet the retirement goal of the middle-class father in the case. Between the ages of 60 and 85, he could receive US$25,000 a year, effectively creating his own monthly retirement income to cover day-to-day living expenses, and even travel from time to time to enjoy the second half of life.
However, the above scenario is calculated based on the insurers’ current assumed projected returns. If the policy returns perform below expectations (i.e. the dividend realisation rates in some policy years are far below 100%), the policyholder may only be able to withdraw less than US$25,000 a year, or may even be unable to make any withdrawals from the remaining policy value. (Please refer to Table 1 for the guaranteed and non-guaranteed portions of the different products.)
Under the pessimistic scenario1, the policyholder is even more likely to insist on withdrawing US$25,000 a year, which could force the policy to terminate early.
| Product | Expected amount to be withdrawn from policy value (USD)* | Expected proportion of the total amount withdrawn from the guaranteed portion | |
| Guaranteed portion* | Non-guaranteed portion* | ||
| AIA友邦 「盈御多元貨幣計劃3」 | $85,540 | $564,460 | 13.2% |
| FWD 富衛 「盈聚‧天下壽險計劃」 | $76,997 | $573,003 | 11.8% |
| Manulife宏利 「宏摯傳承保障計劃」 | $99,862 | $550,138 | 15.4% |
| Prudential保誠 「雋富多元貨幣計劃」 | $93,278 | $556,722 | 14.4% |
| Sun Life永明 「萬年青•星河尊享計劃」 | $88,276 | $561,724 | 13.6% |
| *Based on the above cases, if the policyholder withdraws USD 25,000 per year, the withdrawal amount will first be taken from the policy’s annual and/or reversionary bonuses (if any). After the value of these bonuses has been exhausted, the policyholder will need to partially surrender the policy to withdraw the remaining amount. Therefore, if the bonus realisation rate for that policy year is lower than expected, the cash value available for withdrawal will be less than expected, and the policyholder will need to surrender a larger notional amount. Note: 1. Based on product brochures and quotations available in the market as printed in April 2024, the above figures may change from time to time. 2. The amounts shown in the table are calculated based on the insurers’ current assumptions (base scenario) returns. 3. Products are listed in alphabetical order by the insurers’ English names. | |||
(Assuming the policyholder takes out a policy at age 35, pays US$20,000 a year for a premium payment period of 5 years, with total contributions of US$100,000, and withdraws US$25,000 a year between ages 60 and 85)
| Product | Projected remaining policy cash value (US$) | Ratio of projected remaining total cash value to premiums paid | Projected internal rate of return | |
| Guaranteed portion* | Total cash value | |||
| AIA友邦 「盈御多元貨幣計劃3」 | $20,766 | $321,984 | 322% | 6.23% |
| FWD富衛 「盈聚‧天下壽險計劃」 | $35,817 | $605,582 | 606% | 6.64% |
| Manulife宏利 「宏摯傳承保障計劃」 | $20,971 | $343,343 | 343% | 6.27% |
| Prudential保誠 「雋富多元貨幣計劃」 | $20,483 | $358,091 | 358% | 6.29% |
| Sun Life永明 「萬年青•星河尊享計劃」 | $21,172 | $323,402 | 323% | 6.23% |
| *The “guaranteed portion of the projected remaining policy cash value at age 85” is calculated based on the projected amount at the end of the previous policy year. Over the 26 policy years of the self-assembled retirement income plan, the actual principal amount after each partial surrender may be higher or lower than the illustrative figures for each policy year; accordingly, the subsequent actual “guaranteed portion” will also be adjusted correspondingly. Notes: 1. Comparison based on product brochures and proposals (base scenario) printed as at April 2024 in the market; the above figures may change from time to time. 2. Ranked in alphabetical order by the insurer’s English name. | ||||
In the ideal scenario corresponding to the table above, assuming the middle-class father deploys wealth succession at the age of 85 after withdrawing cash for 26 years, the five products would still have an expected remaining cash value of between approximately US$320,000 and US$600,000.
Although the expected internal rate of return (IRR) of all five products exceeds 6%, the difference becomes more apparent when comparing the ratio of each product’s expected total cash value to premiums paid, due to the compounding effect of interest. Among them, FWD’s savings product ranks highest, with a ratio of more than six times.
It is worth noting that policyholders should be aware that all five products above have already withdrawn most of their guaranteed cash value during the policyholder’s income period from age 60 to 85. Therefore, as shown in Table 2, the “guaranteed portion” of the total remaining cash value in the policy accounts for only a small share, at around US$20,000 to US$35,000. The expected total cash value will depend largely on the insurer’s investment performance and the realisation of bonuses.
In fact, whether it is the amount of self-generated income (from age 60 to 85) or wealth succession (at age 85), both include guaranteed and non-guaranteed returns. The guaranteed and non-guaranteed value to be withdrawn in the future will be affected by the bonus realisation at the time of each cash withdrawal, and the above returns may not necessarily be realised.
| Product | Currency conversion option (available currencies) | Death benefit payment options | Policy split | ||
| Lump sum | Instalments | Combined payment of 2 forms | |||
| AIA友邦 「盈御多元貨幣計劃3」 | 9 | ✔ | Fixed amount | ✘ | From the end of the 3rd policy year |
| FWD富衛 「盈聚‧天下壽險計劃」 | 8 | ✔ | Fixed amount/increasing | ✔ | From the 3rd policy anniversary |
| Manulife宏利 「宏摯傳承保障計劃」 | 7 | ✔ | Fixed amount/increasing | ✔ | From the 5th policy anniversary |
| Prudential保誠 「雋富多元貨幣計劃」 | 6 | ✔ | Fixed amount | ✔ | From the 5th policy anniversary |
| Sun Life永明 「萬年青•星河尊享計劃」 | 4 | ✔ | Fixed amount/increasing | ✔ | From the 3rd policy anniversary |
| Note: 1. Listed in alphabetical order by insurer English name. | |||||
Policyholders can not only pay attention to the returns of savings insurance, but also compare the features of different products. The above five savings insurance products are all available in different currencies for selection or conversion, ranging from 4 to 9 currencies, helping to meet policyholders’ needs at different life stages, such as planning to live overseas after retirement or returning to the Mainland to live.
To facilitate policyholders in using savings insurance as a wealth transfer tool, all five products above offer an insured change option, as well as policy splitting and a range of death benefit payment options. The products mentioned above can all pay death benefits as a lump sum. If instalment payments are preferred, note that some products not only allow fixed-amount payments, but also offer an escalating payment option. In addition, the products from FWD, AIA and Sun Life allow policy splitting as early as the 3rd policy anniversary, making it easier for policyholders to allocate assets flexibly.
Notes:
1. Insurance companies use the 25th percentile of projected investment returns as an estimate for policyholders’ reference.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com




 Talk to 10Life on WeChat
