






10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong



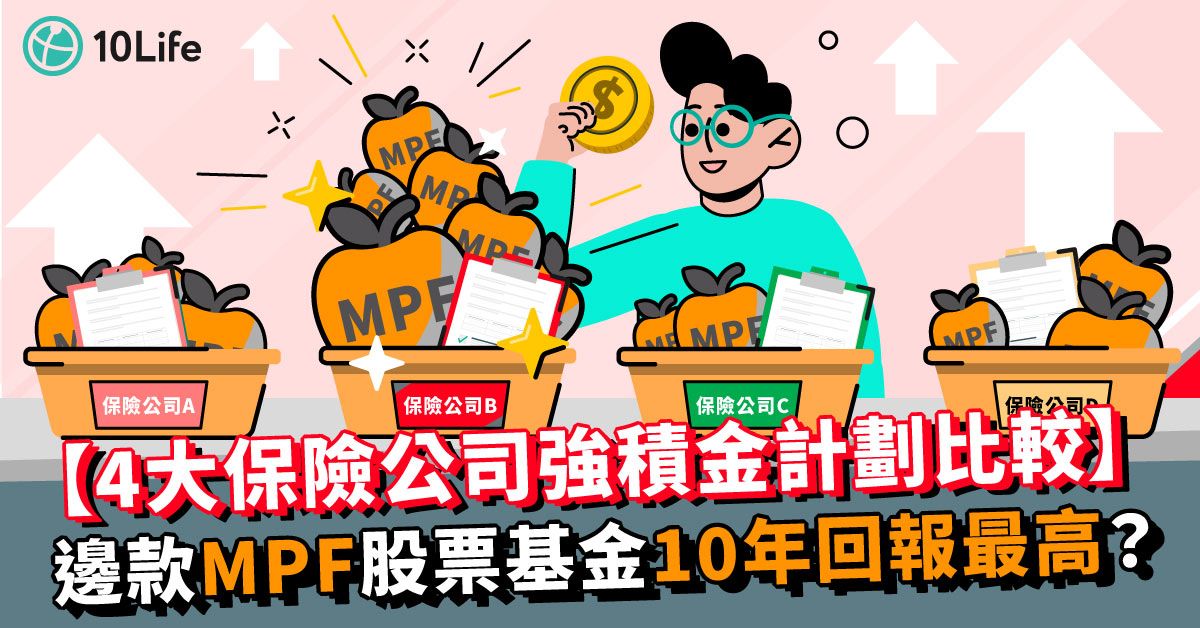
There are different types of funds within the Mandatory Provident Fund (MPF) scheme (see Table 1). Among them, equity funds have the highest long-term growth potential and are the main engine for asset appreciation, making them suitable for those with a longer investment horizon and a higher tolerance for investment risk. But which type of equity fund offers the highest returns? 10Life examined the MPF schemes of the four major insurers with the largest total fund size and found that one category of equity fund delivered returns of over 115% over the past 10 years in all four schemes.
Table 1: Compare the 5 main MPF funds
| Type | Risk Level | Suitable for |
| Conservative Fund | Lower | Conservative people, those who do not like taking risks, or those approaching retirement |
| Guaranteed Fund | Lower | People who do not like taking risks, want guaranteed commitments, or are about to retire |
| Bond Fund | Low to medium | Moderately conservative, more mature in age, and those seeking steady gains |
| Mixed Assets Fund | Medium to high depending on the equity-bond ratio | Prudent or aggressive people |
| Equity Fund | Higher | People with a longer investment horizon and a higher risk tolerance |
| Reference: MPFA | ||
AIA, BOC Life, Prudential and Manulife offer at least 7 stock fund options
Equity funds are often classified according to the markets in which they invest, such as US equity funds (single-country equity funds) and European equity funds (regional equity funds). The more types of funds offered by an MPF scheme, the better it can meet the investment needs of scheme members and help diversify portfolio risk.
The types of equity funds offered vary from one MPF scheme to another. Among the MPF schemes offered by the four major insurers, AIA, BOC Prudential and Manulife each offer at least seven equity fund options, while Sun Life offers only five (see Table 2). It is worth noting that, among the four schemes, only BOC Prudential and Manulife offer Japanese equity funds.
One point to note is that, although they are all equity funds, their risk levels vary. In general, funds that invest heavily in a single market, such as US equity funds, carry higher risk than funds that invest across different markets, such as global equity funds. For the risk level of equity funds, readers may refer to the “risk indicator” in the fund fact sheet.
In addition, readers should also pay attention to the regions in which different equity categories invest, rather than relying solely on the fund name to make a judgement. For example, China equity funds invest in Chinese equities listed in Hong Kong, while Greater China equity funds invest in the stock markets of Mainland China, Hong Kong and Taiwan, among others.
US equity fund returns over the past 10 years have exceeded 115%
The returns of equity funds are related to the regions in which they invest. Table 2 shows the returns of different categories of equity funds over the past 10 years, covering Hong Kong, Greater China, Asia, global markets and more. US equities have performed well over the past 10 years, which has also benefited the relevant funds. As shown in Table 2, US equity funds outperformed other regional categories. Among them, the 10-year returns of AIA, BOC-Prudential and Manulife-related funds all reached at least 115%, while BOC-Prudential’s North America Index Tracking Fund returned as much as 161.8%.
Different insurance companies perform differently across various equity fund categories. Readers should compare carefully before investing and refer to the fund fact sheets for a detailed understanding of the funds’ features, objectives, risk levels, fees and charges, etc.
Table 2: Compare the 10-year returns of equity funds under flagship MPF schemes of four major insurers (as at end-2022)
| Equity Fund Category |
友邦 強積金優選計劃 |
中銀保誠 簡易強積金計劃 |
宏利 環球精選(強積金)計劃 |
永明 彩虹強積金計劃 |
| United States | North American Equity Fund 151.91% Americas Fund 119.33% |
North America Index Tracking Fund 161.8% |
North American Equity Fund 117.1% |
Not provided |
| Unclassified | Asia-Europe Fund 28.17% |
Not provided | Healthcare Fund 131.1% |
Not provided |
| Global | Global Fund 75.96% Green Retirement Fund 106.58% |
Global Equity Fund 90.78% |
International Equity Fund 77.91% |
Industry Equity Fund 62.20% (Class A) 65.49% (Class B) |
| Japan | Not provided | Japan Equity Fund 35.88% |
Japan Equity Fund 97.4% |
Not provided |
| Europe | Europe Equity Fund 54.79% |
Europe Index Tracking Fund 61.6% |
Europe Equity Fund 59.94% |
Not provided |
| Hong Kong | China and Hong Kong Fund 4.08% |
Hong Kong Equity Fund 8.33% |
Hong Kong Equity Fund 14.36% |
Hong Kong Equity Fund 43.09% (Class A) 45.98% (Class B) |
| Asia | Asia Equity Fund 39.36% |
Asia Equity Fund 18.98% |
Asia Pacific Equity Fund 42.99% |
Asia Equity Fund 37.45% (Class A) 40.22% (Class B) |
| Greater China | Greater China Equity Fund 41.18% |
Not provided | China Power Fund 15.53% |
China Equity Fund 26.59% (Class A) 29.15% (Class B) |
| Hong Kong (Index Tracking) |
Not provided | CSI Hong Kong 100 Index Fund 0.55% |
Hang Seng Index Fund 9.88% |
Not applicable (less than 10 years since inception) |
| China | Not provided | China Equity Fund -1.06% |
Not provided | Not provided |
| Note: 1. Data source: Quarterly fund fact sheets of major insurers for Q4 2022. 2. Equity fund categories are based on MPFA classifications. 3. Ranked according to the highest fund return within each equity fund category. |
||||
Another point worth noting is that the level of fund charges has a significant impact on the long-term net returns of MPF schemes, and passive investment strategies (such as index funds) usually have lower charges than active investment strategies. Taking Europe equity funds as an example, AIA and Manulife’s Europe equity funds charge 1.67% and 1.77% respectively, while BOC Prudential’s Europe index tracking fund charges 1.05%.
Same-venue bonus: Default investment strategy
The MPF legislation stipulates that all MPF schemes must offer a “Default Investment Strategy” (DIS) option. The Default Investment Strategy has a fee cap of 0.95% and adopts a diversified investment approach, with fund assets allocated across global equity and bond markets. It also automatically reduces investment risk as scheme members approach retirement age. It is suitable for salaried employees who do not have time to manage their MPF or are unfamiliar with investment knowledge, and is therefore commonly known as the “lazy fund”.
This article provides only a rough comparison of the returns of equity funds under different schemes. Past performance is not indicative of future returns. Readers should not rely solely on this document to make any investment decisions. Before making any investment decision or switching funds, you should consider your personal risk tolerance and financial situation, as well as understand the features and investment risks of the relevant funds. If you have any questions about choosing funds, you should seek advice from a financial and/or professional adviser.
Note: Updated to 4 April 2023.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com


 Talk to 10Life on WeChat
