









10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


In 2021, Ms S (a pseudonym) had just sold her owner-occupied property and planned to move house a year later. She went to the bank to enquire about a mortgage and intended to place the funds in a fixed deposit first, withdrawing them a year later to pay the deposit. However, the bank staff said that a savings insurance policy would deliver better returns: by making a one-off payment of more than HK$280,000, followed by monthly premiums of around HK$3,000, she could receive more than HK$800,000 after 10 years. After strong persuasion from the bank staff, Ms S eventually took out a savings insurance policy.
At the end of 2023, Ms S received a debt collection letter from the bank, demanding repayment of the principal and interest of more than HK$720,000. She found this very strange at the time and did not understand when she had borrowed the money. She then called the bank’s credit department and learned that, without her knowledge, she had applied for a loan of more than HK$720,000 from the bank in 2021 through a “premium financing” arrangement. The loan arrangement had now been cancelled, and she was required to repay the full loan amount and interest immediately. It was only then that she realised the monthly payments she had thought were for insurance premiums were actually just interest repayments. She tried visiting a bank branch to find out how she could delay repayment. A bank staff member first suggested that she surrender the policy and use its cash value to repay the HK$720,000 loan, but the initial HK$280,000 in contributions would then be lost; later, the bank staff member said that if Ms S deposited assets worth HK$1 million with the bank, the loan might be reinstated. Unsure what to do, Ms S sought help from 10Life.
For ordinary bank loans, as long as borrowers regularly repay the interest, banks very seldom suddenly “call the loan” and require borrowers to repay the loan early, which would make it difficult for borrowers to plan their finances. However, in the case of mortgage loans, when a property falls into negative equity, the bank handling the mortgage may, to protect its own interests, also “take down the umbrella when it rains” and “call the loan” early. But with premium financing, the loan amount is usually not higher than the policy’s guaranteed cash value. If the borrower does not pay the interest, since the policy has already been pledged to the bank, the bank has the right to cancel the policy and offset the debt with the policy’s guaranteed cash value. Therefore, the bank bears very low lending risk in premium financing, and so sales consultants generally do not mention the possibility of a “call loan”.
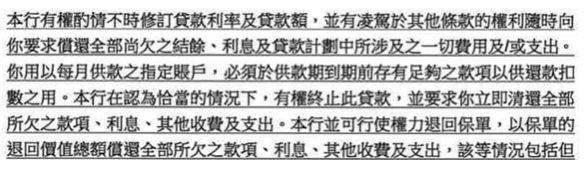
It is indeed hard to understand why Miss S, who had been paying interest all along (although she thought she was paying for her insurance), was suddenly “called” by the bank. However, when 10Life looked more closely into the bank’s loan terms, it found that the bank has the right to “call the loan” at any time, as set out in the following terms:
According to the statement and documents provided by Ms S, the 10Life team found that bank branch staff displayed many unfair practices during the sales process, and were suspected of concealing and deceiving Ms S into taking out high-risk premium financing.
Based on the multiple doubts and procedural errors mentioned above, 10Life, on behalf of Miss S, argued the case forcefully with the bank. After repeated negotiations, the bank not only stopped the “call loan”, but also refunded the insurance premium financing-related premiums and interest to Miss S, compensating her with more than HK$300,000.
Afterwards, Miss S sent a fruit basket to 10Life, together with a thank-you card to express her gratitude.
In the market, it is not only the sales practices of premium financing products that have issues; many other insurance products may also have plenty of hidden pitfalls. The above case is likely only the tip of the iceberg. If you have also encountered poor insurance sales practices, or are facing great difficulty when making a claim, please contact 10Life via WhatsApp at 37051599. Upholding its mission to “make fair insurance a reality”, 10Life will do its utmost to fight for insurance victims.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com




 Talk to 10Life on WeChat
