





10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong



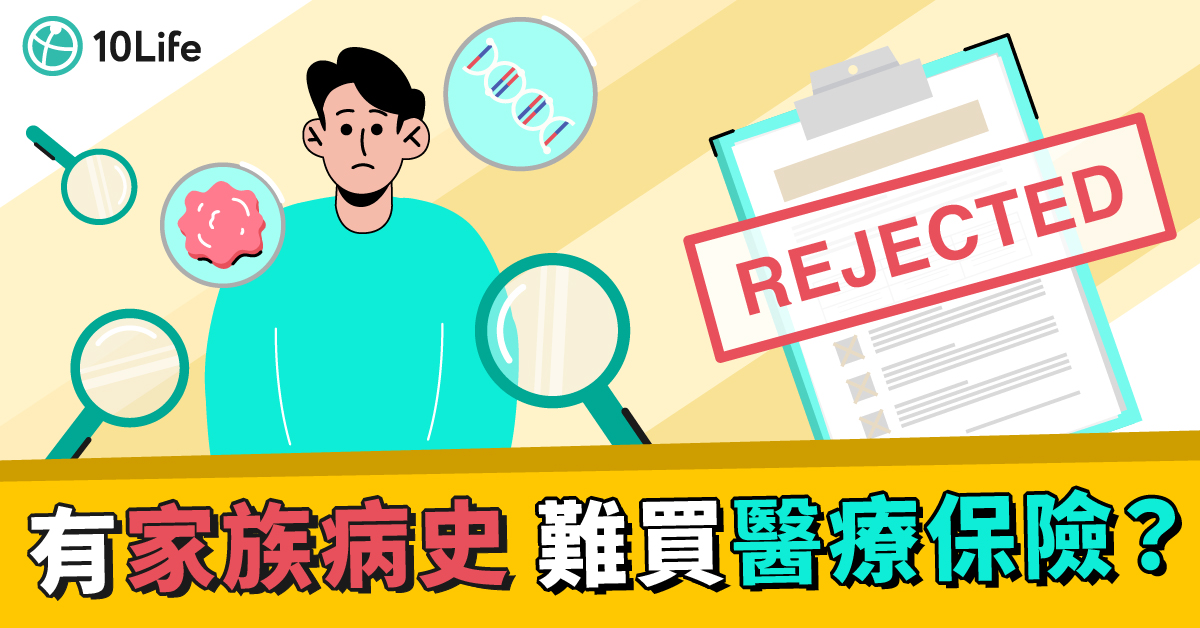
Family medical history may affect the health of the next generation. When buying medical insurance, insurers will ask about the health history of family members. If it is found that a family member has had cancer, diabetes, a hereditary disease and so on, in the worst-case scenario the policyholder may even be denied a claim. But do different insurers in fact have different underwriting standards?
Hereditary diseases are not limited to congenital conditions present from birth. Many studies have already shown that major illnesses such as cardiovascular disease, diabetes and various types of cancer are all related to genetics. Looking at many insurers’ application forms, including those of major insurers such as AIA, Manulife and Prudential, most state that applicants must declare the health history of family members.
One insurer’s medical insurance application form requires the applicant to disclose whether their “parents, brothers or sisters have ever suffered from:
as well as other hereditary diseases including:
Under the principle of utmost good faith, applicants must truthfully declare these “material facts”, including the relationship between the prospective insured and the family member, the name of the illness, the current health condition, and the age at which the disease first appeared. If these are not disclosed truthfully, serious problems may arise when making a claim in future. For example, the insurer may refuse to pay out or even cancel the contract on the grounds of “non-disclosure of material facts”.
Once the insurer learns about the insured person’s family medical history, it will also underwrite the medical cover more cautiously. For example, if a prospective insured person’s father and elder brother have both had colorectal cancer, as both are direct relatives, the insurer will assess the prospective insured person as having a higher likelihood of developing colorectal cancer. This may lead to more exclusions, a substantial increase in premiums, or even refusal of cover.
In fact, different insurers also have different underwriting standards when assessing hereditary diseases, the three major critical illnesses or diabetes. Some are stricter, some are more flexible, and the final outcome may differ. 10Life has helped many people with a family medical history try various insurers in the market and successfully secure cover. If you are concerned about this factor when buying medical insurance, you may wish to consult a 10Life insurance adviser.
In addition, if you are worried that developing a critical illness yourself may affect your children’s ability to buy insurance, parents should take out cover for their children as early as possible while they are still healthy, to avoid rejection and prevent their right to buy insurance from being taken away.
Of course, even if a family member has suffered from a serious illness, it does not mean that other relatives will necessarily develop it, and it may also be preventable through lifestyle choices later on. Taking diabetes as an example, effective prevention starts with diet and lifestyle habits, such as reducing refined carbohydrates and sugar, avoiding smoking and alcohol as far as possible, exercising regularly, and keeping an eye on weight.
As for cancer, preventive measures generally include eating high-fibre foods, reducing intake of red and processed meat, avoiding smoking and alcohol, exercising regularly, managing weight, and undergoing regular cancer screenings and related examinations such as gastroscopy and colonoscopy.
Note: This article was last updated on 7 December 2022.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com


 Talk to 10Life on WeChat
