





10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong



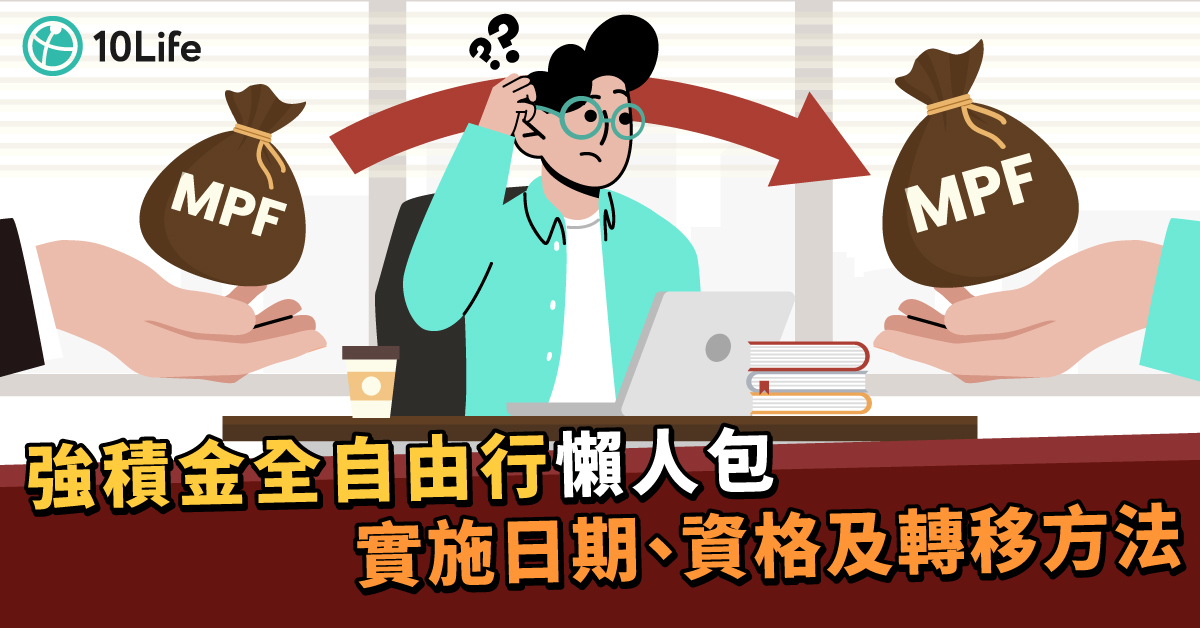
Good news for employees! Phase One of MPF “Full Portability” will take effect on 21 December 2026, and is expected to benefit about 1 million employees! In the past, employees could transfer only the MPF accumulated from their own mandatory contributions during their current employment. Under the new arrangement, eligible employees can also transfer, in full, the MPF accumulated from their employer’s mandatory contributions to an MPF scheme of their own choice, giving them more control over their retirement savings.
But is everyone eligible to transfer? How many transfers are allowed each year? Do you have to transfer? And is another scheme necessarily better? 10Life, a one-stop insurance platform, explains the differences between Full Portability and semi-portability, who can apply, how to transfer through the eMPF Platform, and what to watch before you transfer.
What is MPF “Full Portability”? How does it differ from “semi-portability”?
Every month when wages are paid, both employees and employers make MPF contributions. But did you know that the MPF you contribute and the MPF your employer contributes have always been subject to different transfer limits?
The MPF “semi-portability” arrangement launched in 2012 — officially the Employee Choice Arrangement (ECA) — only allows employees, once in every calendar year, to transfer the MPF accumulated from their own mandatory contributions during their current employment to a scheme of their choice. The portion from employer mandatory contributions has to stay in the MPF scheme chosen by the employer.
The “Full Portability” arrangement introduced in 2026 extends the right to transfer to the employer mandatory contribution portion as well. In other words, eligible employees can not only choose a scheme to manage their own contributions, but can also transfer the MPF accumulated from their employer’s contributions to a scheme they prefer.
MPF “semi-portability” vs “Full Portability”
| Comparison item | Semi-portability | Full Portability (Phase One) |
|---|---|---|
| Employee mandatory contributions under current employment | Can be transferred | Can be transferred |
| Employer mandatory contributions under current employment | Cannot be transferred by the employee | Can be transferred if you are eligible |
| Number of transfers each year | Once per calendar year for the employee contribution portion | The employer and employee contribution portions can be transferred separately, generally once each per calendar year |
| Transferred to which account? | A personal account in an MPF scheme of your choice | A personal account in an MPF scheme of your choice |
| Future employer contributions | Continue to be paid into the original scheme | Continue to be paid into the original scheme |
It is worth noting that “Full Portability” is meant to give employees more choice. It does not mean you can withdraw your MPF early, nor does it mean your employer will in future pay contributions directly into the MPF scheme you choose.
The reason is linked to the abolition of the MPF offsetting arrangement on 1 May 2025.
Although the Government has abolished MPF offsetting, if an employee began their current job before 1 May 2025, the employer may still, under transitional arrangements, use part of the MPF accumulated from employer mandatory contributions to offset severance payments or long service payments for years of service before the offsetting arrangement was abolished.
The Government therefore needs to settle the relevant legal arrangements before Full Portability can be extended to this group of employees.
The Government expects to introduce the Phase Two amendment bill into the Legislative Council in mid-2027, but the official implementation date for Phase Two has not yet been announced. Mid-2027 does not itself mean you will be able to transfer from that time.
Who is eligible for MPF “Full Portability”?
Phase One of MPF “Full Portability” applies to employees whose current employment began on or after 1 May 2025, including those entering the workforce for the first time and those changing jobs. In other words, eligibility depends mainly on the start date of your current job, not on when you first joined the MPF.
Eligibility in different employment situations is as follows:
| Employee situation | Does Phase One apply? |
|---|---|
| First job after graduating in June 2025 | Applies |
| Started work in 2024 and changed to a new company in 2026 | Applies to employer mandatory contributions under the new job |
| Joined a new company on 1 May 2025 | Applies |
| Started work in 2024 and has not changed jobs since | Does not apply yet; wait for Phase Two |
An example:
Suppose Mr Chan joined Company A in 2024 and moved to Company B in 2026. Because his new job began after 1 May 2025, he is eligible for Phase One “Full Portability” and may transfer the MPF accumulated from employer mandatory contributions during his employment with Company B to an MPF scheme of his choice.
By contrast, if Mr Chan has been employed by Company A continuously since 2024, he will have to wait until Phase Two is implemented before he can transfer the employer mandatory contribution portion from his current job on his own.
It should be noted that even if you are not yet eligible for “Full Portability”, you can still, under the existing “semi-portability” arrangement, transfer the MPF accumulated from employee mandatory contributions during your current employment.
How much MPF can you transfer under Full Portability? How many transfers are allowed each year?
MPF “Full Portability” does not mean employees can transfer any amount they like. Transfers must follow the different arrangements for employer and employee mandatory contributions.
Eligible employees may transfer the MPF accumulated from both employer and employee mandatory contributions during their current employment to the same scheme of their choice, or transfer the two portions separately to different schemes.
In general, the employer and employee mandatory contribution portions may each be transferred in full once in every calendar year. Each transfer must move the entire accumulated MPF of the chosen portion; you cannot transfer only part of the amount.
| Type of MPF | Transfer arrangement |
|---|---|
| Employer mandatory contributions under current employment | Eligible employees may generally transfer the entire amount once per calendar year |
| Employee mandatory contributions under current employment | The entire amount may be transferred once per calendar year |
| MPF accumulated from previous jobs | Can be handled under the transfer arrangements that apply after leaving a job |
| Voluntary contributions | Subject to the governing rules of the individual MPF scheme |
If the governing rules of the original scheme allow it, the employer mandatory contribution portion may also be transferred more than once a year. The actual arrangement is subject to the rules of the relevant scheme.
How do you transfer MPF through the eMPF Platform?
The eMPF Platform has updated the relevant functions. Eligible employees can arrange a Full Portability transfer themselves through the platform, without applying via their employer. The transfer process has three main steps:
An MPF transfer is not completed instantly. The original scheme first has to sell the funds, and the new scheme then has to buy them again. There is generally an investment gap of one to two weeks during this period.
Because the money is not invested in funds during that time, if market prices rise you may end up selling low and buying high, which can affect investment returns. So before you transfer, besides comparing fund performance and fees, you should also watch the risk of market volatility.
Is MPF “Full Portability” worth using? Four factors to consider before you transfer
MPF “Full Portability” gives employees greater autonomy in choosing their MPF trustee and scheme. They can select funds that better meet their personal needs, and it can also help foster market competition, creating room for lower fund fees.
That said, transferring MPF does not necessarily mean higher investment returns. Mrs Ayesha Macpherson Lau, Chairman of the Mandatory Provident Fund Schemes Authority (MPFA), has reminded scheme members that MPF is a long-term investment, and that employees should avoid transferring “for the sake of transfer” or making frequent transfers.
Before deciding whether to transfer, consider the following four factors:
Different MPF schemes offer different types of funds and investment strategies. You should understand a fund’s investment approach and risk level, and choose funds that meet your personal needs.
Besides short-term returns, you should also compare a fund’s long-term performance and risk. Past returns are not a guide to future performance, and you should not decide whether to transfer on recent returns alone.
Fund fees affect long-term investment returns. You should compare the fund expense ratios and related charges of different schemes, while also considering investment performance and risk.
Employees at different life stages may have different risk tolerance and investment objectives. You should choose a suitable investment strategy according to your age, expected retirement time and personal needs.
If your current scheme already meets your personal needs, there is no need to transfer immediately just because Full Portability has been introduced.
MPF is mainly intended to provide a reserve for retirement, and can generally be withdrawn only at age 65. Early withdrawal is allowed only if you meet specific statutory conditions. If you want to plan short- to medium-term savings for marriage, buying a home or other life goals, you may also consider other savings tools besides MPF, such as short-term savings insurance. Some USD savings insurance plans mature in 5 years, with a guaranteed internal rate of return (IRR) in year 5 of up to 5.03%, subject to specified contribution and application conditions. Before you apply, pay attention to the lock-in period, surrender losses and exchange-rate risk.
Want to know more about which short-term savings insurance plans offer higher returns? See the 2026 comparison of USD short-term savings insurance, or contact a 10Life insurance consultant via WhatsApp to find out about options that fit your personal savings goals.
MPF “Full Portability”: FAQs
No. Phase One takes effect on 21 December 2026 and applies to employees whose current employment began on or after 1 May 2025. Employees who started their current job earlier and have not changed jobs since will have to wait for the Phase Two arrangements, but they can still transfer the employee mandatory contribution portion under the “semi-portability” rules.
Eligible employees may transfer, in full, the MPF accumulated from employer mandatory contributions during their current employment. The transfer of employer voluntary contributions is subject to the rules of the individual scheme.
The employer and employee mandatory contribution portions under current employment may generally each be transferred in full once in every calendar year. If the scheme rules allow it, the employer contribution portion may also be transferred more than once a year. Unused annual transfer entitlements cannot be carried forward.
Yes. Eligible employees may exercise their 2026 transfer right from 21 to 31 December 2026, and may exercise the new year’s transfer right again from 1 January 2027, without waiting 12 months. That said, frequent transfers should be avoided, so as not to increase the investment gap and the risk of market volatility.
No. Full Portability is not a compulsory transfer arrangement. If the fund choices, fees and investment strategy of your current scheme already meet your personal needs, you can keep your MPF there and do not need to apply for a transfer.
No. Eligible employees can submit a transfer application themselves through the eMPF Platform, without going through their employer. After the transfer is completed, the employer will still continue to pay contributions into the original MPF scheme.
References
The information in this article is as at 19 November 2026. The actual arrangements are subject to the latest announcements by the MPFA and the eMPF Platform.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
10+ years in editing & copywriting. I love solving puzzles — now my goal is making insurance jargon simple. Let's decode policies and learn together.
10+ years in editing & copywriting. I love solving puzzles — now my goal is making insurance jargon simple. Let's decode policies and learn together.
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com


 Talk to 10Life on WeChat
