
false
Category
Author
Search for Articles
Trending Keywords
Category
Author
Search
Category
Author
Search
Medical
Editor's Pick

Medical insurance: Worried your claim won’t be paid? Is it a pre-existing condition? How long is the waiting period?

2018-11-29 3min read
blog-Medical-Insurance-Pre-existing-Conditions-and-Waiting-Period-kv.png
One day, I received a call from a friend: “I am going to undergo surgery. I have not bought medical insurance, but I want to buy some now. I do not know how to compare the policies.”
“However, you already know that you have an illness. Even if you buy medical insurance now, it will not cover this surgery.” My words immediately dampened my friend’s spirits…
When taking out medical insurance, no one wants to pay premiums without receiving any payout or face numerous difficulties when making a claim. Therefore, we need to understand two important concepts: first, pre-existing conditions; and second, the waiting period.
 
Pre-existing conditions are not covered
Medical insurance policies available on the market do not cover conditions that existed before the policy was taken out. In other words, conditions that were diagnosed, had obvious symptoms, or for which the insured had received relevant medical advice or treatment before taking out the policy are not covered. In the case above, my friend clearly wanted to buy insurance only after learning that they had an illness. Even if the insurance company accepted the application, it would not cover this surgery. It is worth noting that the upcoming Voluntary Health Insurance Scheme requires insurers to cover “unknown pre-existing conditions”. We shall wait and see.
 
Coverage takes effect after the waiting period
Suppose you are in good health, have no pre-existing conditions and have bought medical insurance, but happen to need hospitalisation immediately afterwards. Will the insurance company pay out? Consumers should note that medical insurance policies have a waiting period. If you fall ill and are hospitalised during the waiting period, the insurance company will not pay out. Coverage only takes effect after the waiting period has ended.
 
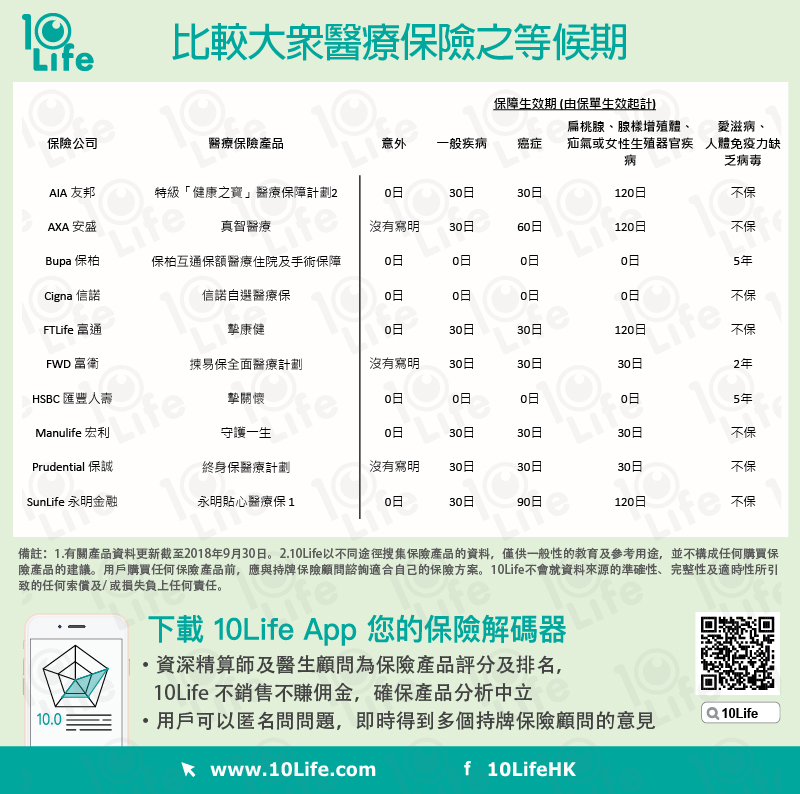
  • Some products state that if the insured is hospitalised due to an accident, coverage begins immediately once the policy takes effect. Therefore, the waiting period is 0 days.
  • However, for general illnesses, most medical insurance products have a waiting period, usually 30 days. Only a small number of products have a waiting period of 0 days.
  • For certain illnesses, some insurers require a longer waiting period (than 30 days), for example:
  •  
    • Cancer: the waiting period for AXA TrueCare Medical is 60 days, while the waiting period for SunHealth Medical Care is 120 days
    • Tonsils, adenoids, hernias or diseases of the female reproductive organs: AIA, AXA, FTLife and Sun Life’s mainstream medical products have a waiting period of 120 days
    • Acquired immune deficiency syndrome (AIDS) or infection with the human immunodeficiency virus (HIV): most products treat these as exclusions, while the few products that provide cover impose a waiting period of 2 to 5 years
 
The following is a comparison of the waiting periods for various mainstream medical insurance products:


Once the waiting period has passed, is it easy to make a Claim?
Generally speaking, if you are hospitalised shortly after taking out a policy, making a claim may be somewhat difficult because the insurance company has reasonable grounds to suspect that the condition was pre-existing. It may need time to investigate, and the claims process may take longer. For example, if the insured submits a claim for cancer treatment during the first year of the policy, the insurance company is very likely to conduct a thorough investigation into whether the insured misrepresented, omitted or concealed any information about their health. If the insured is found to have breached the principle of utmost good faith, the insurance company may refuse to pay the claim.
 
Finally, we would like to remind readers that when completing the health declaration form during the application process, they must report all information truthfully to avoid complications when making a claim in the future.
 
If you are interested in mainstream medical insurance products, you can browse 《Product Decoder Comparison》 on our website to view analyses of more products.


If you have any insurance-related questions, you can “Ask a question anonymously” on the 10Life website and App to receive opinions from multiple licensed advisers immediately. 

This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

10Life Logo
10Life Editorial Team

Our team of professional content researchers focussing on insurance

Disclaimer

10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com

Whatsapp icon
Whatsapp icon
WeChat icon
WeChat icon
Enquiry icon Close icon
Back To Top
Whatsapp icon
Whatsapp icon
WhatsApp