




10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


Savings insurance combines savings with life protection and may include both guaranteed and non-guaranteed returns. Plans can generally be divided into short-term and long-term savings insurance based on policy term and financial goals.
Short-term savings insurance typically focuses on guaranteed returns over 1 to 8 years, while long-term plans focus more on projected returns and long-term wealth accumulation.
10Life compares 190+ savings insurance plans from 20 + insurers, including guaranteed IRR, projected IRR, breakeven period and dividend fulfilment ratios. Ratings are developed by our actuarial team and are independent of insurers.
Policy term
Premium payment
Main financial goals
Return structure
What to compare
Currency options
Liquidity
Early surrender risk
Additional features
May suit
Around 1–8 years
Often single premium or paid over 1–2 years
Mainly guaranteed returns
Grow short-term savings and put idle cash to work
Guaranteed IRR, breakeven period, minimum premium and early surrender terms
Shorter commitment period
Surrender value may be significantly lower than premiums paid during the early policy years
Generally fewer
People with idle cash who may need the money again within several years
10 years or more; some policies provide lifelong coverage
Single premium or regular premiums, sometimes over 20 years or more
Guaranteed returns + non-guaranteed bonuses
Education fund, retirement planning and wealth transfer
Projected IRR, breakeven period, dividend fulfilment ratio and insurer financial strength
Mainly HKD and USD; some multi-currency plans allow currency conversion after policy inception
Funds are generally committed for longer
Surrender value may be significantly lower than premiums paid during the early policy years
Some plans offer policy split, change of insured and multi-currency options
People with long-term financial goals who can keep their money committed for longer
10Life savings insurance ratings are developed by our actuarial team and use different criteria for short-term and long-term plans.
For short-term savings insurance, 10Life mainly compares guaranteed IRR, while also considering the breakeven period and early surrender risk.
For long-term savings insurance, the assessment also considers projected returns, non-guaranteed return risk, dividend fulfilment performance and the insurer’s financial strength.
This helps users compare plans with similar savings periods and financial goals, rather than relying only on headline maturity values.
Compare guaranteed IRR and projected IRR rather than only looking at the amount you may receive at maturity. Even with the same premium and policy term, annualized returns can differ between plans.
If you may need the money within three to five years, a long-term plan with a lengthy breakeven period may not be suitable, as early surrender could result in a loss. Keep enough liquid savings for unexpected expenses before committing, also need to understand the risk preference for savings insurance.
For short-term plans, guaranteed IRR is a key comparison metric. For long-term plans, you should also consider projected IRR, dividend fulfilment ratio and the insurer’s financial strength, as part of the return may be non-guaranteed.
1–2 years
3 years
5 years
8 years or more
Highest liquidity, mainly guaranteed returns, but generally lower annualised returns.
A balance between liquidity and returns.
Guaranteed IRR is generally higher, with more products available in the market.
Closer to long-term plans; some include non-guaranteed bonuses.
You may need the money within one or two years.
You do not need the money immediately but want to avoid a long lock-in period.
You are unlikely to need the money within five years.
You can accept a longer commitment for higher potential returns.
10Life savings insurance ratings are developed by our actuarial team and use different criteria for short-term and long-term plans.
For short-term savings insurance, 10Life mainly compares guaranteed IRR, while also considering the breakeven period and early surrender risk.
For long-term savings insurance, the assessment also considers projected returns, non-guaranteed return risk, dividend fulfilment performance and the insurer’s financial strength.
This helps users compare plans with similar savings periods and financial goals, rather than relying only on headline maturity values.
The minimum return guaranteed under the policy terms, regardless of market performance.
Returns that may include annual dividends, reversionary bonuses or terminal bonuses, depending on the insurer’s investment performance and bonus policy.
The combined value of guaranteed and non-guaranteed returns. It is an estimate, not a guaranteed return.
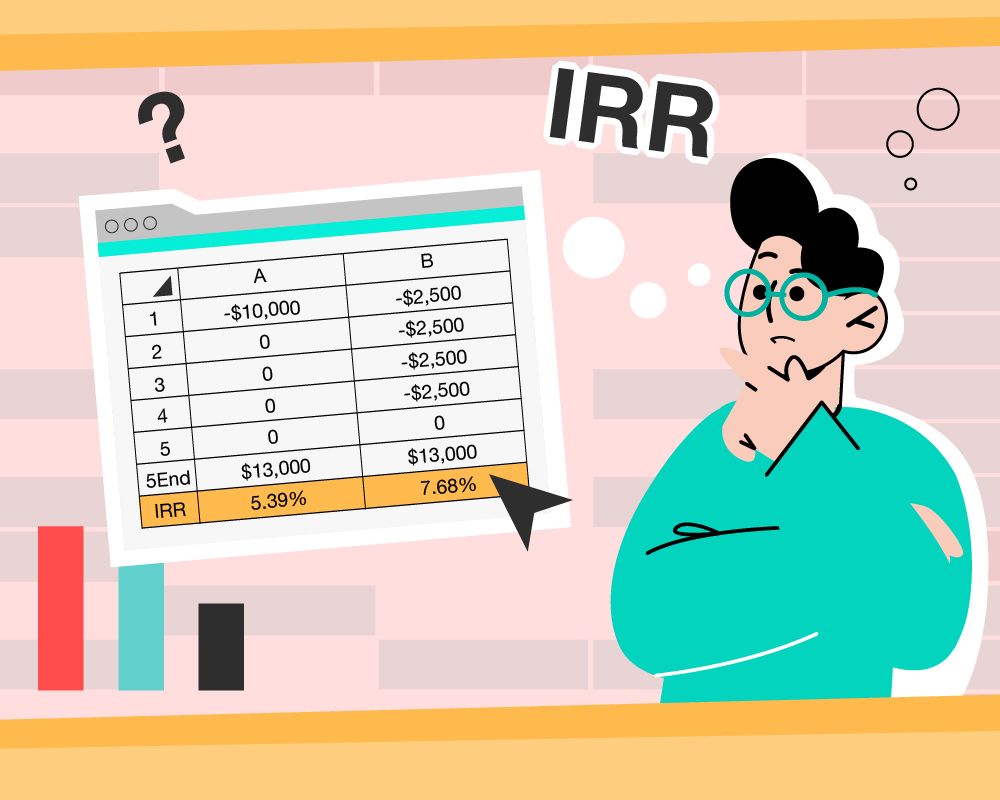
The annualised return based on the amount and timing of cash flows. Compare IRR using the same currency and target year.
The amount you receive when surrendering a policy. In the early years, it may be lower than the premiums paid.
The point when the surrender value reaches the total premiums paid. A longer breakeven period means your money is locked in for longer.
Dividend fulfilment ratio shows how actual non-guaranteed bonuses compare with the amounts originally illustrated, and can be used as a reference for past bonus performance.
The value of stocks and funds rises and falls with the market, and their returns are not guaranteed.
With savings insurance, the guaranteed portion of the return is set out in the policy contract. Once the guaranteed cash value has reached the breakeven point, that guaranteed cash value is not reduced simply because financial markets fall.
The insurer manages the underlying assets, so policyholders do not need to trade investments or follow market movements on a day-to-day basis.
Regular-premium savings plans require policyholders to contribute a fixed amount over a specified period, which can help people maintain a more structured savings habit.
In addition to building policy value, savings insurance generally includes a death benefit, combining savings with a basic level of life protection.
Products range from one-year plans to lifelong policies, with options ranging from single premiums to premium payment periods of 20 years or more.
If you have money that is not needed in the short term, savings insurance can be an option for earning more predictable returns. Compare IRR, breakeven period and policy term to find a plan that matches your expected use of the money.
Long-term savings plans can help build education fund and prepare for other major life goals such as marriage or home ownership. Some plans also offer staged withdrawals or policy splitting for greater flexibility.
Savings insurance includes a guaranteed component, which can provide greater certainty than market-linked investments. However, higher guaranteed returns may come with lower potential returns.
The insurer manages the underlying assets, so you do not need to monitor markets or rebalance a portfolio yourself. You mainly decide how much to contribute and for how long.
Regular-premium plans follow a fixed contribution schedule, which can help build a more consistent savings habit over time.
In Hong Kong, terms such as “savings insurance”, “savings plan” and “savings life insurance” are often used to describe similar products — life insurance policies with a savings element.
The terminology may differ between banks and insurers, but the basic structure is similar: you pay premiums, the insurer manages the assets, and the savings insurance plan builds guaranteed and/or non-guaranteed cash value while providing life protection.
It depends on your needs.
If you want to set aside money for several years and prefer a guaranteed component, a guaranteed savings insurance plan may be worth considering.
If your priority is higher return potential and you are comfortable with market volatility, other investment options may be more suitable.
The key is to balance risk, return and liquidity. You should also keep enough cash for emergencies to avoid having to surrender the policy early and potentially make a loss. You can also review what to consider before buying savings insurance.
The key consideration is when you expect to need the money.
If you may need it within five years, short-term savings insurance may offer more flexibility. For goals that are 10 years or more away — such as overseas education, retirement or wealth transfer — a long-term savings insurance plan gives your money more time to grow through compounding and non-guaranteed bonuses.
IRR reflects both the amount and timing of your premium payments and returns.
When comparing savings insurance plans, use the same policy currency and the same target year. Comparing a USD policy directly with an HKD policy, or a 5-year IRR with a 20-year IRR, would not be a like-for-like comparison.
It varies significantly by product.
Some short-term savings insurance plans may break even within one to two years, while long-term policies can take more than 10 years.
Before buying a plan, check its guaranteed and non-guaranteed cash values at the point when you are likely to need the money.
Yes. During the early policy years, the surrender value may be significantly lower than the total premiums paid.
Some insurance savings plans can therefore result in a substantial loss if surrendered very early. Consider your cash flow and short-term liquidity needs before committing to a policy.
Fixed deposits generally have shorter terms, often from one month to 12 months. Early withdrawal usually means losing interest rather than principal.
Higher deposit rates may also come with conditions such as new-fund or new-customer requirements, and the rate available when the deposit matures may change.
Short-term savings insurance can lock in returns for several years and usually includes life protection, but early surrender may result in a loss of principal. Which is more suitable depends on your time horizon, liquidity needs and return expectations.
Savings insurance is mainly designed to build up wealth over time. You may access the policy value at maturity, at a chosen target year or through withdrawals.
An annuity is mainly designed to provide regular income, usually from a specified age for a fixed period or for life.
In simple terms, saving insurance focuses more on accumulation, while an annuity focuses on regular income. The two can also be used together for retirement planning.
Standard savings insurance is generally not tax-deductible in Hong Kong.
Only qualifying products, such as Qualifying Deferred Annuity Policies (QDAP) and eligible Voluntary Health Insurance Scheme (VHIS) policies, may qualify for tax deductions under the applicable tax rules.
A long-term savings insurance plan often includes non-guaranteed bonuses as part of its projected return.
The actual amount paid may vary depending on the insurer’s investment performance, bonus policy and market conditions. Projected returns are therefore estimates, not guaranteed outcomes.
You can also review the insurer’s dividend fulfilment ratio to see how its actual non-guaranteed dividend or bonus payments have compared with previous illustrations.


 Talk to 10Life on WeChat