





10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong



Reader Miss Xia (pseudonym) previously told 10Life that in 1997, when her mother fell ill, the insurance agent recommended that her father buy a whole life insurance policy with an attached level term life benefit. Recently, Miss Xia accidentally discovered that the whole life policy her father had been paying into for many years had a surrender value that was in fact far lower than the premiums paid. What exactly was going on?
The matter spans many years, and we have tried to piece together the full story...
1993: Miss Xia’s father suffered a stroke and required brain surgery.
1995: Miss Xia’s aunt joined the agency of a major insurance company. She persuaded Miss Xia, her elder sister and their mother to each purchase insurance products. Shortly afterwards, the aunt left the company, and the three policies were then handled by another agent, Ms Wong (pseudonym).
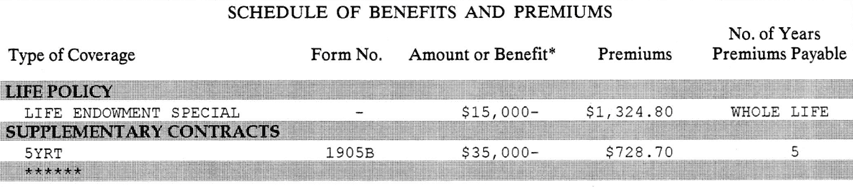
1997: Miss Xia’s mother was admitted to hospital for surgery. During the claims process afterwards, Ms Wong recommended that Miss Xia’s father purchase “Installment Savings Whole Life Insurance” and “Five-Year Term Life Insurance”.
2022: Miss Xia helped her father manage his policy and logged into his online account, where she accidentally found the annual statements and projected values table from recent years. The table showed that after paying into the policy for 25 years, her father’s surrender value (US$24,048) was in fact far less than the total premiums paid (US$33,120).
Mr Xia’s Policy Expected Value Summary (USD)
Policy Year End | Total Premiums Paid | Surrender Value | ||||
Guaranteed Amount | Non-guaranteed Amount | Total | ||||
Guaranteed Cash Value (A) | Other Guaranteed Amount (B) | Cumulative Annual Dividend+ | Terminal Dividend (D) | |||
74 | 33,120 | 7,440.00 | 16,608 | 0 | 0 | 24,048 |
75 | 33,445 | 8,055 | 16,608 | 498 | 0 | 25,161 |
76 | 35,770 | 8,700 | 16,608 | 1,011 | 0 | 26,320 |
77 | 37,094 | 9,405 | 16,608 | 1,540 | 0 | 27,553 |
78 | 38,149 | 10,155 | 16,608 | 2,084 | 0 | 28,848 |
79 | 39,744 | 8,730 | 18,858 | 2,645 | 0 | 30,233 |
80 | 41,069 | 9,285 | 18,858 | 3,290 | 0 | 31,433 |
81 | 42,394 | 9,870 | 18,858 | 3,955 | 0 | 32,683 |
82 | 43,718 | 10,515 | 18,858 | 4,639 | 0 | 34,012 |
83 | 45,043 | 11,250 | 18,858 | 5,344 | 0 | 35,452 |
84 | 46,368 | 9,840 | 21,108 | 6,070 | 0 | 37,018 |
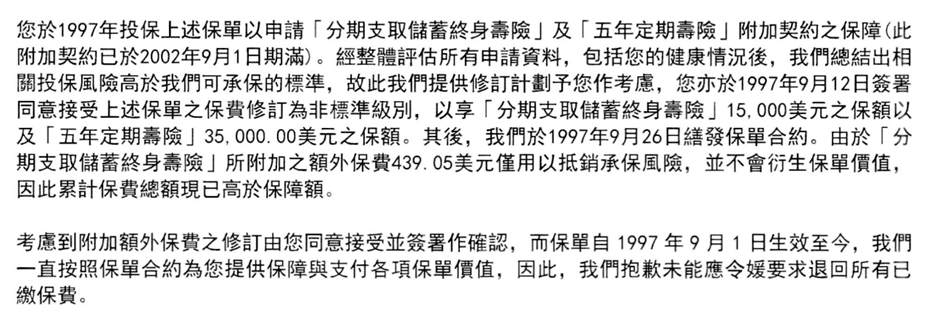
Accordingly, Miss Xia immediately enquired with the insurer and requested a refund of all premiums paid, but received the following reply from the insurer’s customer service department:
Case analysis:
1. According to the customer service reply, the premium for Mr Xia’s policy at the time of application was “substandard”, because the risk of the application was higher than the insurer’s acceptable standard. An additional premium loading of USD439.05 was therefore applied, and this amount would not accrue any policy value. In short, Mr Xia had previously suffered a stroke and was subject to a loading, meaning he paid a higher premium than others.
2. Upon reviewing the application documents, the medical declarations and supplementary application materials submitted at the time were all in English. The supplementary materials, written partly by hand and in a mix of Chinese and English, disclosed the relevant information and were signed by Mr Xia.
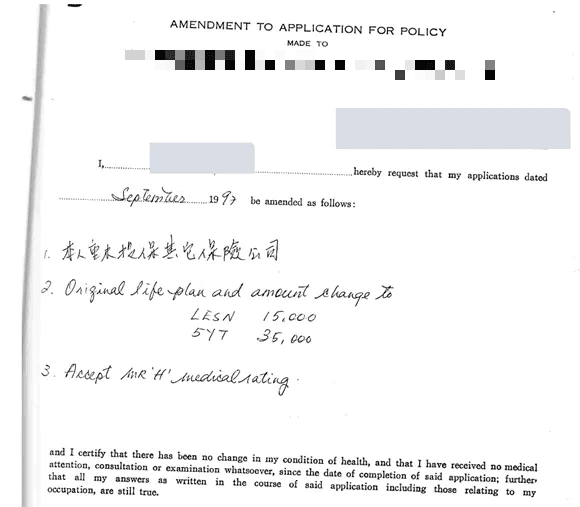
3. We are unable to verify whether Mr Xia clearly understood that a loading had been applied, given that the application took place many years ago. We would like to remind readers to pay particular attention to handwritten declarations when applying for insurance, and to sign only after confirming that they agree with the contents.
4. Was this policy completely worthless? In the policy’s inception year of 1997, the premium was USD2,053.5 and the death benefit was USD50,000, which was 24.3 times the total premium paid. However, as premiums continued to accumulate, the multiple of the death benefit relative to premiums paid continued to decline. By the 11th policy year, the death benefit was equal to the cumulative premiums paid. Any further premium payments would only result in greater losses. If Mr Xia had a reliable adviser reviewing the policy regularly, this issue might have been identified earlier and an earlier exit could have been made.
What should Mr Xia do now? Looking again at the recent policy projected values table, when Mr Xia was 74, the premiums paid already exceeded the death benefit by USD9,072. If he continued paying, by the age of 79 the gap would widen further to USD12,156 (excluding non-guaranteed dividends), and even if the full non-guaranteed dividends were paid, the gap would still increase to USD9,511. It therefore appears that there is no benefit in continuing to pay.
Miss Xia believes the insurer failed to provide a projected policy values table in the earlier years, allegedly concealing the fact that the long-term surrender value was lower than the premiums paid. This is because, years ago, the regulator did not require insurers to provide a projected policy values table.
However, Guidance Note 16 issued by the Insurance Authority in 2017 requires insurers to provide a benefit illustration for participating policies, showing projected performance information such as guaranteed and non-guaranteed benefits at different policy years, as well as their total. When taking out a participating policy, or the so-called savings insurance, you should pay attention to the benefit illustration, which shows the guaranteed breakeven year and the projected breakeven year.
Finally, if readers have any questions about their own policies, including medical insurance, critical illness insurance, or savings insurance policies with a term of more than 10 years, please feel free to contact us and email the relevant information to enquiries@10life.com. We will do our best to help answer your questions. If the case is selected and published, the reader will receive a HKTVmall shopping voucher worth HK$50 free of charge.
Note: This article was last updated on 7 June 2023.
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com


 Talk to 10Life on WeChat
